

Every Monday, I share my first take on 2 to 3 attractive ideas.
As usual, if you want me to dig deeper into an idea, vote for it. Use the poll at the end of this email.
Li Ning Company Limited (2331 HK)
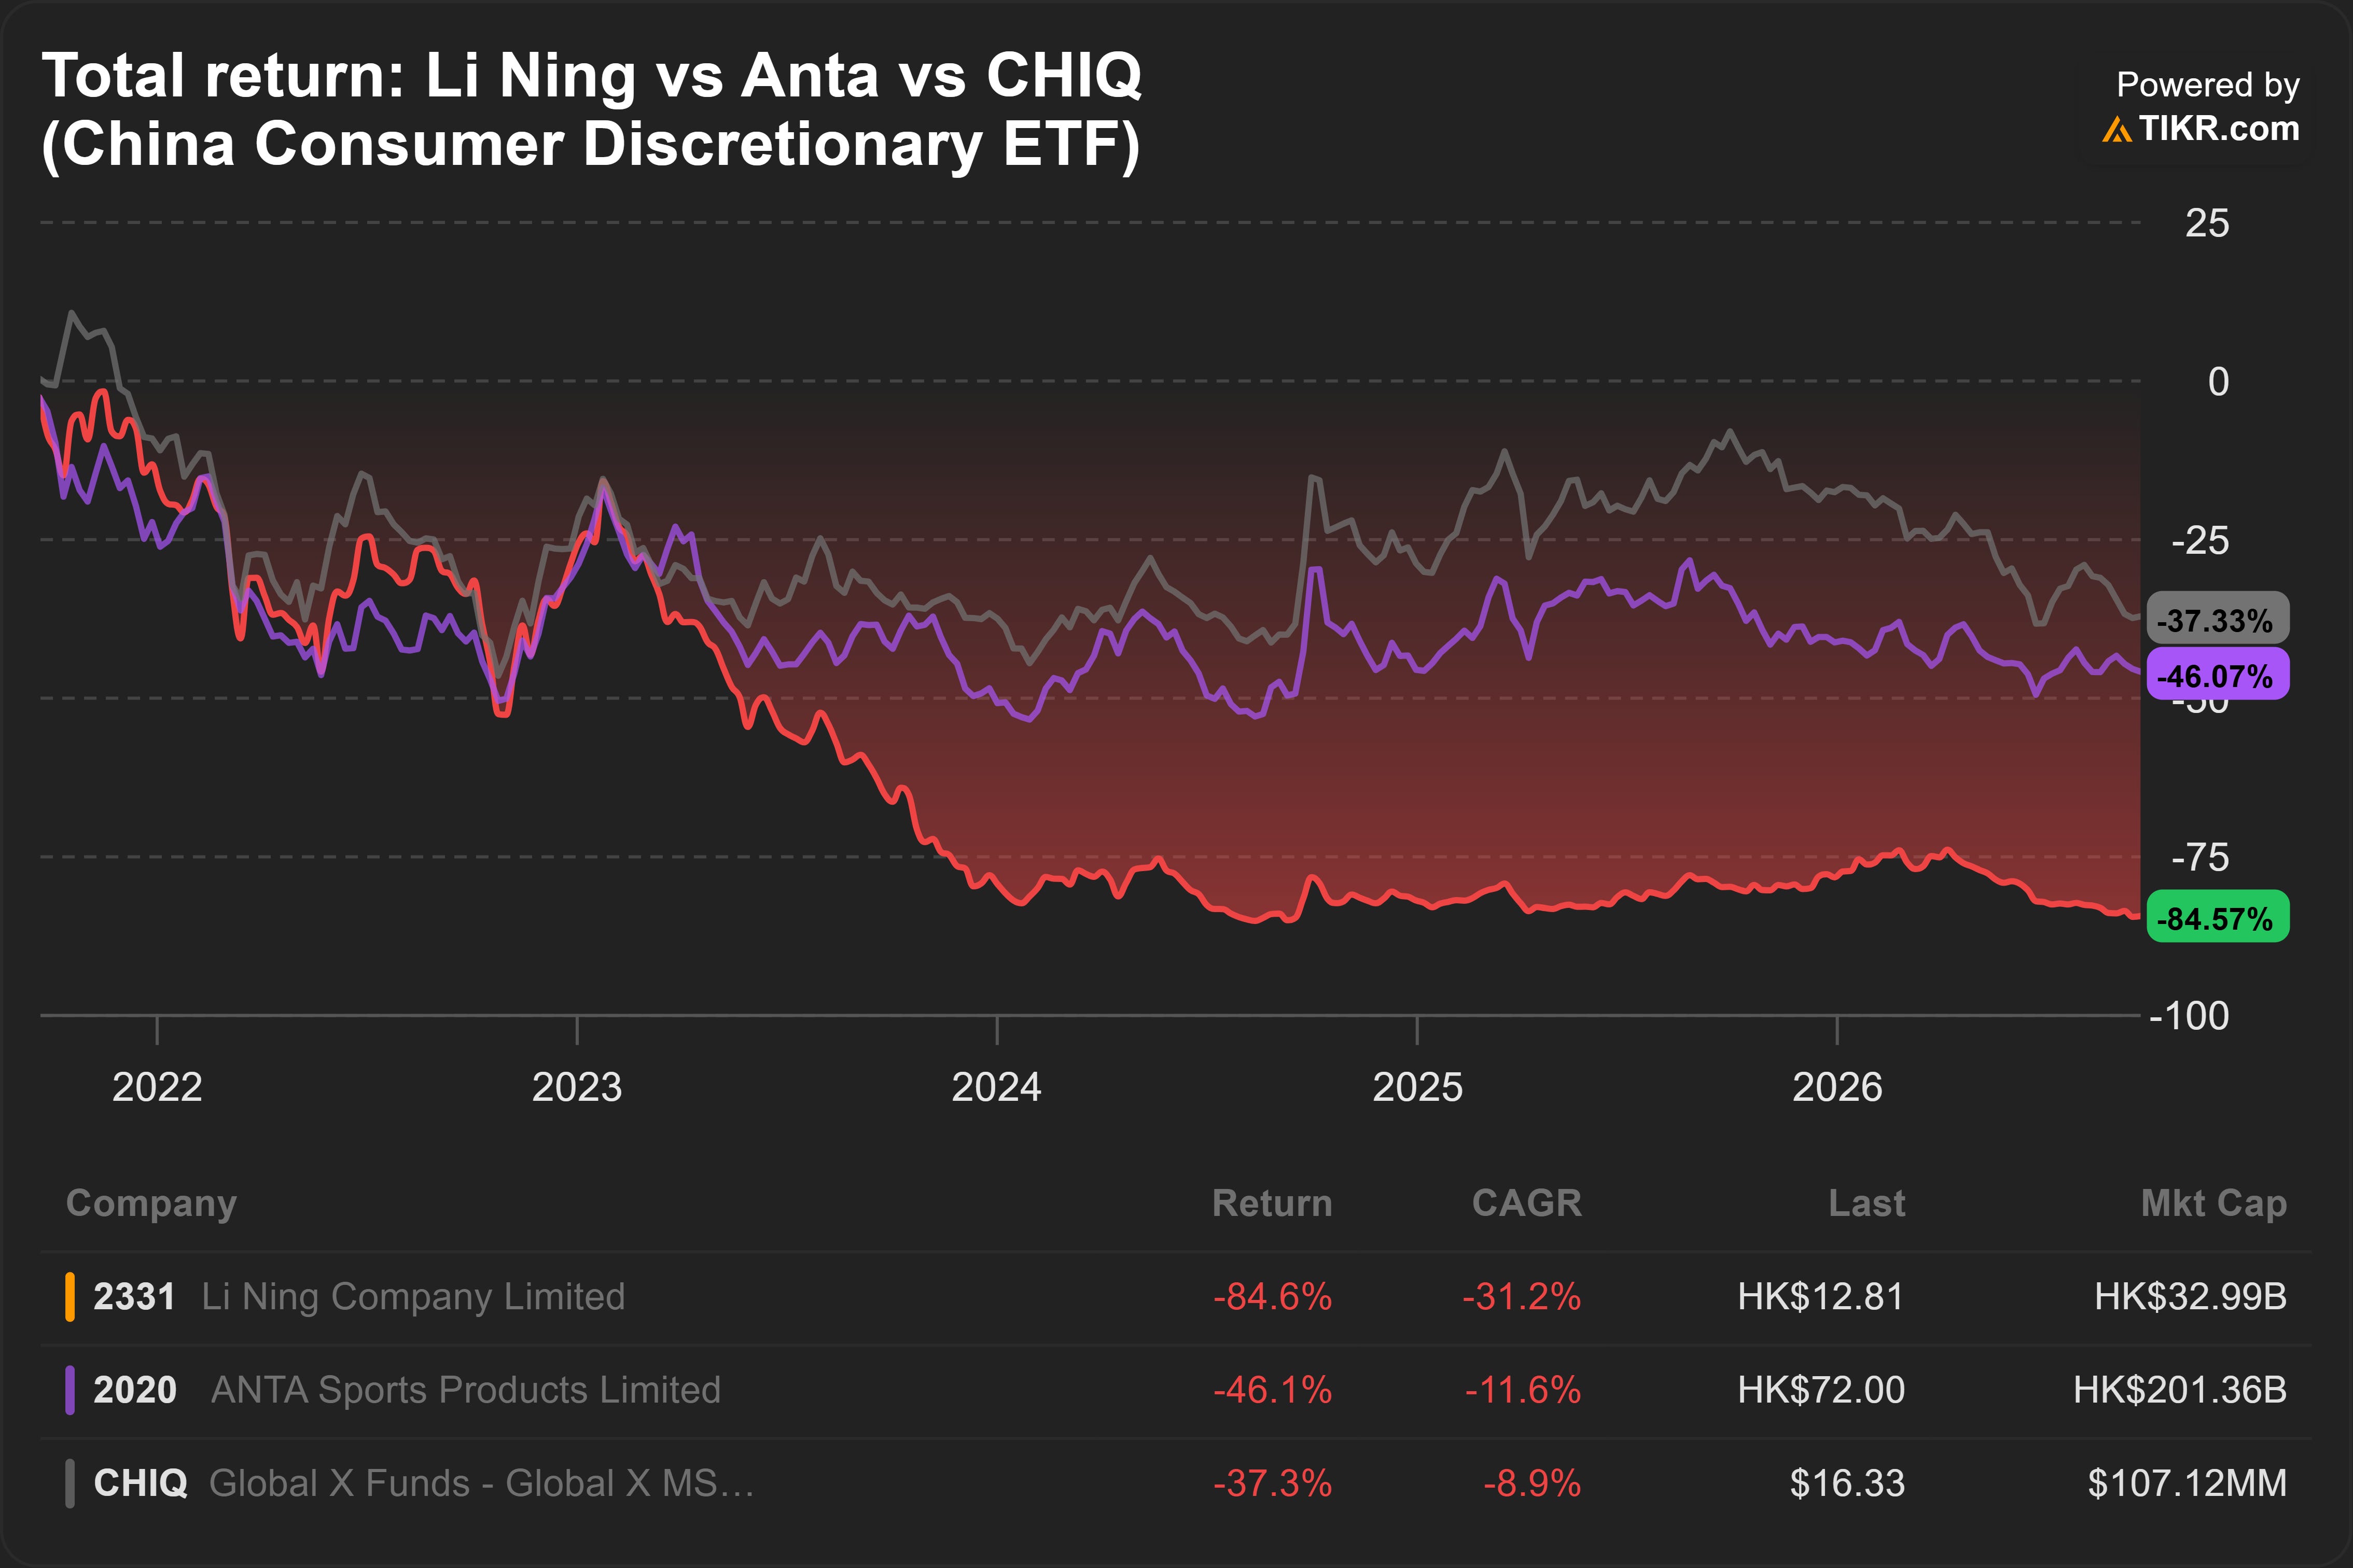
The market seems to be pricing in another long and severe downturn, like the one from 2011 to 2017. At that time, Li Ning overestimated demand and had to cut prices aggressively to clear excess inventory.
However, the current downturn will likely be less severe than expected. Inventory footnotes reveal a good business that’s much healthier than expected.
Furthermore, investors are overlooking the inflection point in Li Ning’s growth in international markets.
About (27 Sep 2026)
Share price: HKD 12.33
Market capitalisation: HKD 31,524 mn (USD 4,019 mn)
Enterprise value (EV): HKD 16,239 mn (USD 2,070 mn)
Average daily volume (ADV): HKD 318 mn (USD 41 mn)
NTM P/E: 9x
Li Ning sells sportswear under its own brand, mainly in mainland China.
It earned CNY 30 bn revenue in 2025 (+3% YoY):
49% footwear (+2% YoY)
42% apparel (+2%)
9% equipment and accessories (+13%)
Li Ning sells through these channels:
47% wholesale (+6% YoY)
30% e-commerce (+5%)
22% direct (-3%)
1% international (-20%)
Good business, temporary headwinds?
The current headwind will likely be less severe than expected. Compared to 10 years ago, inventory today is much healthier.
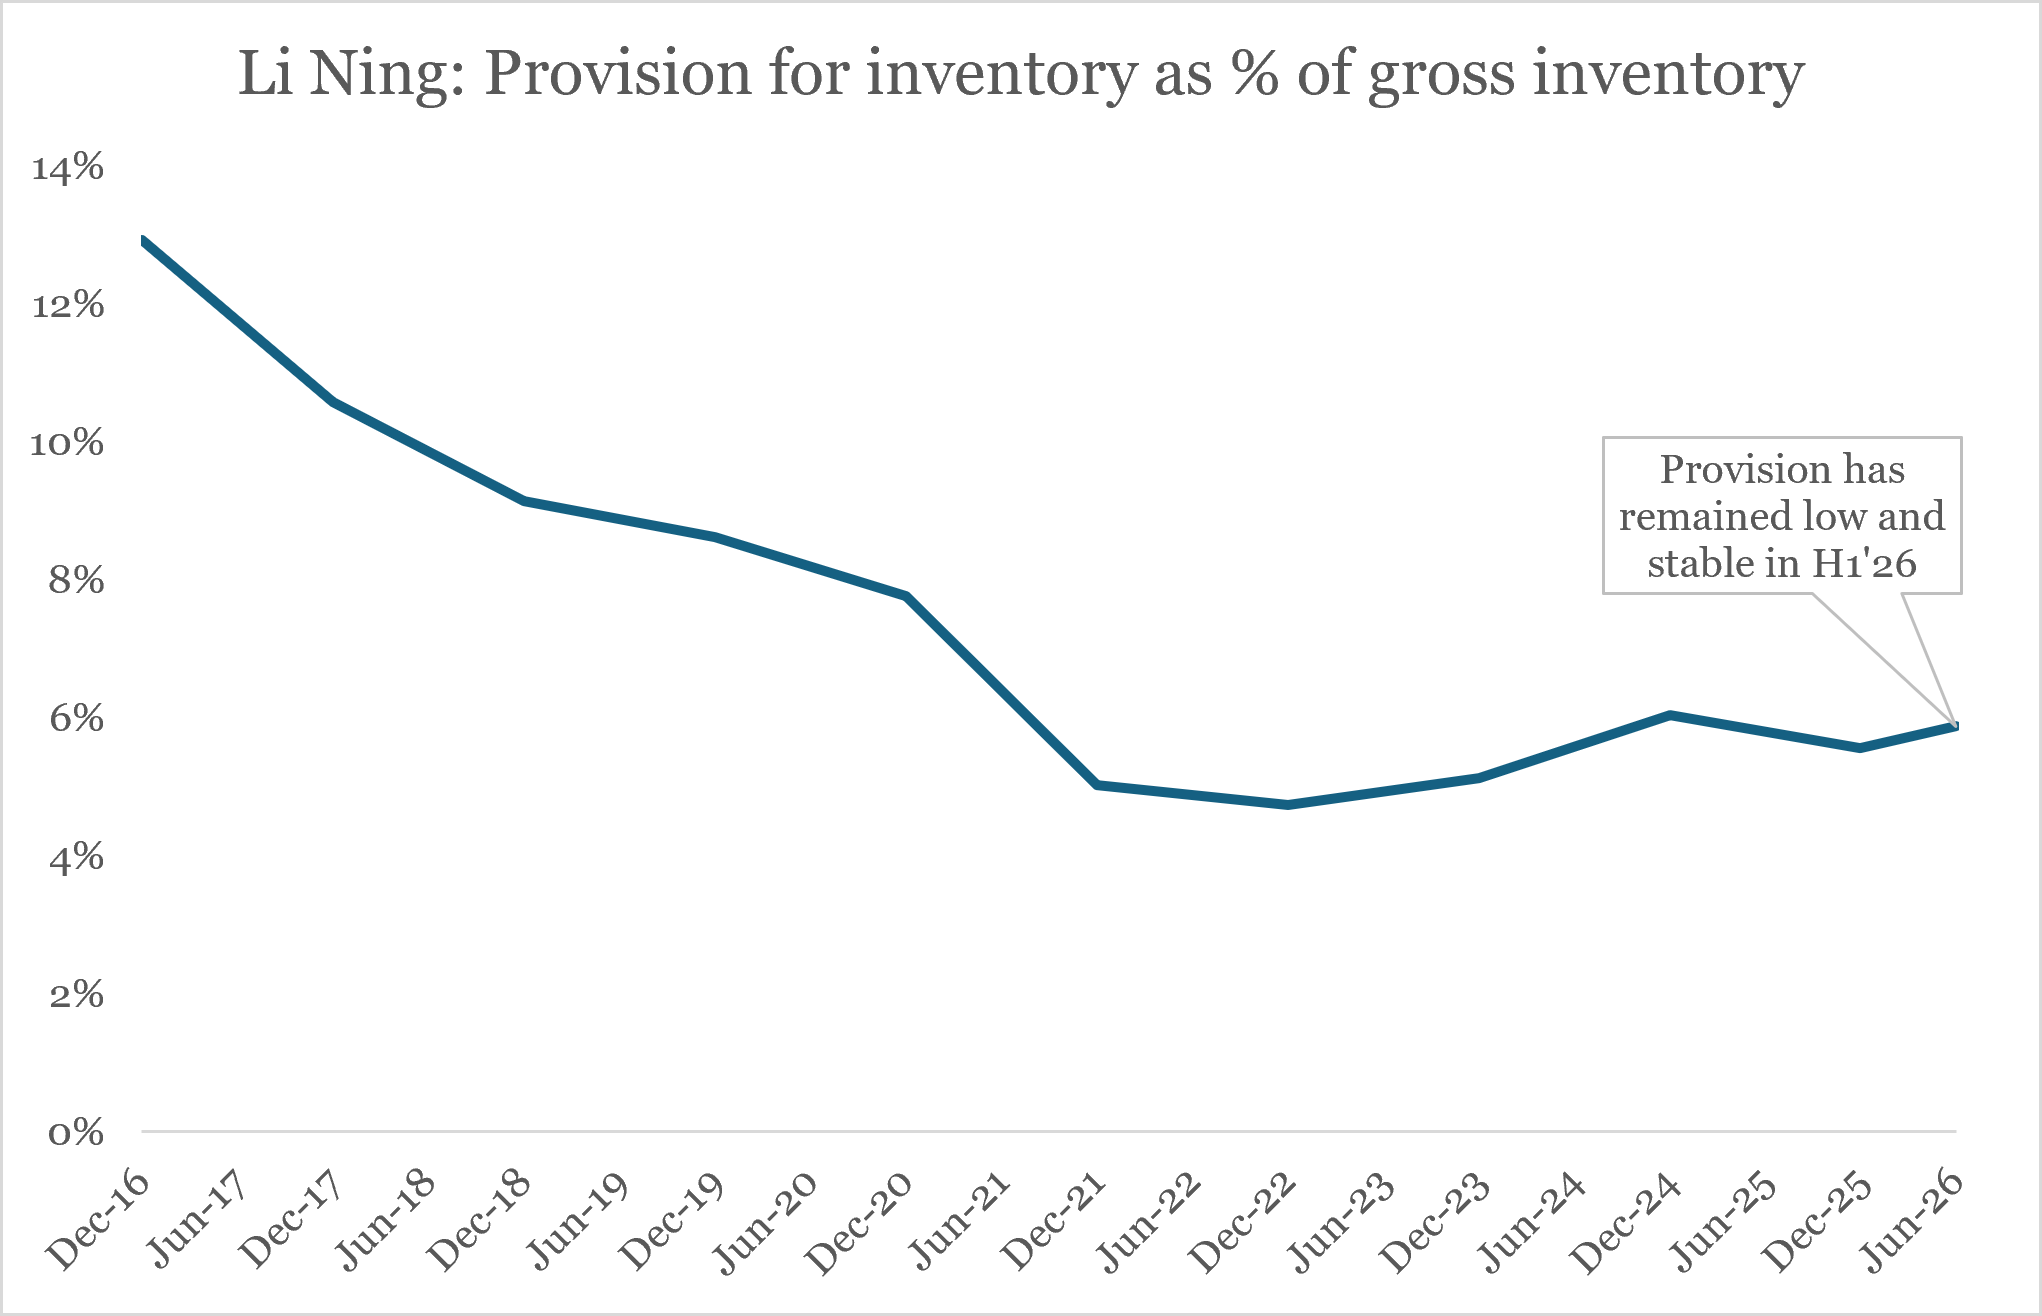
Provision for inventory write-down measures the percentage of inventory whose selling price has fallen below cost.
In H1’26, this remained low and stable at 5.9%. 10 years ago, it was 12.9%.
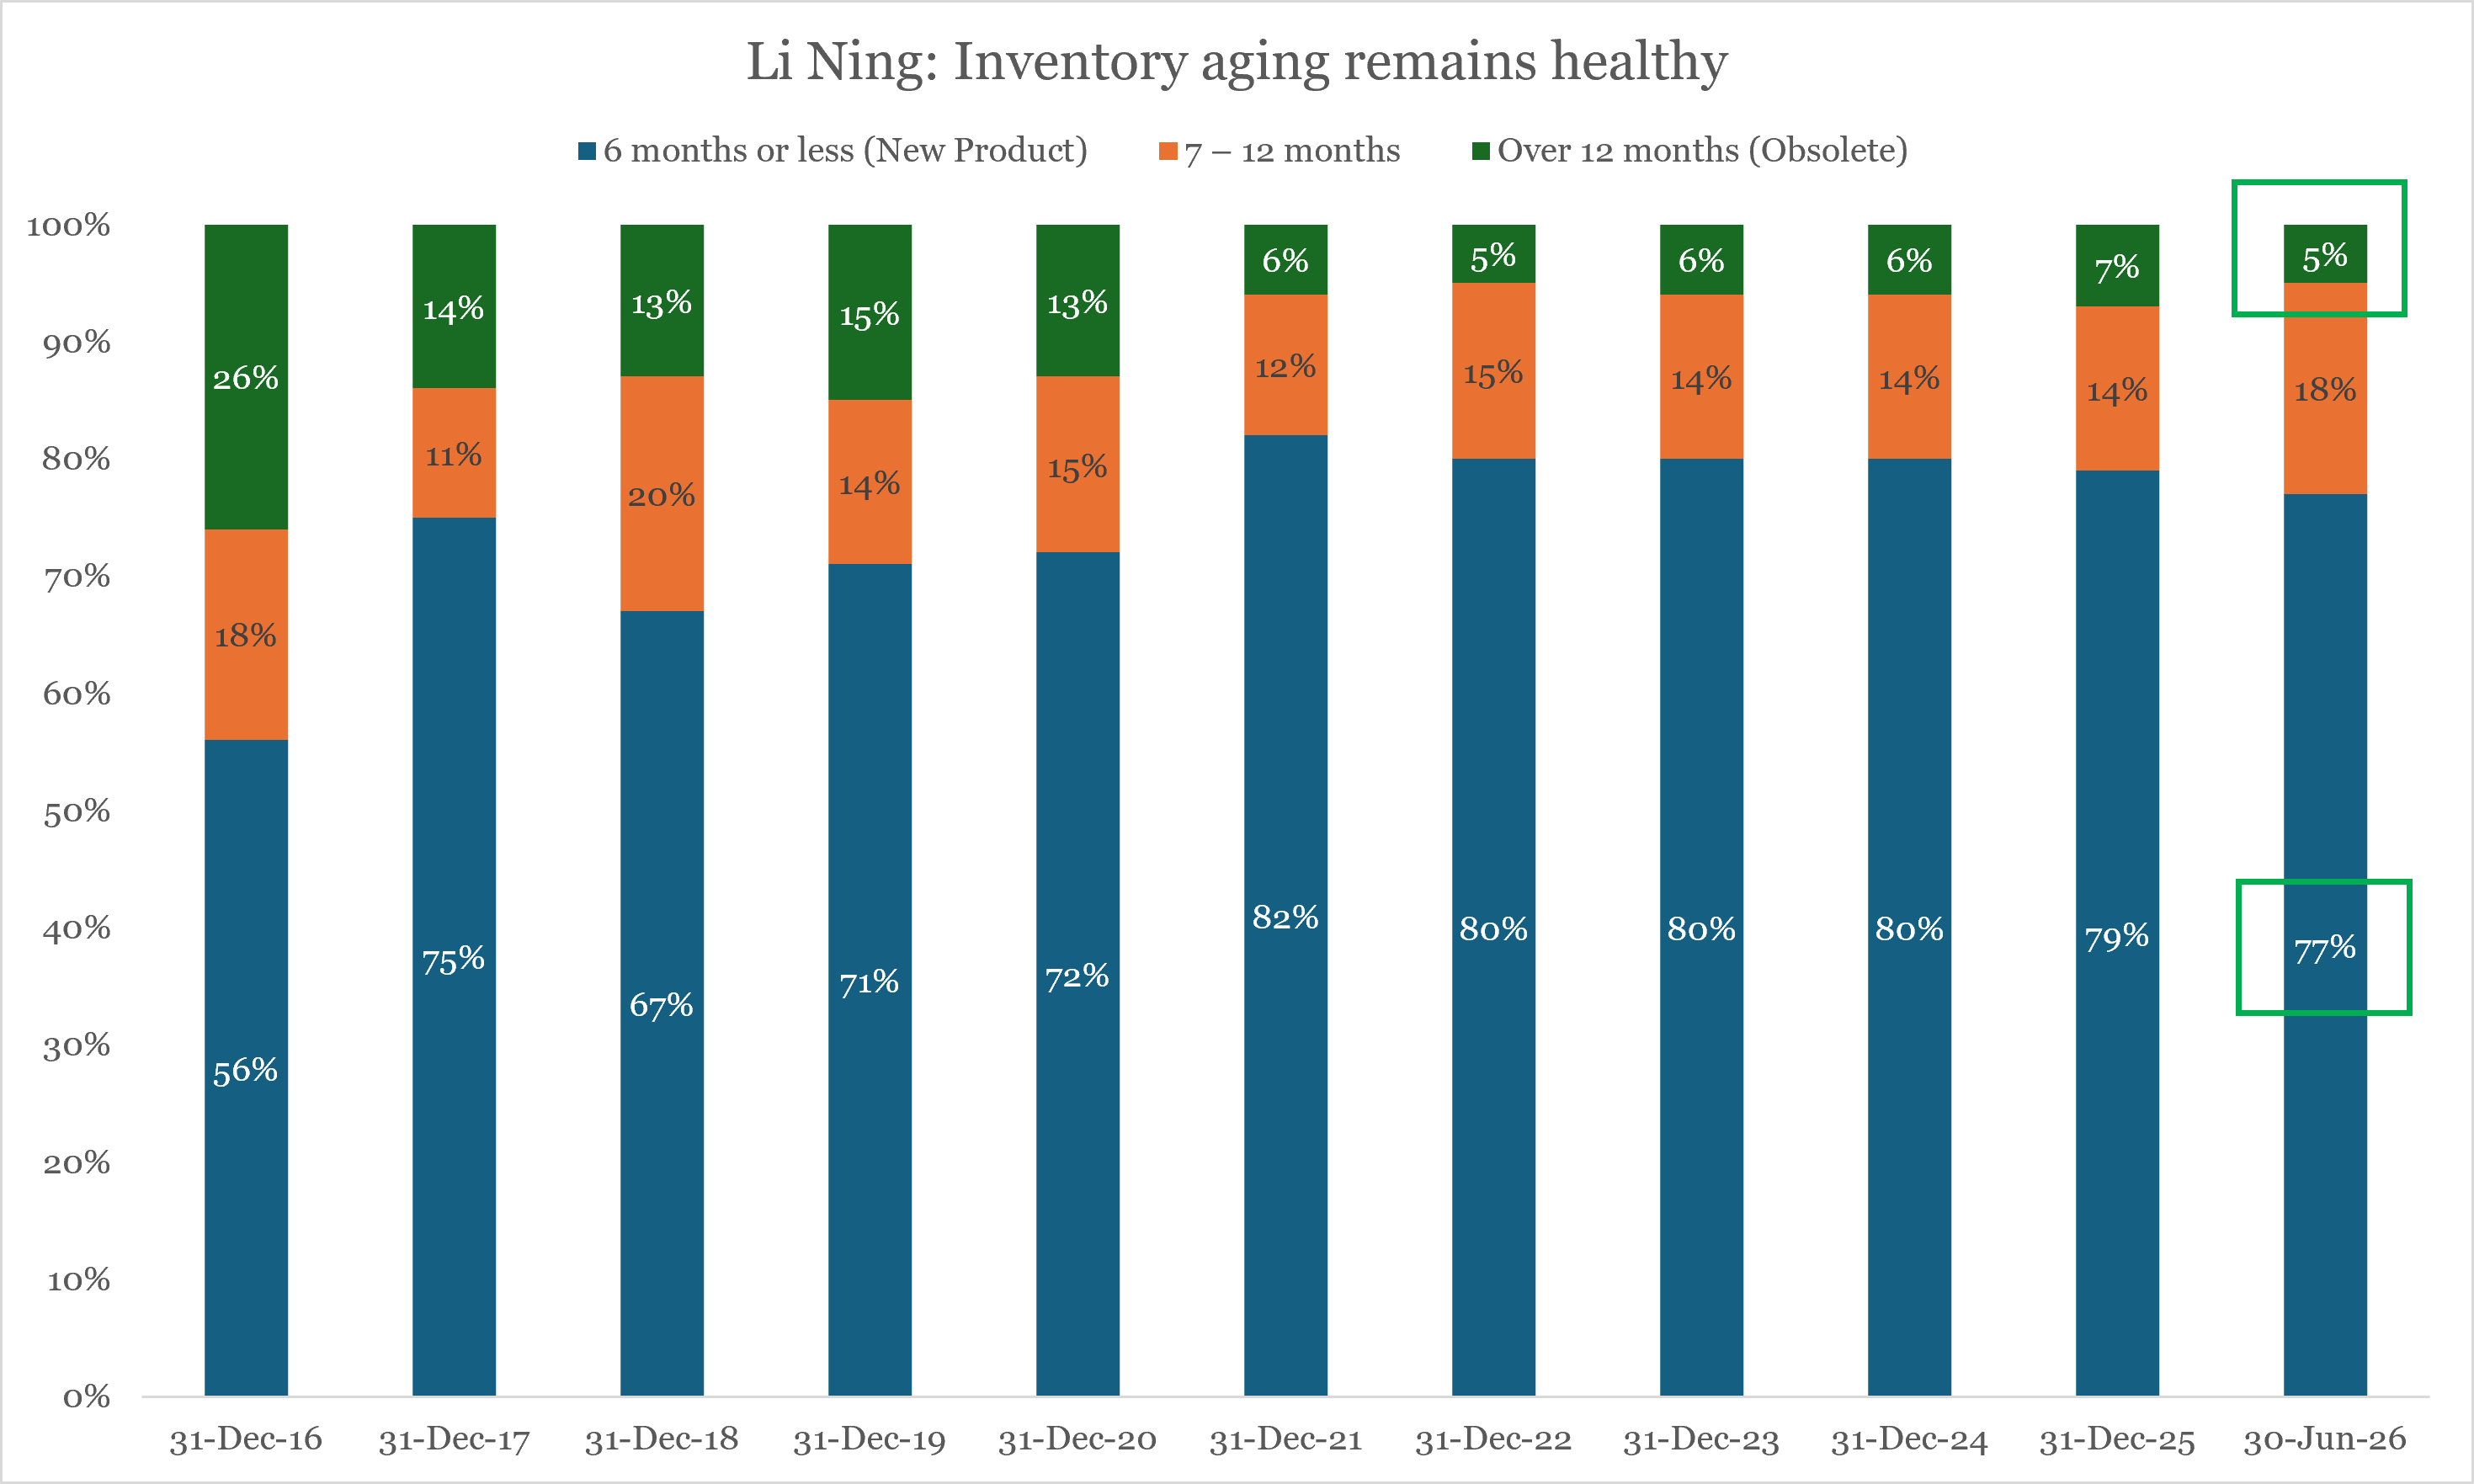
Inventory aging remains healthy in H1’26.
New products make up 77% of inventory, significantly higher than the 56% in 2016. Obsolete products remain near all-time low at 5%.
Under-recognised growth?
Investors are distracted by the near-term guidance cut. They are overlooking Li Ning’s long-term growth potential in international markets.
In October 2024, Li Ning formed a joint venture with HongShan (formerly Sequoia China).1
The JV’s purpose is to develop Li Ning’s business outside China. The agreement sets a target of USD 1 bn (CNY 6.7 bn) revenue by 2028. This is equivalent to ~ 22% of last twelve months’ revenue.
Potential takeover?
In March 2024, Reuters reported founder and CEO Li Ning was considering a privatisation.2 The shares were trading ~ HKD 22.00 per share and 14x NTM P/E.
Today, Li Ning’s valuation is much more attractive.
The founder is buying shares directly on the market. The most recent purchase was on 11 Sep 2026, at ~ HKD 12.92 per share.3
Factors to focus on
Risk of channel stuffing?
Further delays in recovery?
Dr. Martens plc (DOCS LN)
The market seems to be slow in recognising the recovery in DOCS.
Even though revenue declined -3% in FY2026, gross margin improved by +1.2 percentage points. Full-price sales grew strongly. Demand is recovering.
DOCS is making good progress in clearing excess inventory. Inventory days have fallen below median level since 2020.
I estimate the shares are trading at ~ 10% free cash flow yield on enterprise value.
About (25 Sep 2026)
Share price: GBP 0.68
Market capitalisation: GBP 649 mn (USD 860 mn)
Enterprise value (EV): GBP 862 mn (USD 1,143 mn)
Average daily volume (ADV): GBP 1 mn (USD 1 mn)
NTM P/E: 14x
DOCS sells footwear under its own brand around the world.
It earned GBP 765 mn revenue in FY2026 (-3% YoY):
57% boots (-8% YoY)
26% shoes & loafers (+19%)
11% sandals (-11%)
6% bags and accessories (+1% YoY)
DOCS sells through these channels:
37% wholesale (+3%)
32% direct-to-consumer (DTC) retail stores (-9% YoY)
31% DTC e-commerce (-2%)
Good business, temporary headwinds?
In late 2022, DOCS suffered operational issues at its new Los Angeles warehouse. The company also over-extrapolated demand from COVID-19 reopening. Revenue fell every year since.
However, there are signs that these issues are almost resolved.
Revenue fell -3% YoY in FY2026, an improvement from -10% in FY2025. Full price direct-to-consumer revenue increased +14% and +15% YoY in Americas and APAC (~50% of revenue). Demand is recovering.
DOCS continues to clear excess inventory. Inventory days has now fallen below median levels since 2020.
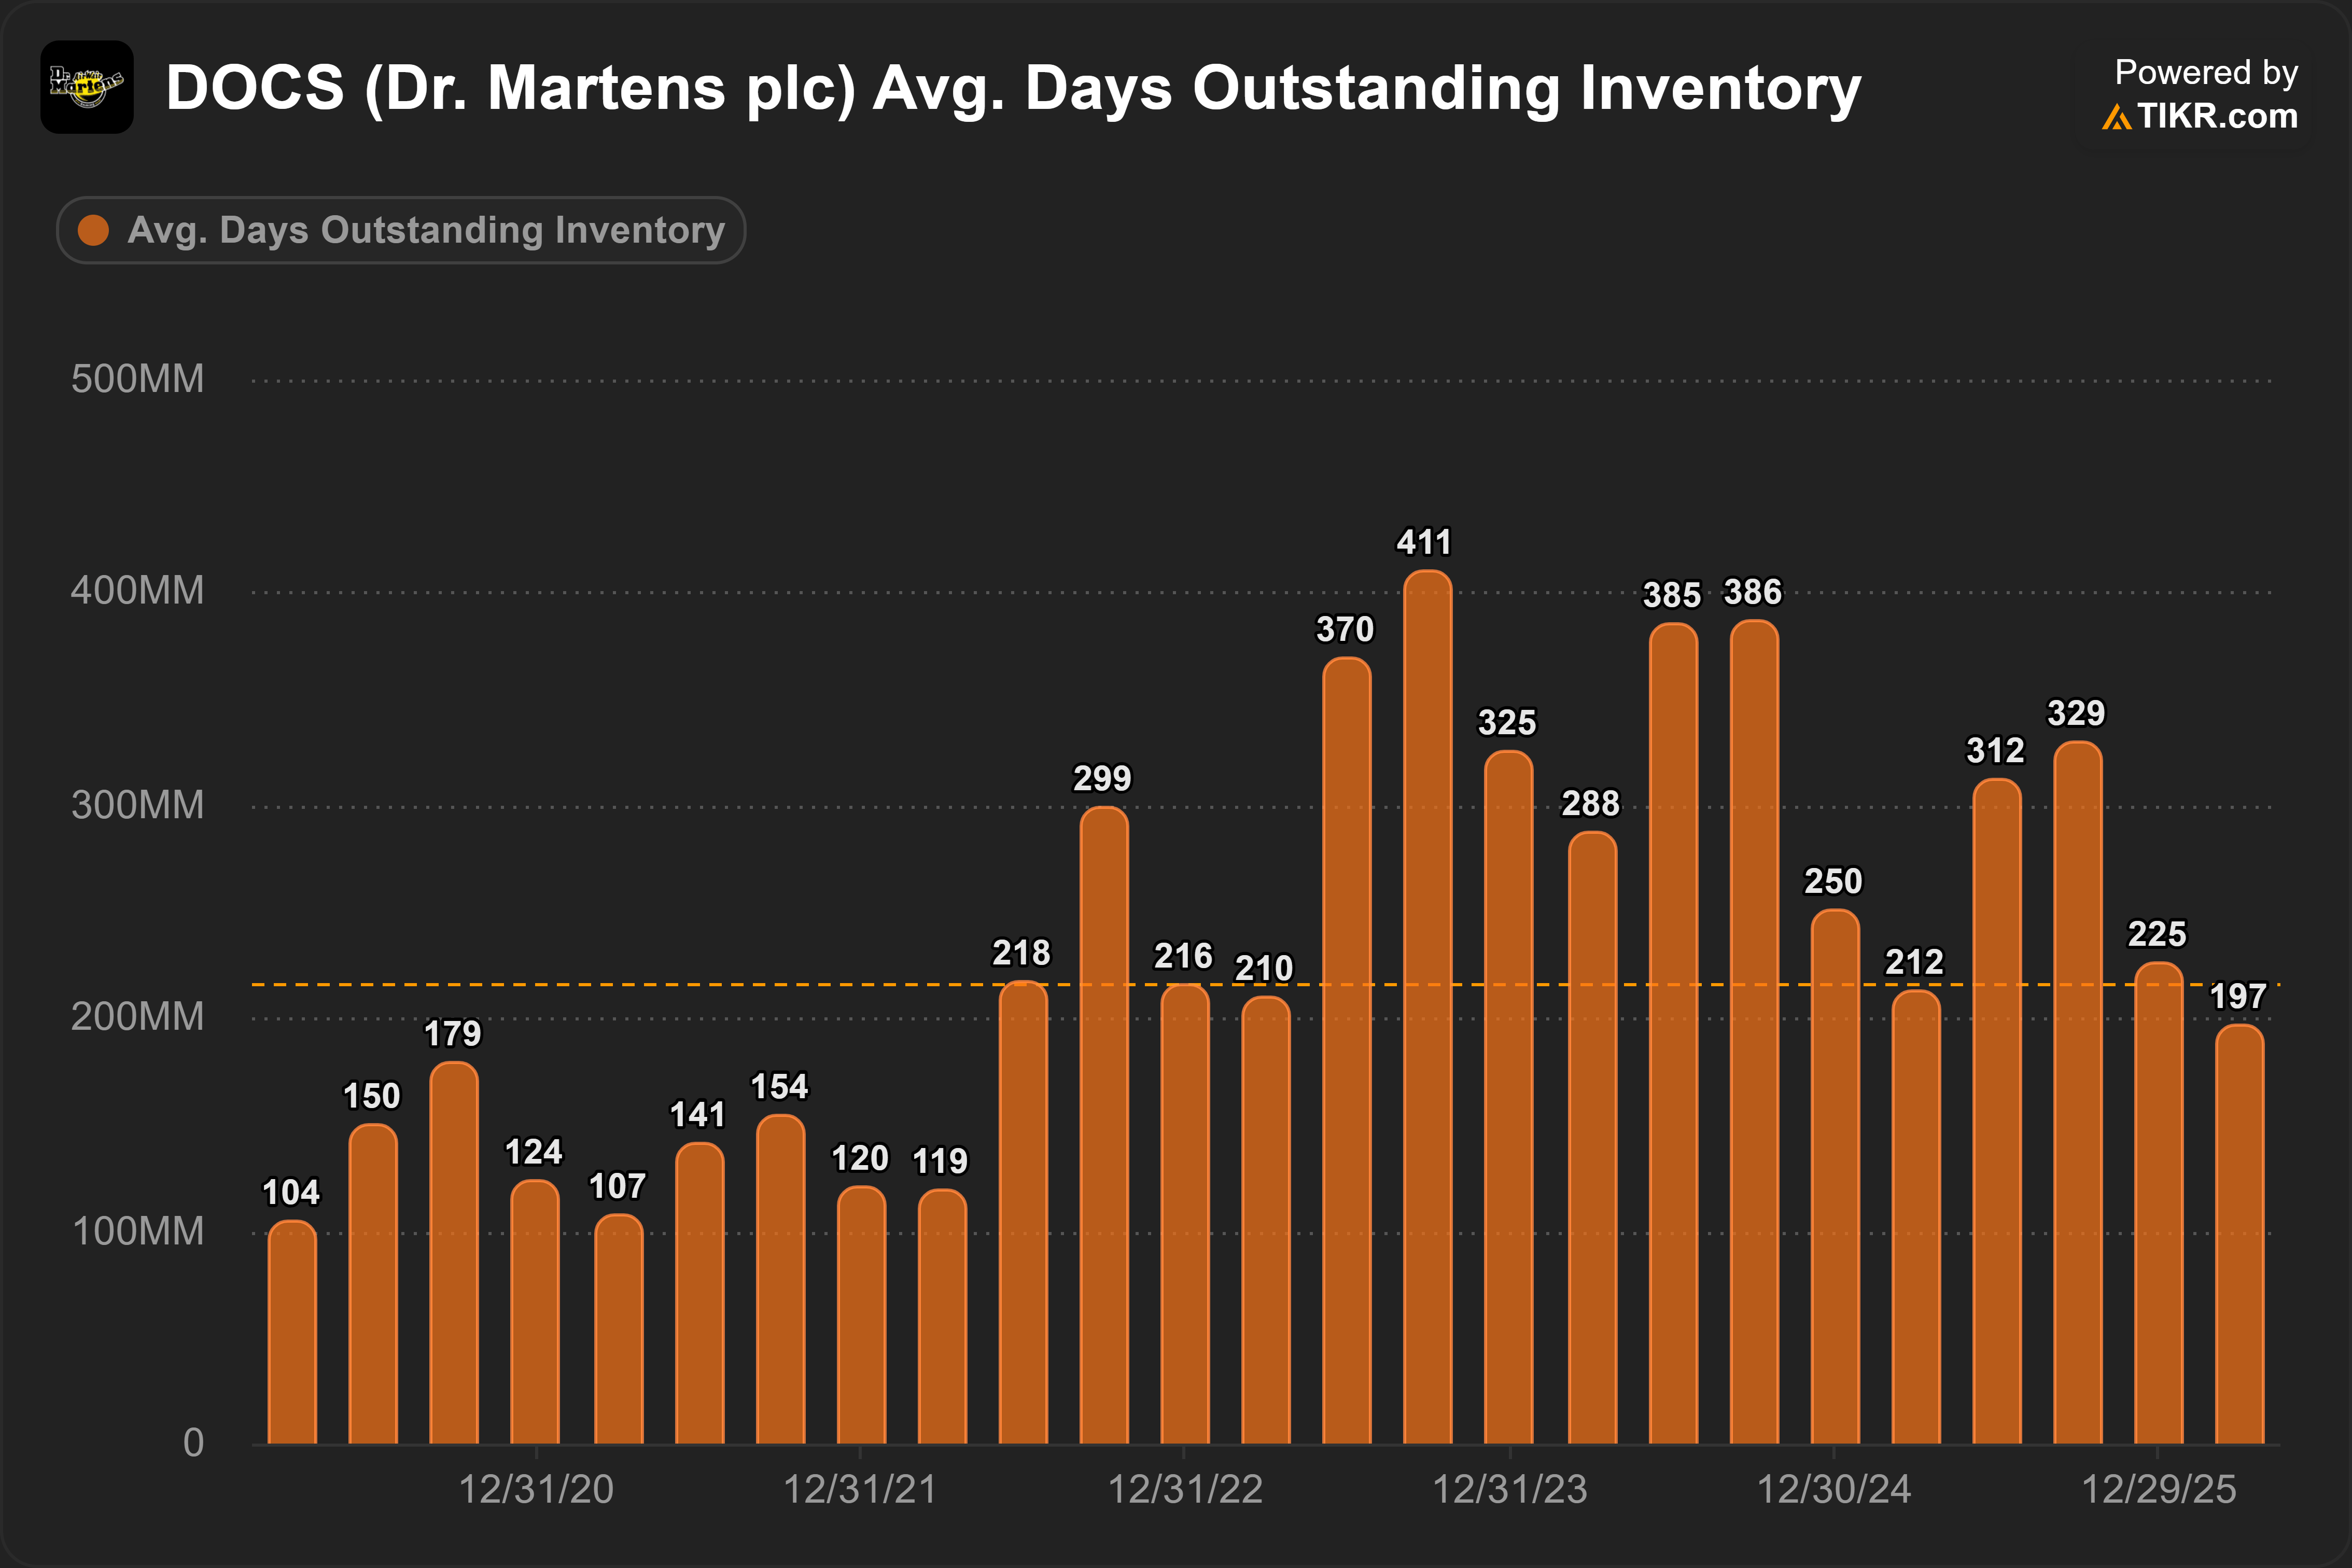
The stronger full-price sales and healthier inventory suggest the headwinds are temporary and nearly over.
Yet, the market seems to ignore this.
I estimate the shares today are trading at ~10% free cash flow yield on enterprise value. ~5% premium over the UK 10y gilt yield.
Potential sale?
Permira, a private equity (PE) firm, is the single largest shareholder. They hold ~38%. At 10 years old, the PE fund (Permira V) is reaching end of life.
Activists funds are pushing for operational improvements and sale.
Marathon Partners took a stake in April 20244 and Sparta Capital in July 20235. Both are sitting on unrealised losses. Huge incentives to engineer a turnaround and eventual sale.
Factors to focus on
Timing and sustainability of recovery.
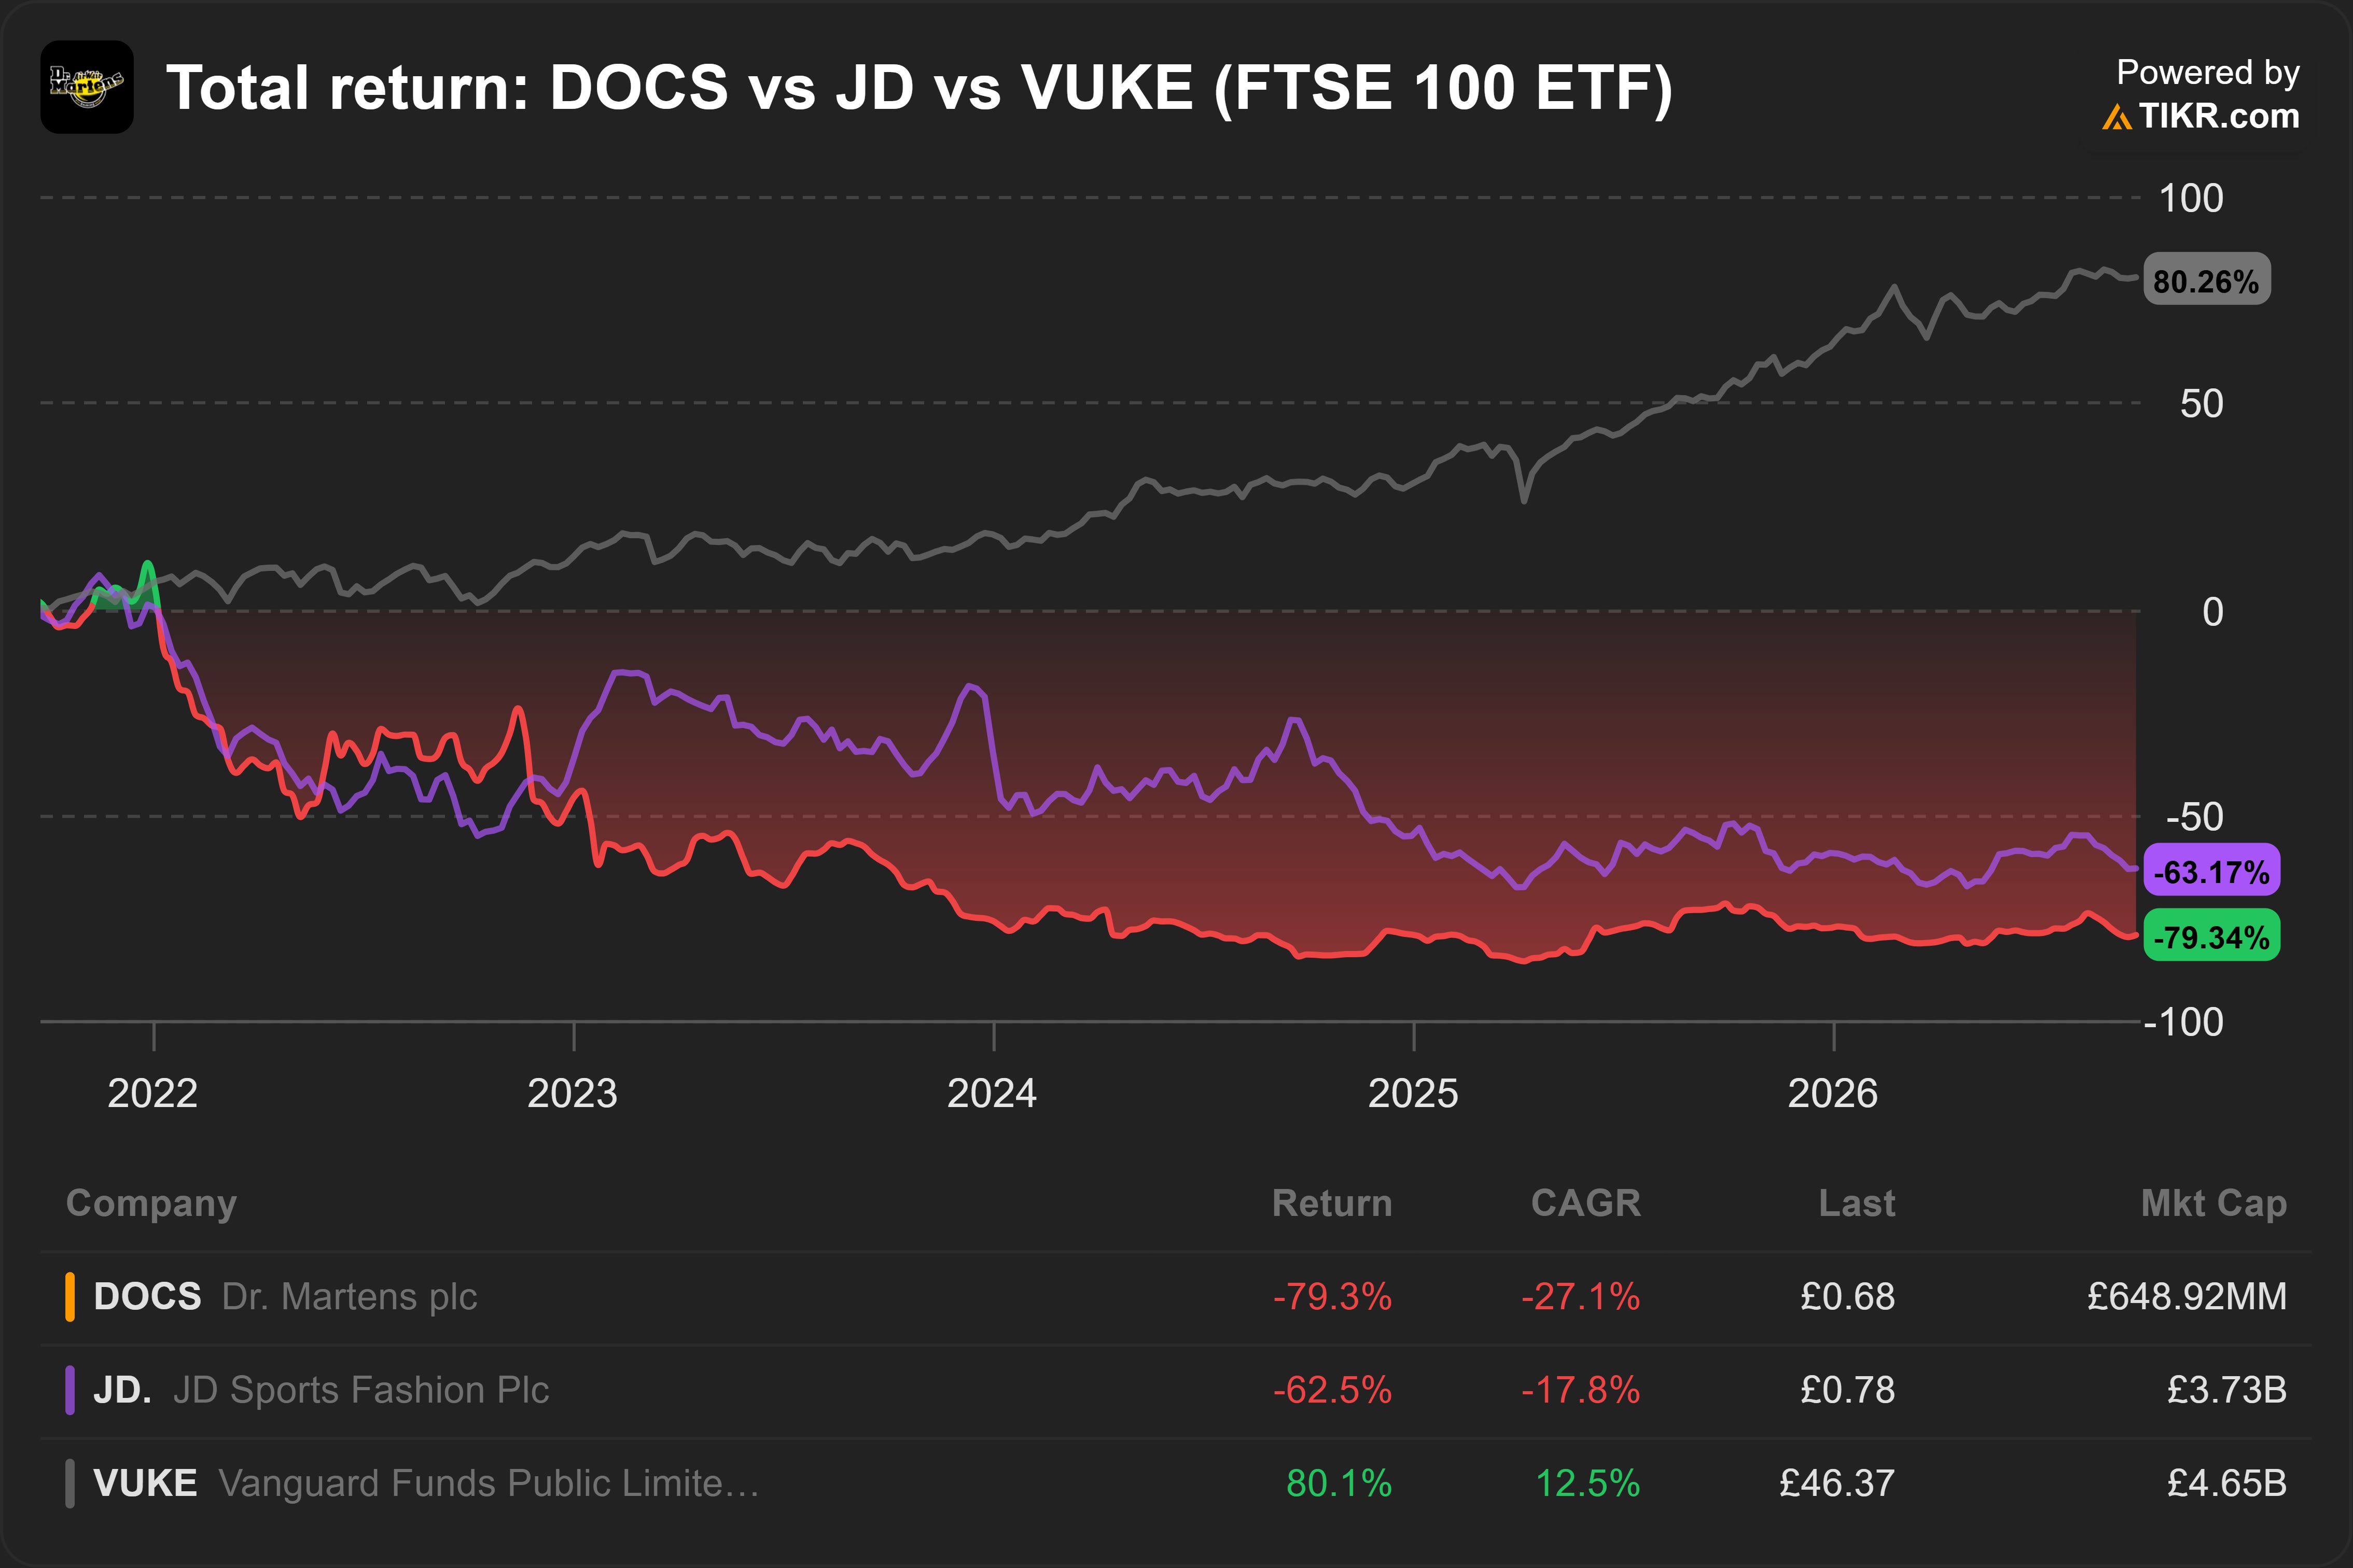
Recovery in DOCS share price reversed in late August after peer JD Sports Fashion Plc (JD LN) reported disappointing results in North America.6 How applicable is the read-through?
US tariffs
Vote for the best idea
If you want me to dig deeper into an idea, vote for it.
Coming up next
I will look deeper into Mortgage Advice Bureau (Holdings) plc (MAB1 LN) this week. This was the idea you voted as the most interesting in my previous email.
Shares in the UK’s largest mortgage network has fallen -50% this year. Is there an opportunity?
Subscribe to get the analysis when I publish.
Subscribe for 2 to 3 analyses of global SMID equities every week.
Discover overlooked ideas and rethink familiar names.
Published by Andrew Wong, ACA, CFA
In case you missed it
Previously, I highlighted the opportunity I see in Siltronic AG (WAF GR).

I also explained why Buffett is wrong.

Disclaimer
This publication is for informational, educational, and entertainment purposes only and does not constitute financial, investment, legal, or tax advice. The content herein is a record of my personal research and investment process, and all analysis, forecasts, and opinions expressed are solely my own.
I make no representation or warranty, express or implied, as to the accuracy, completeness, or timeliness of the information provided. The stock market is highly volatile, and my forecasts, estimates, and assumptions may prove incorrect.
I am not acting as your financial advisor or fiduciary. You should not rely on any information in this publication to make investment decisions. Under no circumstances will I be held liable for any direct, indirect, or consequential losses or damages arising from your reliance on the content of this publication.
At the time of publication, I do not hold any positions in DOCS LN, either long or short. I own shares in 2331 HK. I may change my views, predictions, or personal portfolio positioning at any time without notice.