

Every Monday, I share my first take on 2 to 3 attractive ideas.
As usual, if you want me to dig deeper into an idea, vote for it. Use the poll at the end of this email.
Mortgage Advice Bureau (Holdings) plc (MAB1 LN)
About (11 Sep 2026)
Share price: GBP 3.80
Market capitalisation: GBP 220 mn (USD 298 mn)
Enterprise value (EV): GBP 212 mn (USD 287 mn)
Average daily volume (ADV): GBP 0.9 mn (USD 1.2 mn)
NTM P/E: 8x
MAB1 is one of the largest mortgage networks in the UK. It provides regulatory oversight, software, and lender access to mortgage advisers.
Mortgage procuration fee is the largest revenue stream. It accounts for 42% of revenue in 2025.
Here’s how it works.
A homebuyer approaches a mortgage adviser. The adviser uses MAB1’s software to help the homebuyer assess affordability, the best mortgage lender, etc. They then apply for the mortgage via MAB1’s software.
After the lender disburses the mortgage, it pays a commission to MAB1. MAB1 recognises the entire commission as revenue and the adviser’s cut as its cost of sales.
In 2025, MAB1 grew revenue by +20%. This was driven by +6% growth in number of mortgage advisers and +13% growth in revenue per adviser.
Good business, temporary headwinds?
MAB1 looks interesting now.
The shares dropped -20% after it cut profit guidance on 9 Sep 2026.1 House purchase activity was slower than expected.
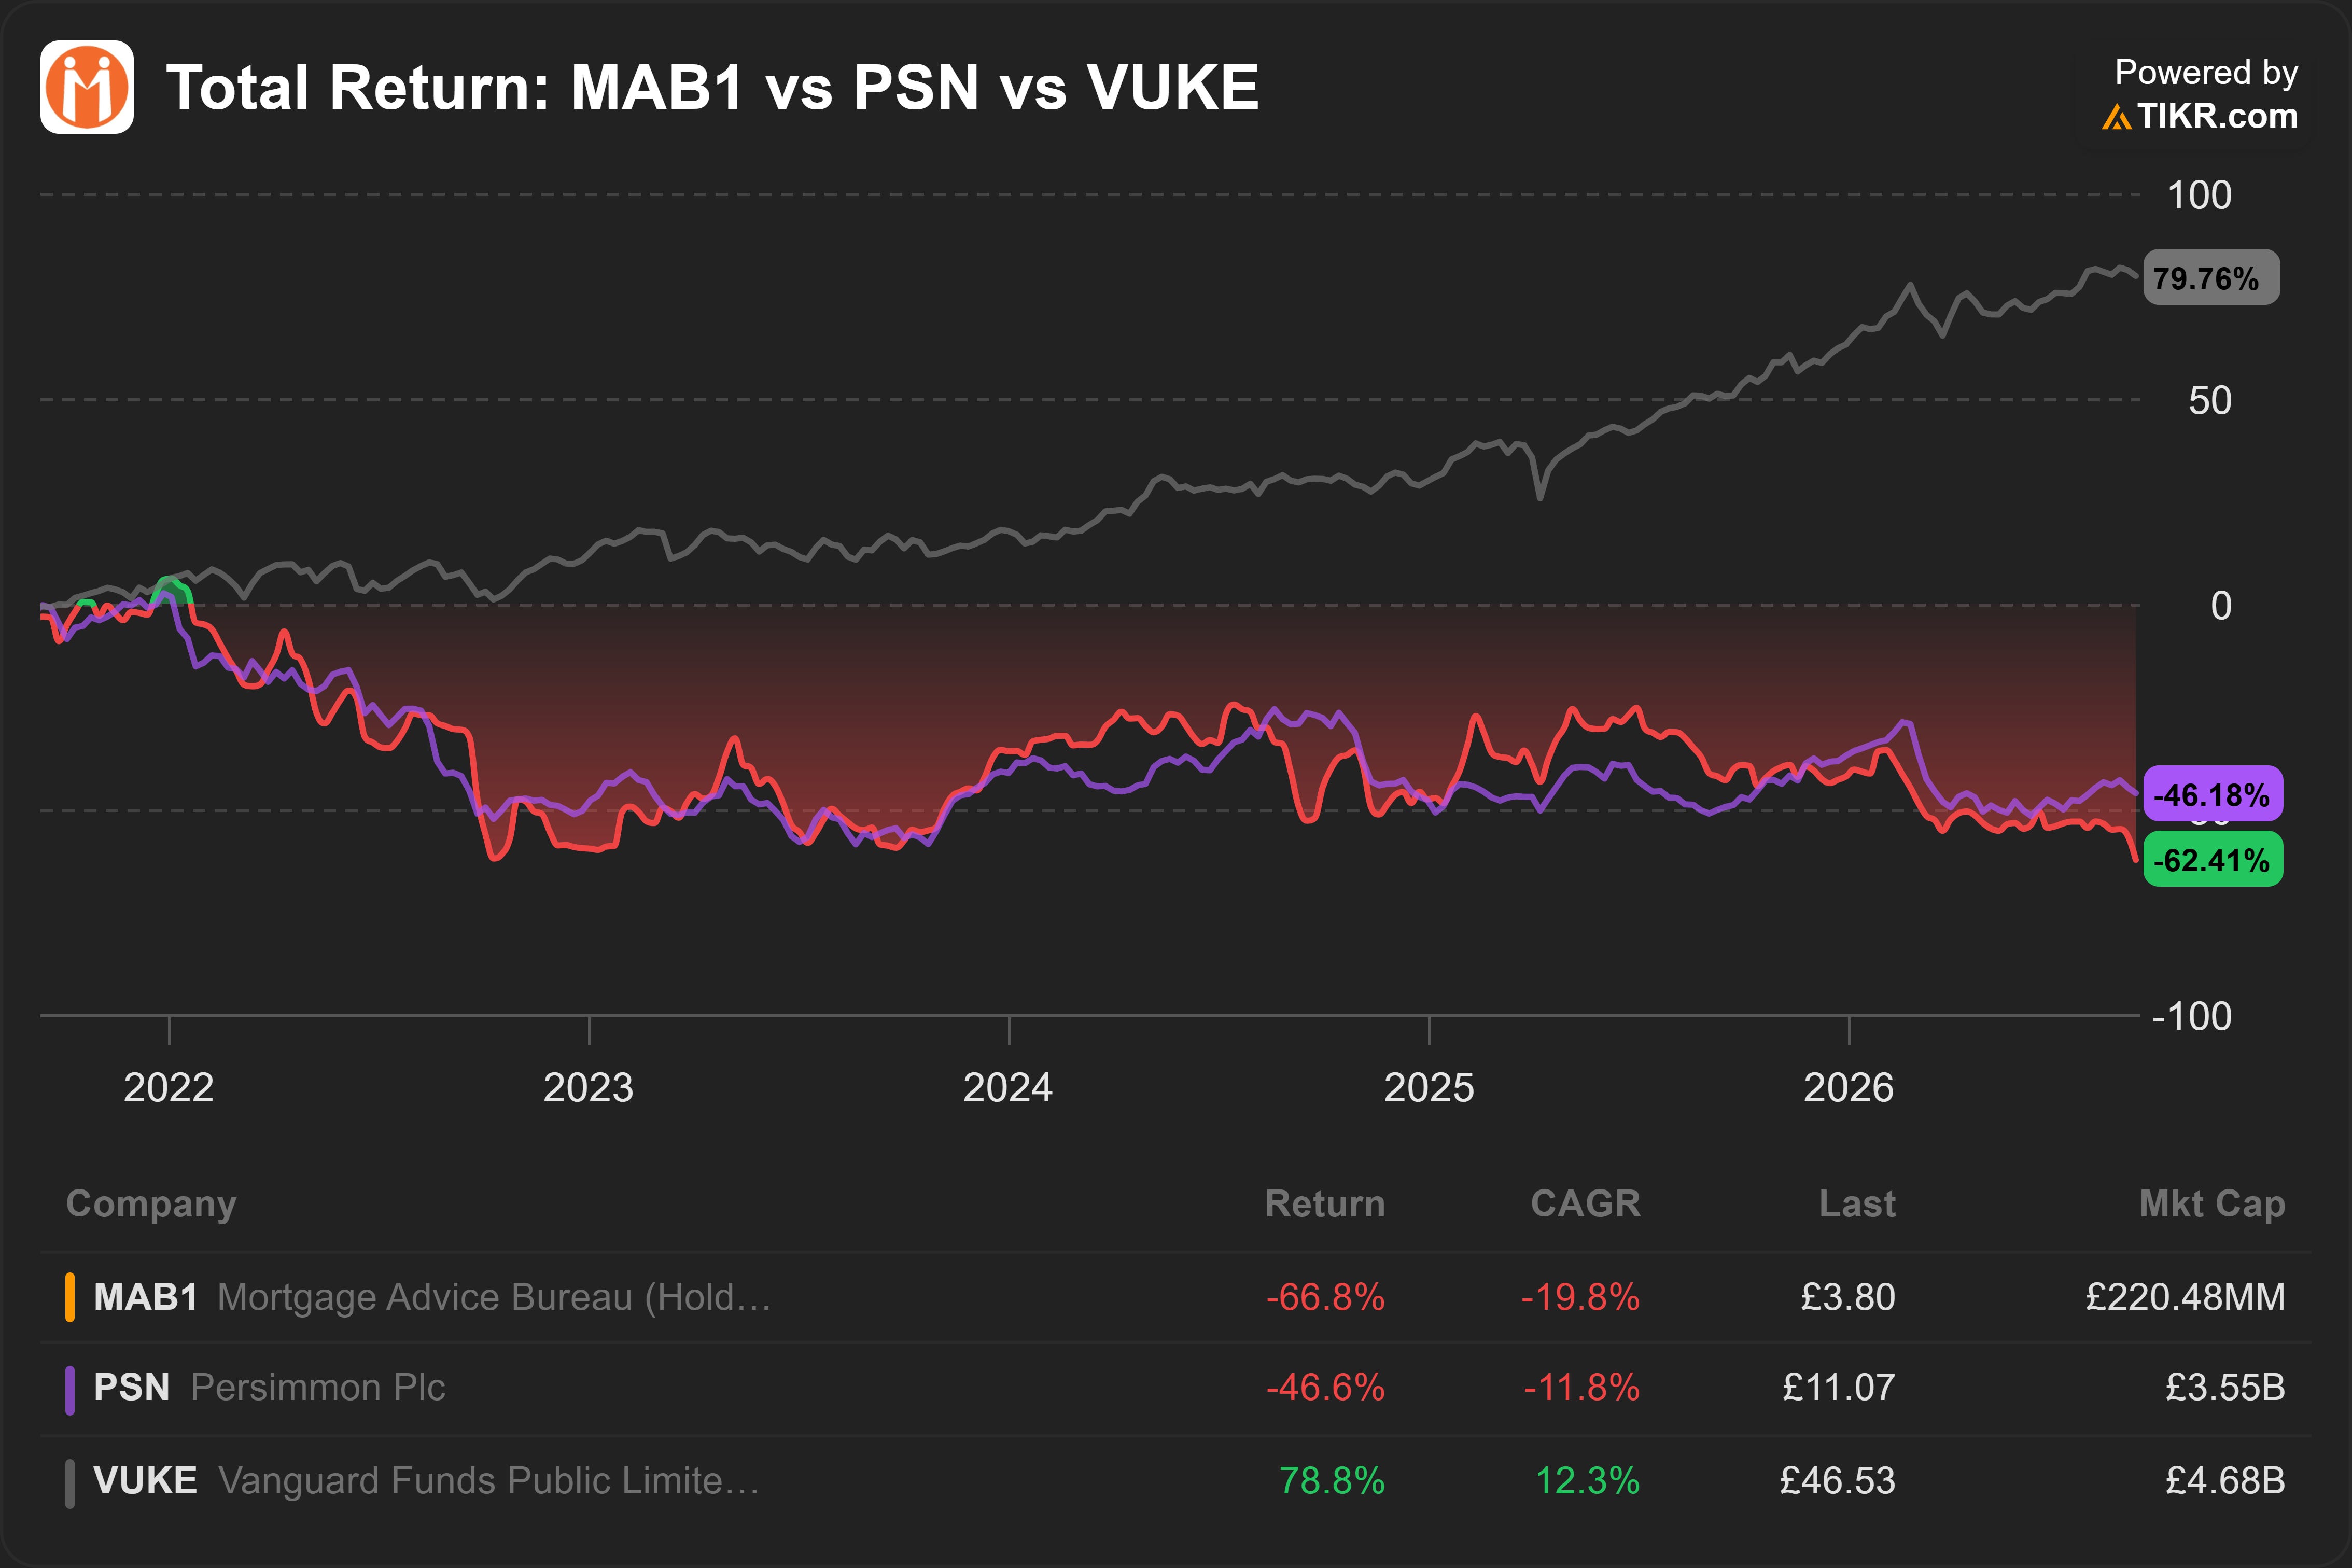
As the chart above shows, investors are treating MAB1 like a homebuilder. The shares trade in line with Persimmon Plc (PSN LN), one of the UK’s largest homebuilders.
MAB1 trades at 8x NTM P/E while PSN trades at 11x.
However, I believe MAB1 should trade at a higher valuation than PSN.
It is a better business. Capital-light. No significant investment in working capital.
MAB1 produces ~10% free cash flow yield on enterprise value (FCF yield). PSN’s FCF yield is negative because of significant inventory.
MAB1 earns 9% return on asset (ROA), superior to PSN’s 5%.
What could close this valuation gap? A sale looks likely.
Potential sale?
CEO and founder Peter Brodnicki is the largest single shareholder, holding ~18% of shares outstanding. Peter is already 64 years old but has no clear successor.
Private equity (PE) firms are targeting capital-light companies in the UK.
Overseas acquirers continue to feast on the UK market like hungry customers at an all-you-can-eat buffet,” said Russ Mould, the investment director at AJ Bell.2
Last week, shares in Eleco PLC (ELCO LN) spiked 70% after the construction software company agreed to a takeover by PE firm Accel-KKR.3
MAB1 fits the profile of a target. Capital-light and high free cash flow conversion. The company is holding net cash, so it has the ability to take on more debt.
Factors to focus on
When will the UK housing cycle recover? Are we already at the bottom?
Why did MAB1 replace its CFO?
Risk looks lower because there is a handover period
Is it appropriate for MAB1 to recognise gross revenue?
Haidilao International Holding Ltd. (6862 HK)
About (13 Sep 2026)
Share price: HKD 9.87
Market capitalisation: HKD 56,074 mn (USD 7,150 mn)
Enterprise value (EV): HKD 53,971 mn (USD 6,882 mn)
Average daily volume (ADV): HKD 207 mn (USD 26 mn)
NTM P/E: 11x
Haidilao operates one of the largest hotpot chains in mainland China.
Good business, temporary headwinds?
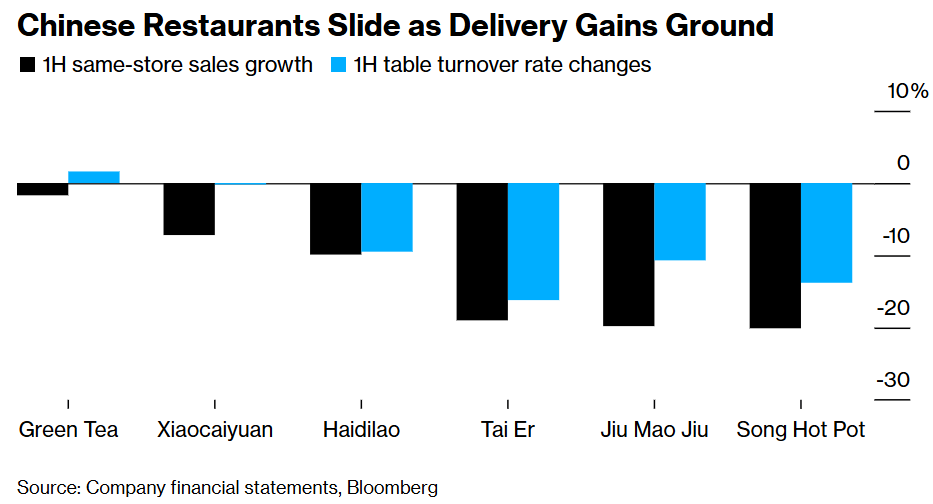
Intense price war between food delivery platforms in 2025 hurt restaurants like Haidilao:
The latest financial results of major listed restaurants, teahouses and cafes analyzed by Bloomberg News show that aggressive online promotion campaigns took a toll on their businesses in the first half of the year, especially in the three months to June when the price war kicked off.4
Source: Bloomberg (2025)
The price war subsided in early 2026 after the regulator launched investigations.5
Haidilao reported early signs of recovery. In H1’26, table turnover rate improved slightly (3.8x to 3.9x) and average spending per guest declined only slightly (RMB 97.9 to RMB 97.0).6
Yet, Haidilao’s share price just hit an all-time low.
The shares slumped last week after the founding family announced a surprise sale of 4.6% of shares outstanding at ~6% discount.
Although they did not disclose the exact reasons, the sale has been linked to tax reasons. The family held their shares through offshore trusts. In July 2026, China announced it will start taxing offshore trusts within 90 days.7
That’s why I see last week’s sell-off as a technical, temporary issue.
With the easing of the price war, Haidilao’s prospect looks much better. Core business seems to have stabilised. New growth engines (delivery business and new brands) are gaining momentum: revenue more than doubled YoY in H1’26.
Without fundamental deterioration, I will be very surprised if the shares fall significantly from here.
Factors to focus on
Growth potential of delivery business and new brands like sushi and food stall hot pot
Stabilisation of core business
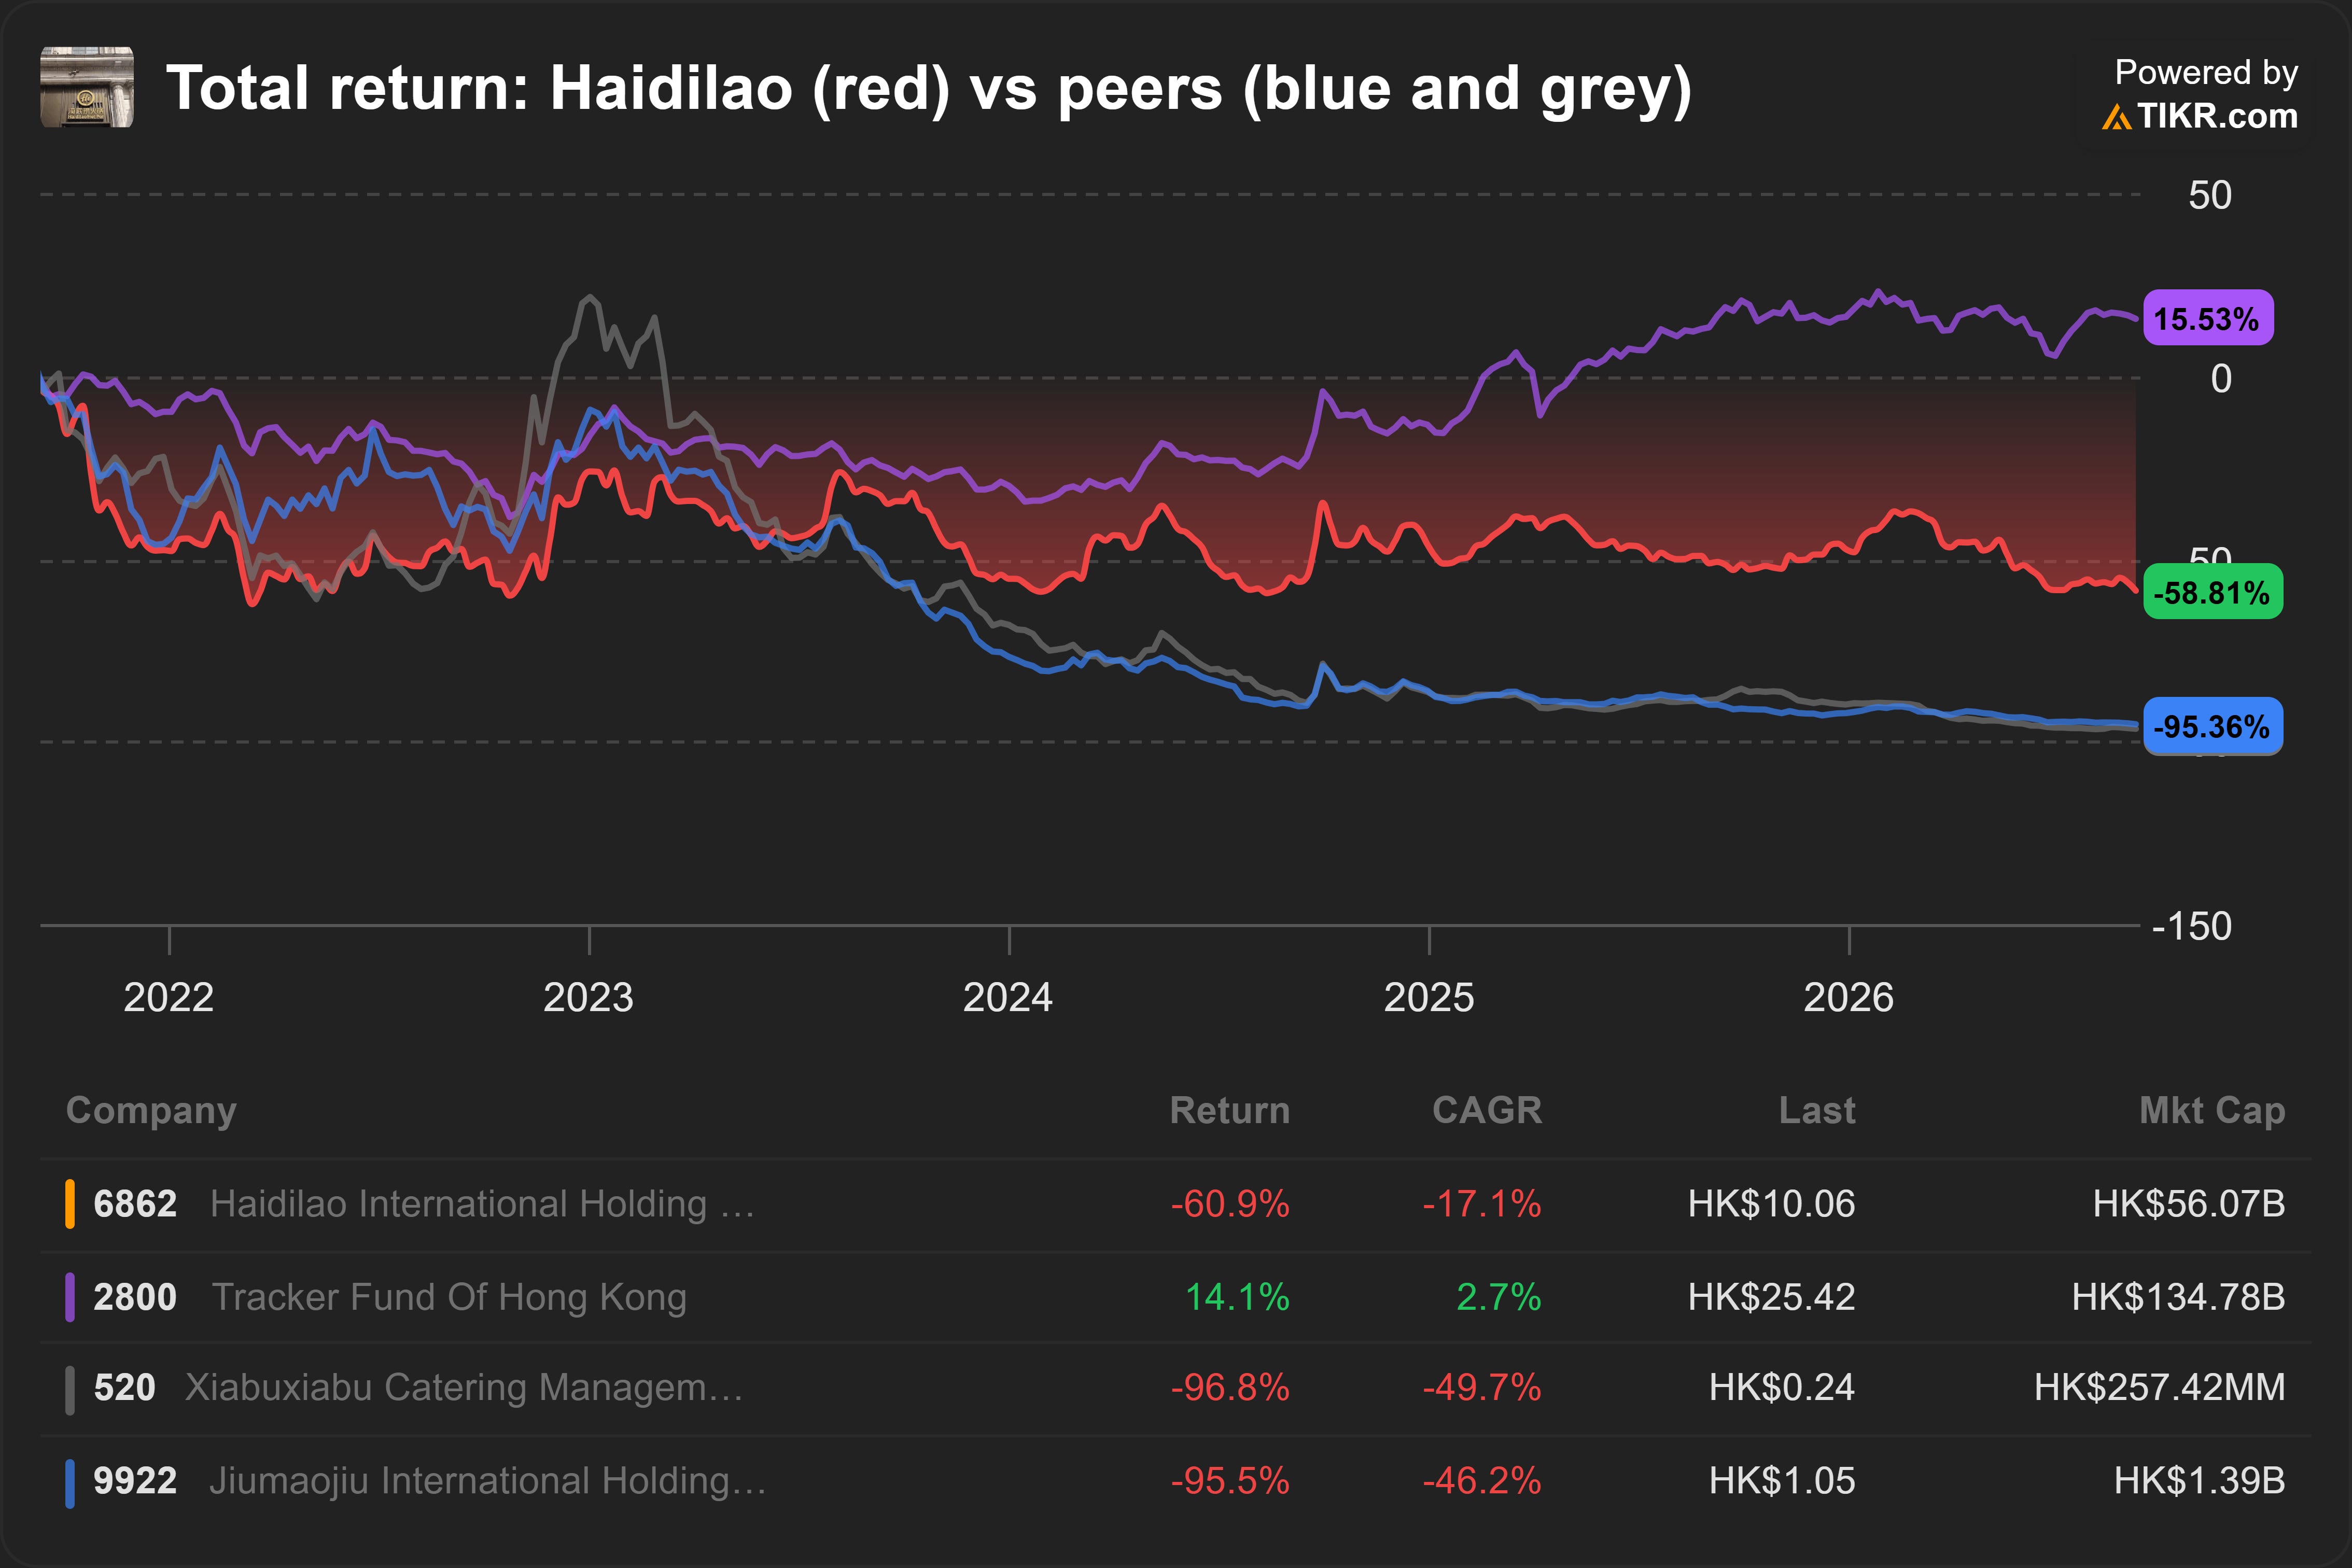
Why did Haidilao perform much better than peers like Jiumaojiu and Xiabu Xiabu?
I suspect economies of scale and vertical integration. Have these been fully priced in?
Vote for the best idea
If you want me to dig deeper into an idea, vote for it.
Coming up next
I will look deeper into Siltronic AG (WAF GR) this week. This was the idea you voted as the most interesting in my previous email.
Is the world’s 4th largest semicon wafer maker reaching an inflection point?
Subscribe to get the analysis when I publish.
Subscribe for 2 to 3 analyses of global SMID equities every week.
Discover overlooked ideas and rethink familiar names.
Published by Andrew Wong, ACA, CFA
In case you missed it
Last week, I highlighted the opportunity I see in Elan Corporation (6099 JP).

I also showed why we should not follow investing rules. They’ll get us into trouble.

Disclaimer
This publication is for informational, educational, and entertainment purposes only and does not constitute financial, investment, legal, or tax advice. The content herein is a record of my personal research and investment process, and all analysis, forecasts, and opinions expressed are solely my own.
I make no representation or warranty, express or implied, as to the accuracy, completeness, or timeliness of the information provided. The stock market is highly volatile, and my forecasts, estimates, and assumptions may prove incorrect.
I am not acting as your financial advisor or fiduciary. You should not rely on any information in this publication to make investment decisions. Under no circumstances will I be held liable for any direct, indirect, or consequential losses or damages arising from your reliance on the content of this publication.
At the time of publication, I do not hold any positions in MAB1 LN or 6862 HK, either long or short. I may change my views, predictions, or personal portfolio positioning at any time without notice.