

Every Monday, I share my first take on 2 to 3 attractive ideas.
As usual, if you want me to dig deeper into an idea, vote for it. Use the poll at the end of this email.
Genting Singapore Limited (G13; GENS SP)
Investors seem to be expecting revenue to continue declining through 2026 and beyond.
However, they are overlooking the inflection points in several key indicators. The percentage of receivables not past due has recovered to its historical average. Contract liabilities, another leading indicator, has already inflected.
Revenue growth, therefore, has likely already bottomed out.
In 2022, international peers like MGM Resorts indicated interest in buying GENS. The major shareholder declined.
Today, high financial leverage at the major shareholder may cause a rethink.
About (2 Oct 2026)
Share price: SGD 0.62
Market capitalisation: SGD 7,419 mn (USD 5,799 mn)
Enterprise value (EV): SGD 4,472 mn (USD 3,495 mn)
Average daily volume (ADV): SGD 18 mn (USD 14 mn)
NTM P/E: 17x
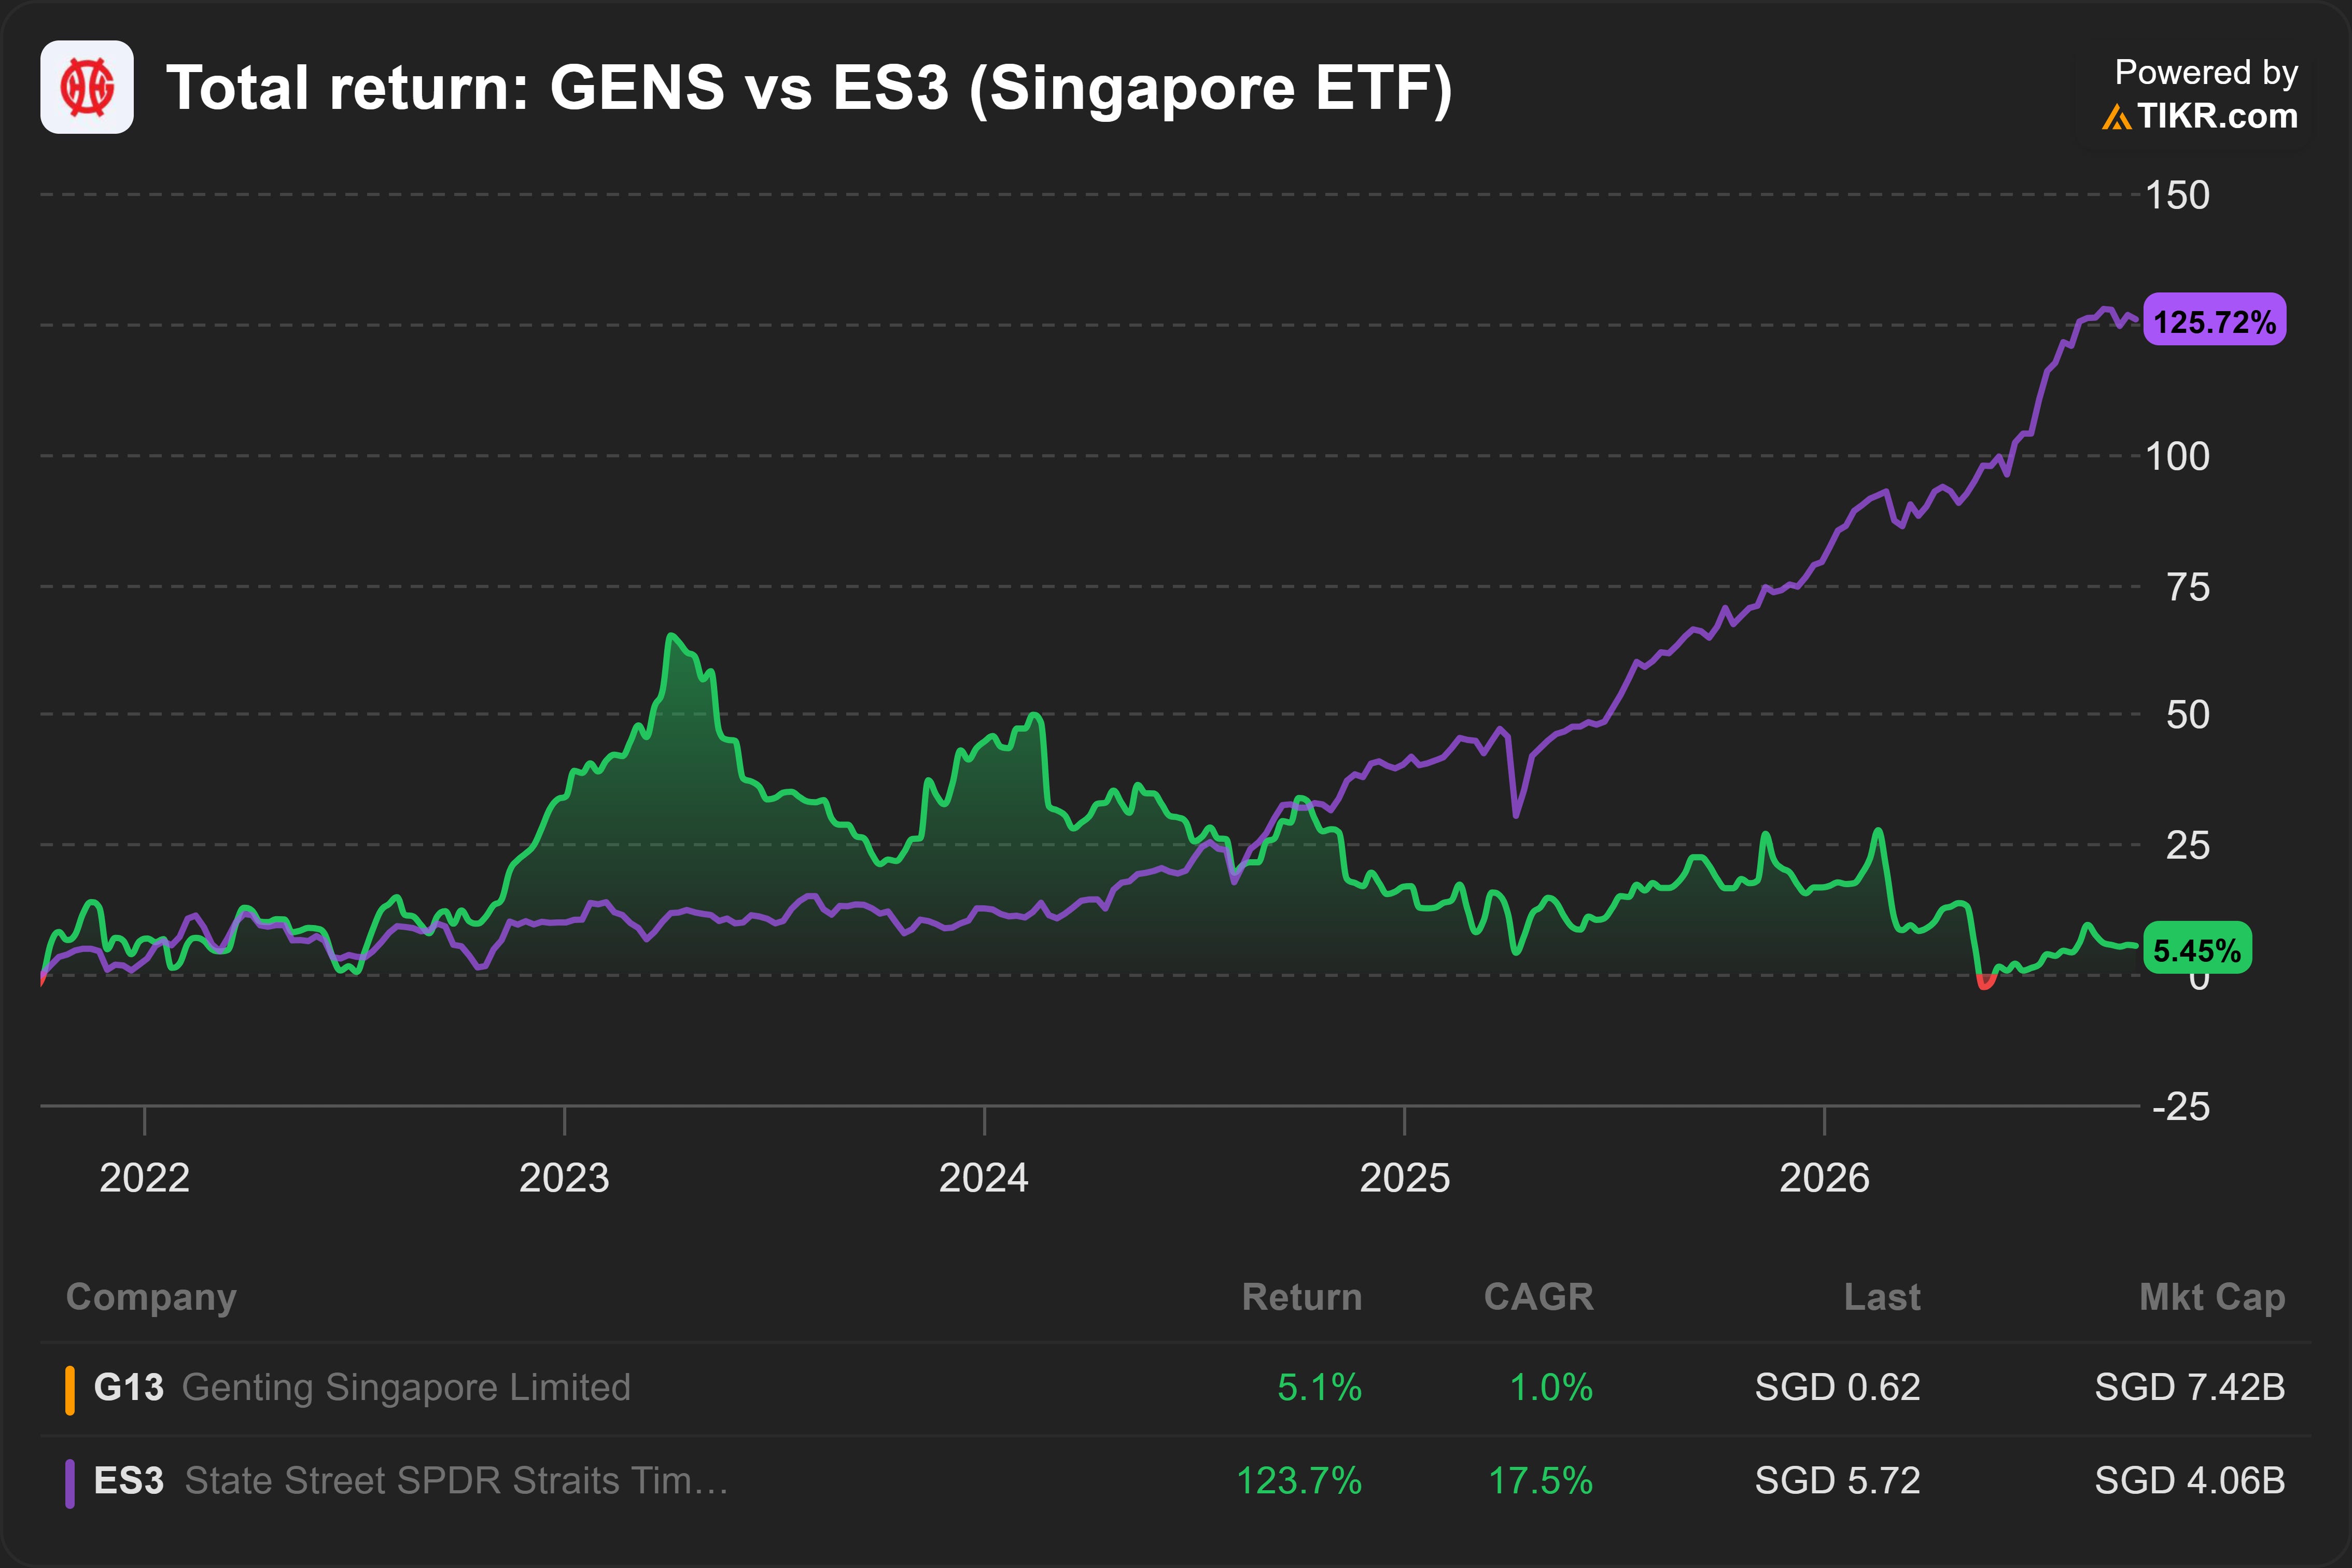
The share price rallied in 2023 on optimism over post-COVID re-opening.
Since then, the shares drifted down. Operating profits fell -9% YoY in 2024, -24% YoY in 2025 and -32% YoY in H1’26.
Two factors: (a) declining revenue and (b) high capital expenditure through 2030.
GENS operates Resorts World Sentosa in Singapore, one of the only two integrated resorts in Singapore.
It earned SGD 2,452 mn revenue in 2025 (-3% YoY):
65% Gaming (-6% YoY)
9% Hotel rooms (-10%)
19% Attractions (+10%)
6% Other non-gaming (-3%)
Good business, temporary headwinds?
Starting 2024, the shares sold off. Performance in the gaming segment was weaker than expected. Gaming revenue declined -6% YoY in 2025.
The market seems to be extrapolating this weakness into 2026.
However, the trends in receivable aging and contract liabilities suggest gaming revenue may perform better than expected in 2026.
Recovery in % of receivables not past due
VIP customers typically borrow from GENS to gamble. The percentage (%) of receivables not past due indicates gaming demand. If demand is weak, customers take longer to pay.
That’s why % of receivables not past due and YoY % change in gaming revenue are correlated.
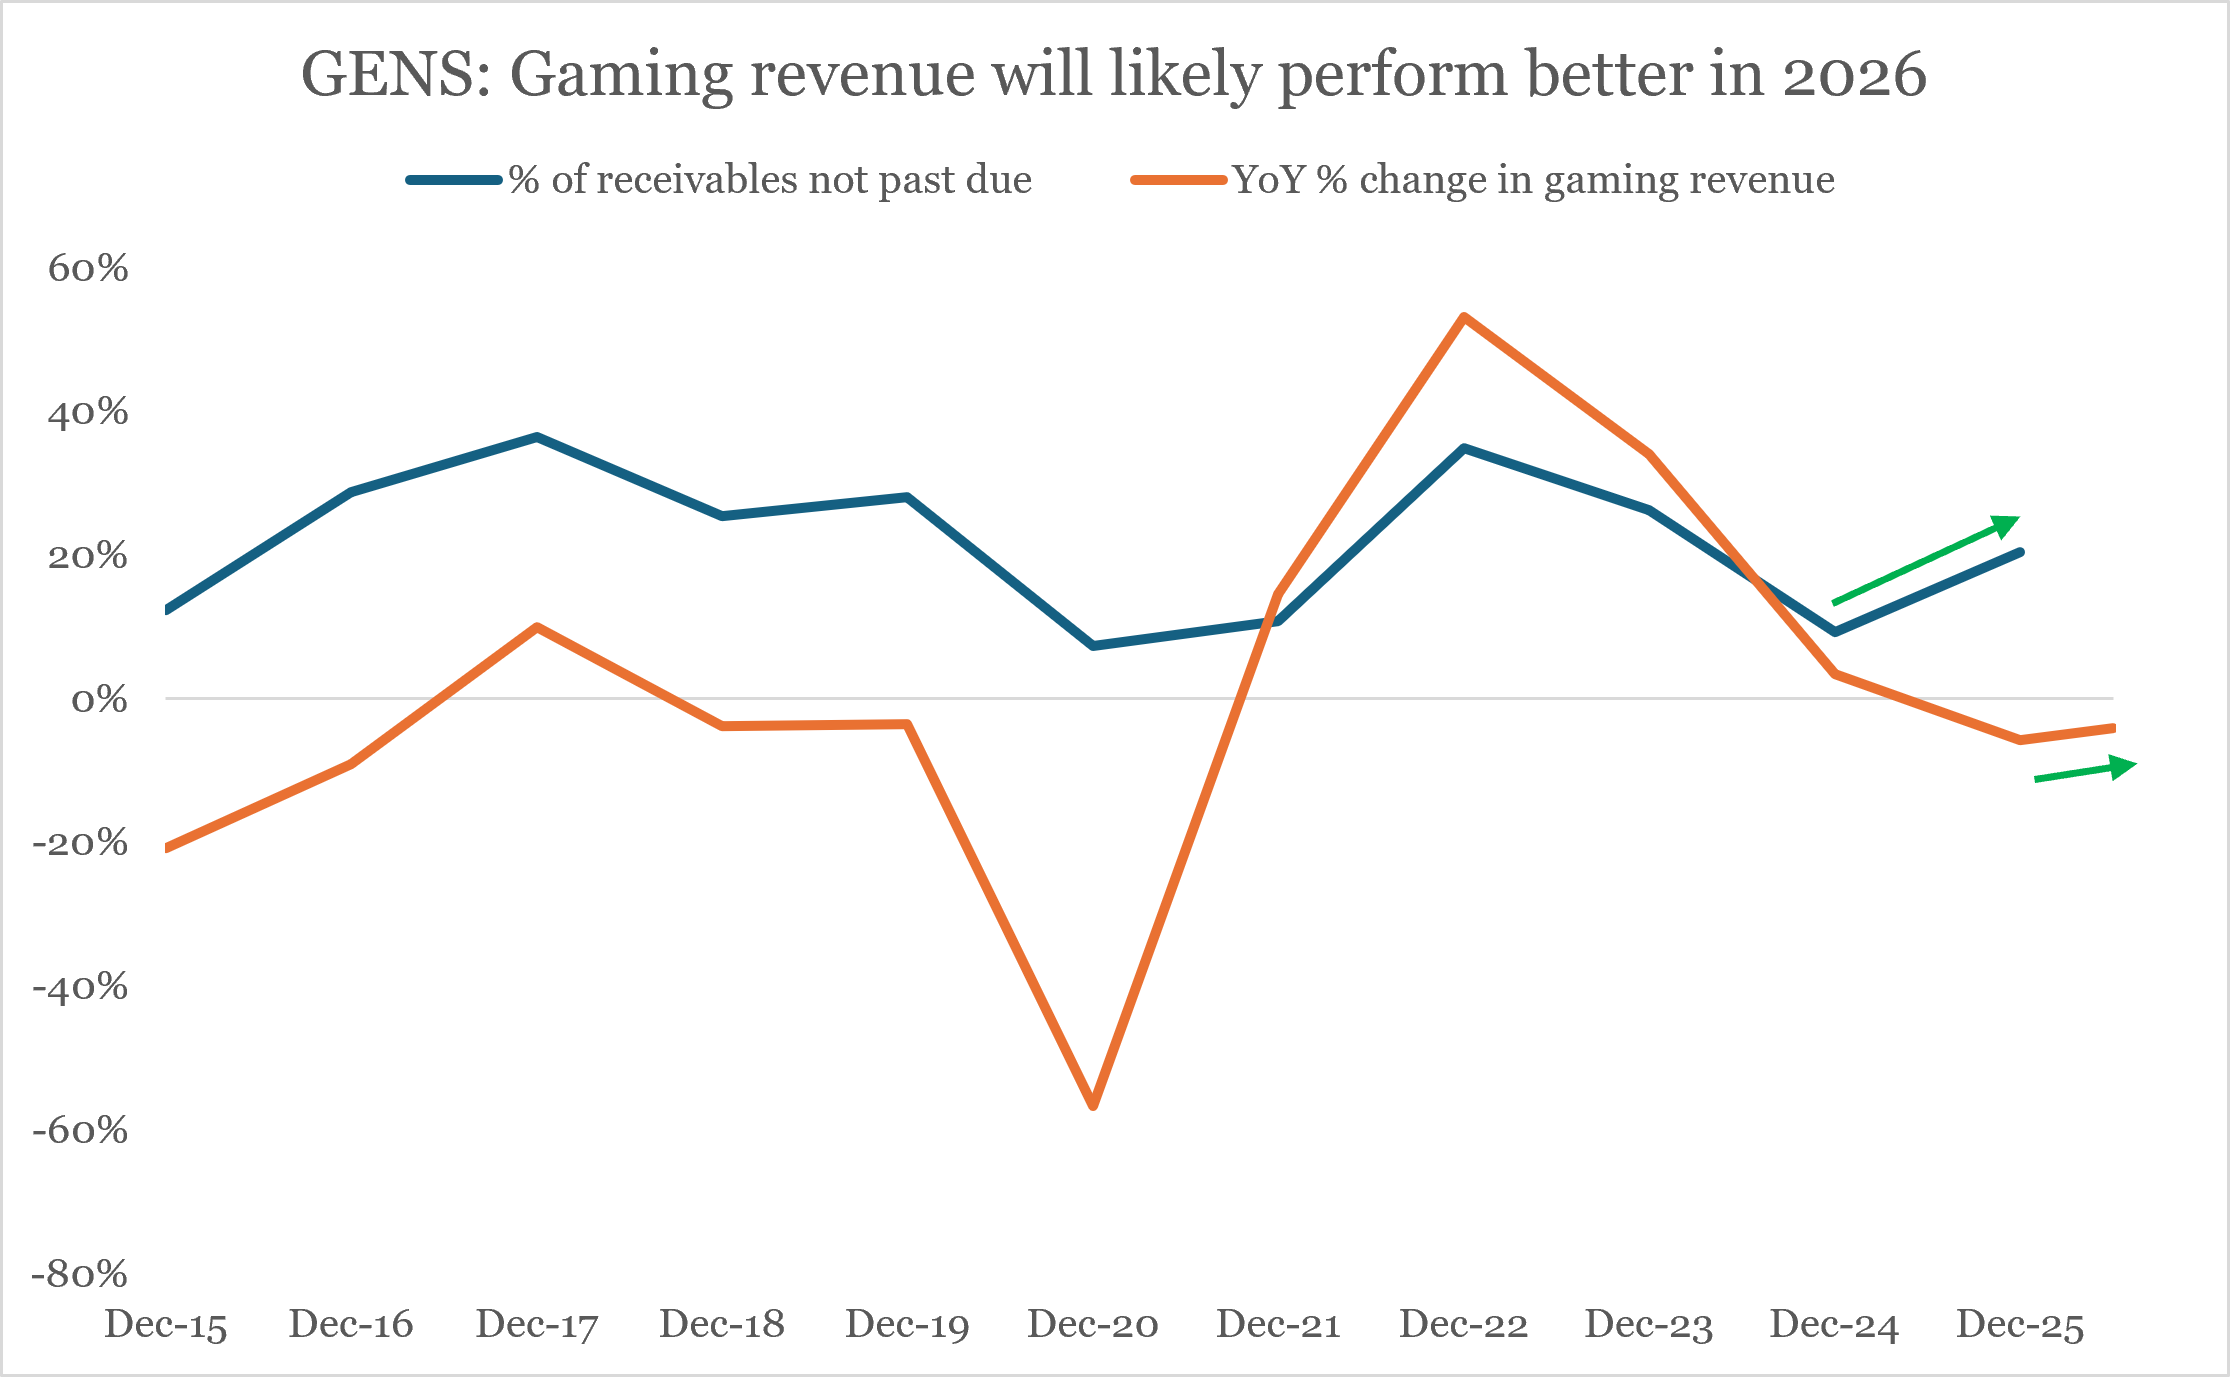
The % of receivables not past due recovered in 2025. YoY % change in gaming revenue also recovered in H1’26, and will likely continue its recovery.
Contract liabilities increased
Contract liabilities represent cash received in advance from customers for future gaming and non-gaming services.
When demand is strong, customers buy more chips or deposit more cash into their gaming accounts. These are recorded as contract liabilities, which are converted into revenue when customers spend them.
That’s why contract liabilities is a leading indicator of revenue (except during the distortion created by COVID-19):
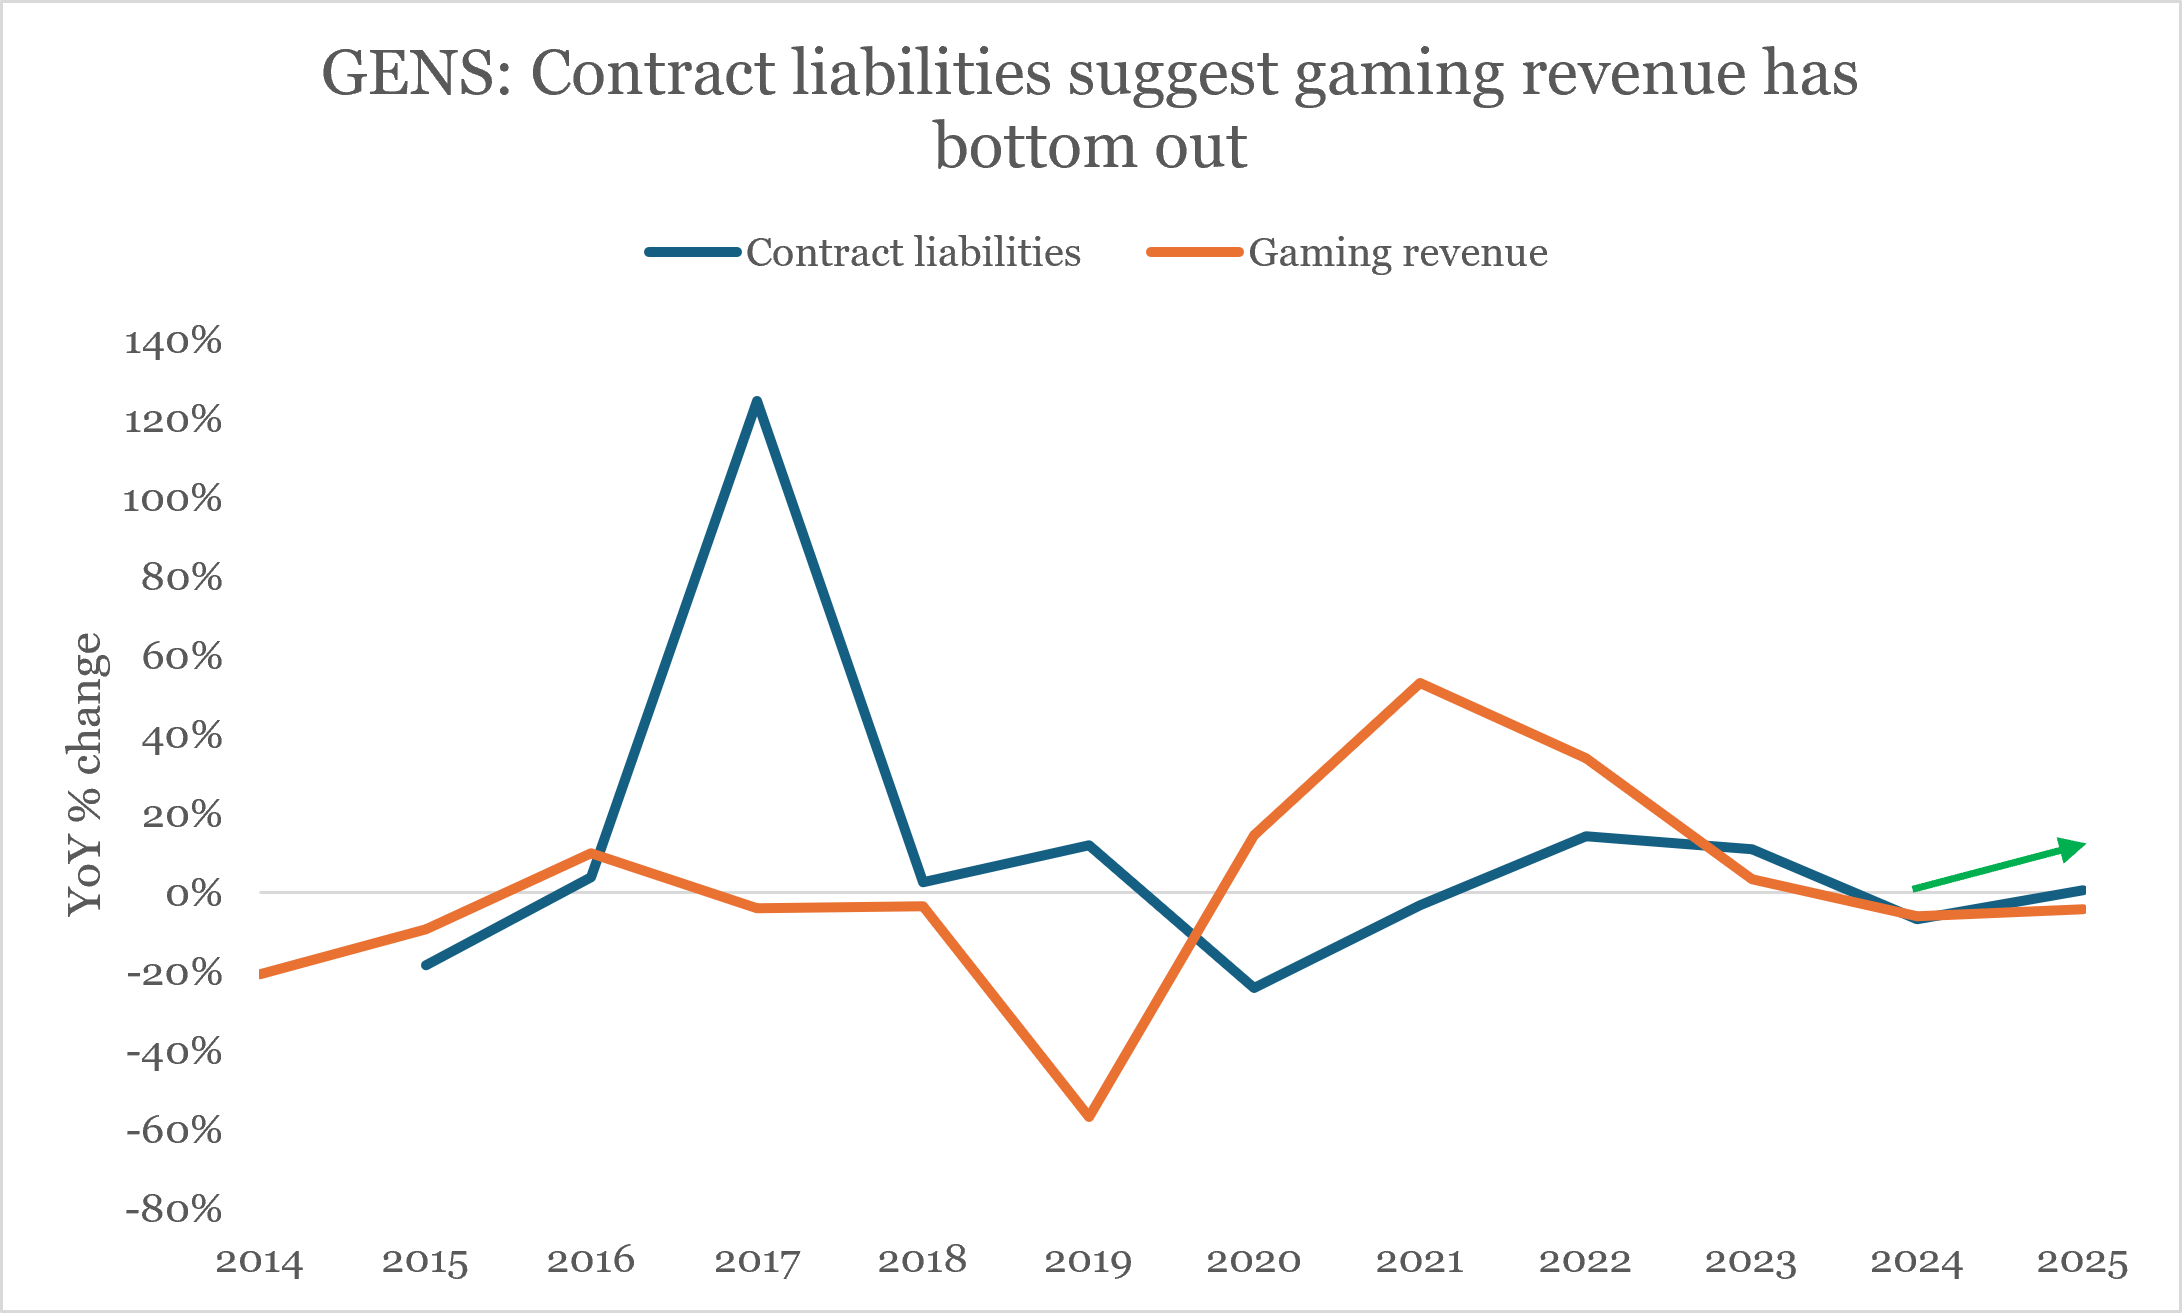
In 2025, contract liabilities grew +1% YoY. This suggests gaming revenue has bottomed out.
Potential sale?
In July 2022, MGM Resorts International (MGM 0.00%↑ US) reportedly approached the GENS’ controlling shareholder, the billionaire Lim family, to express its interest in a deal.
Bloomberg reported: “Other potential suitors have also been in the preliminary stages of studying Genting Singapore”1
No deal materialised. It appeared the Lim family did not want to sell.
Since 2022, what has changed?
Genting Malaysia Berhad (GENM MK), GENS’ sister company, won a license to operate a casino in New York. It is spending a lot of money to build the casino. We talked about this before here.
But Genting Berhad (GENT MK), the parent company of both GENM and GENS, already has a lot of debt. Last month, Fitch downgraded GENT’s credit rating to ‘BBB-’, its lowest investment grade rating.2
A sale of GENS could help deleverage.
Factors to focus on
Remaining committed capex of ~ SGD 4 bn to renovate and upgrade facilities will likely result in negative free cash flow through 2030. GENS has ~ SGD 3 bn cash on hand.
Risk of cost overrun?
Risk of worse-than-expected disruption to operations?
Continued loss of market share to Marina Bay Sands?
ANTA Sports Products Limited (2020 HK)
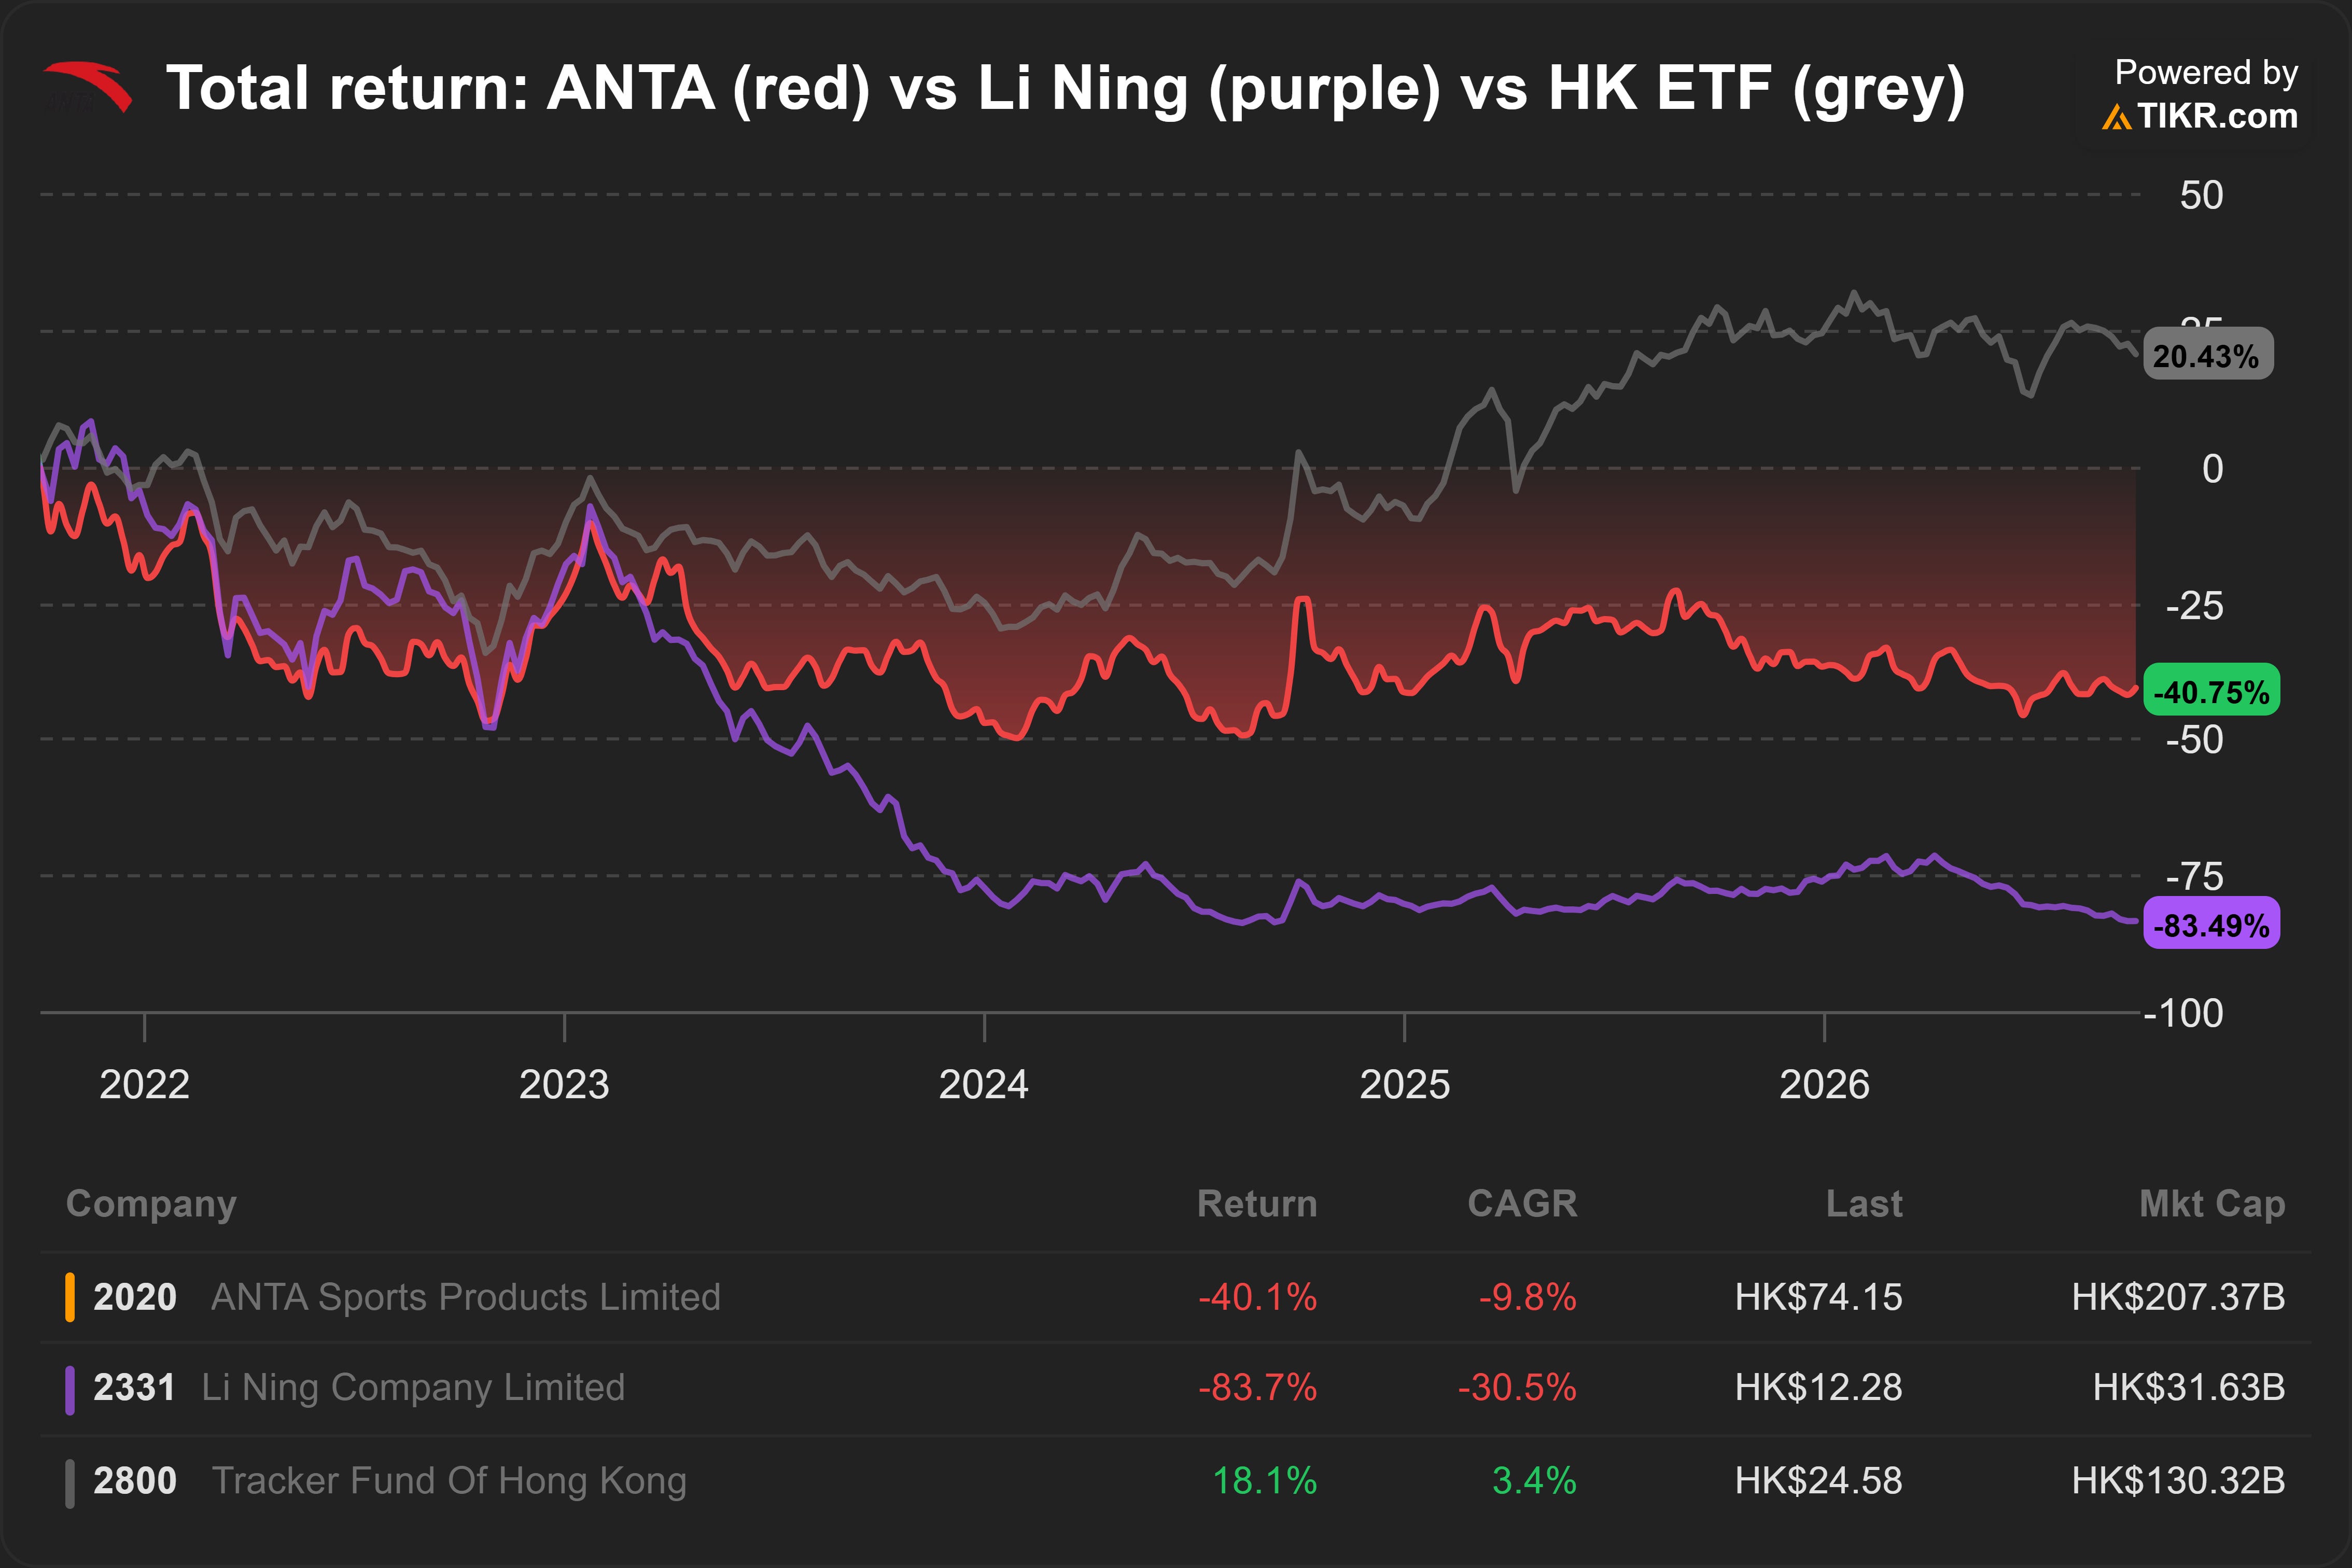
The market seems to be extrapolating Nike’s -26% revenue decline in China onto ANTA.
That is not accurate. Nike’s problem in China is specific to itself.
In fact, ANTA is taking market share. Over the past few quarters, it has grown revenue by mid-teens.
Investors worry over the weak consumer demand in China. But they are overlooking ANTA’s growth opportunities overseas.
About (4 Oct 2026)
Share price: HKD 73.70
Market capitalisation: HKD 207,372 mn (USD 26,425 mn)
Enterprise value (EV): HKD 200,962 mn (USD 25,609 mn)
Average daily volume (ADV): HKD 525 mn (USD 67 mn)
NTM P/E: 12x
ANTA sells sportswear, mainly in China.
It earned CNY 80,219 revenue in 2025 (+13% YoY):
43% ANTA (+4% YoY)
35% FILA (+7%YoY)
21% Others (+59% YoY)
ANTA focuses on mass-market sportswear. FILA is premium. Other brands focus on specialised and high-performance sportswear like Descente (high-end skiing and golf) and Kolon (trekking and hiking).
Good business, temporary headwinds?
The market sees sportswear as a declining market in China.
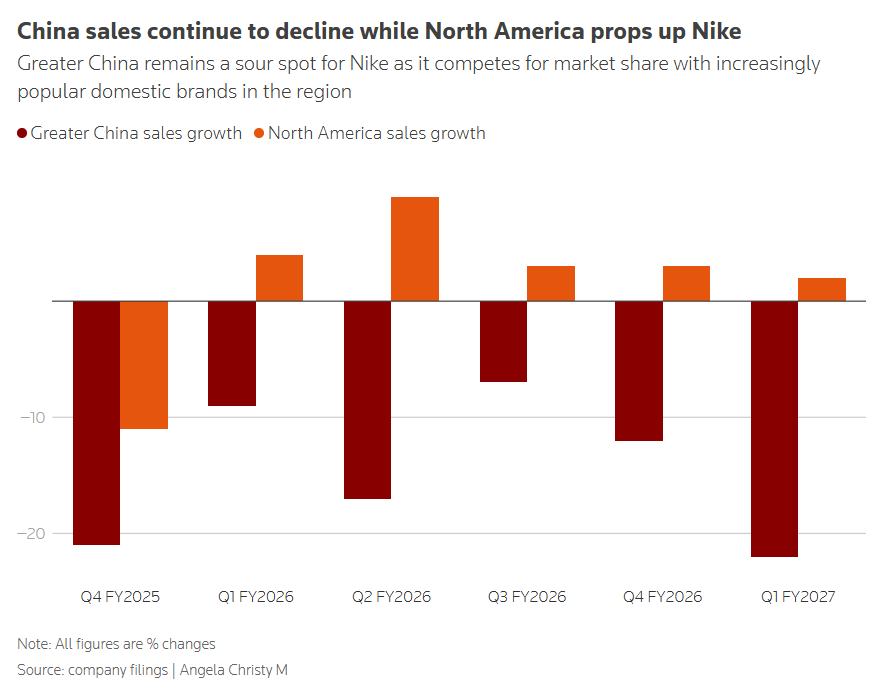
The poster child for this is Nike (NKE 0.00%↑ US). In Q1’FY27 (June to August 2026), NKE’s sales decline in China reached -26% YoY:
Source: Reuters (2026)
However, NKE is not an accurate representation of the sportswear market in China. Its problems are specific to itself.
Even though consumer demand is weak in China, ANTA still grew its revenue by low-teens over the past few quarters.
Furthermore, ANTA is showing early signs of reaching an inflection point. Inventory days is starting to recover.
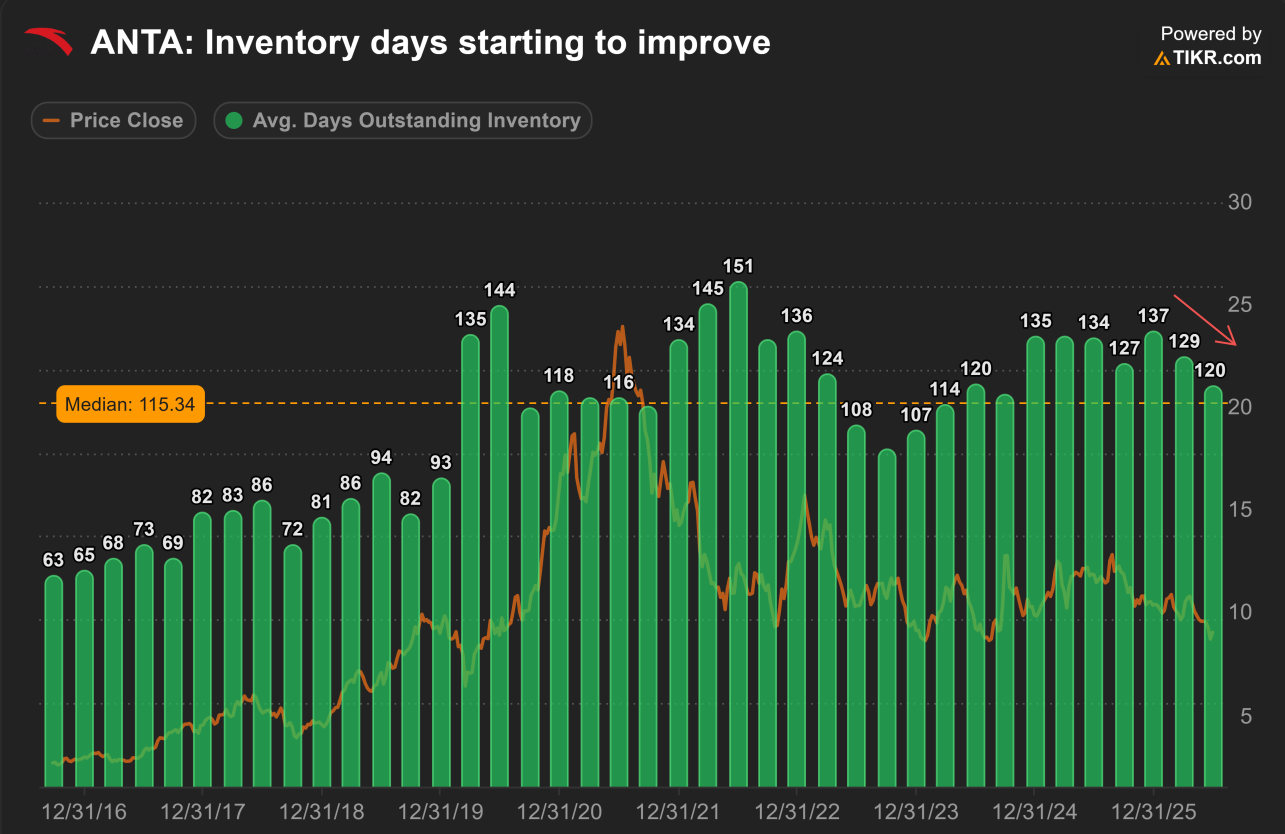
Note: Inventory days before 2020 is not comparable because ANTA shifted from wholesale to direct-to-consumer during that year.
Under-recognised growth?
ANTA also sees opportunities outside China.
In June 2025, it had 224 stores overseas, mostly in Southeast Asia. By June 2026, ANTA had doubled overseas store count to more than 500.3 It targets 1,000 overseas stores by 2028.4
Can they do it?
Probably yes. Their product quality seems to be on par with Western brands, and more-value-for-money.
In 2025, CNA reported:5
Other runners, like competitive marathoner Giebert Foo, also admitted to an initial perception of Chinese shoes as being of lower quality and durability.
…with his friends insisting they were comparable to Nike and Adidas offerings, he was compelled to give it a go.
He said that around 90 per cent of his friends own Chinese super shoes now, up from half of them back in 2022.
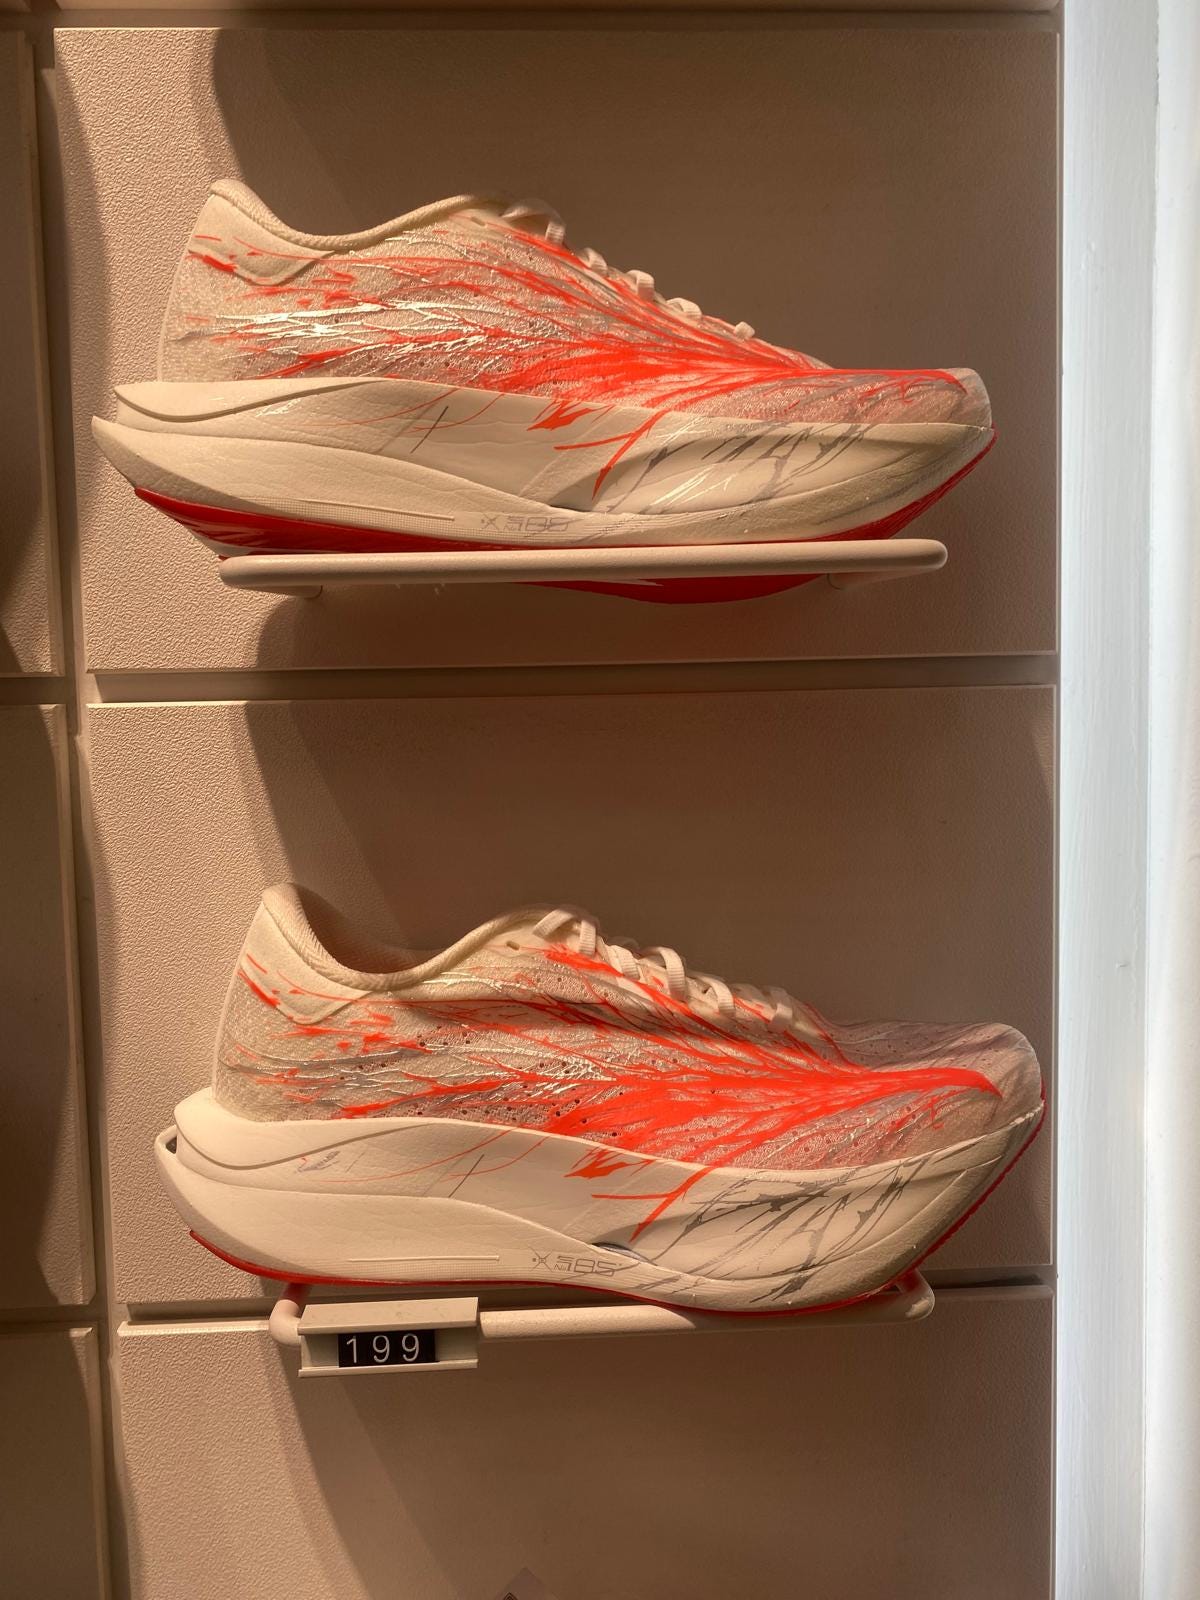
I tried some ANTA shoes in Singapore.
The most expensive model in the store retails for SGD 199.
Source: Angsana Anderson (2026)
Designed for half-marathons and marathon, it gives a strong ‘bounce’ on every step.
I tried it. The quality is good. A comparable pair at a Western brand would probably cost twice as much, I reckon.
BYD brought affordable EVs to the world. Chagee made drinking tea fashionable again.
ANTA (and Li Ning) are bringing Chinese sportswear to the world. Unlike EVs and tea, competition in sportswear doesn’t seem that cut-throat.
Factors to focus on
Timing and sustainability of recovery
Opportunities in international markets
Vote for the best idea
If you want me to dig deeper into an idea, vote for it.
Coming up next
I will look deeper into Li Ning Company Limited (2331 HK) this week. This was the idea you voted as the most interesting in my previous email.
The market seems to be pricing in another long and severe downturn, like the one from 2011 to 2017. At that time, Li Ning overestimated demand and had to cut prices aggressively to clear excess inventory.
However, the current downturn will likely be less severe than expected. Inventory footnotes reveal a good business that’s much healthier than expected.
Furthermore, investors are overlooking the inflection point in Li Ning’s growth in international markets.
Subscribe to get the analysis when I publish.
Subscribe for 2 to 3 analyses of global SMID equities every week.
Discover overlooked ideas and rethink familiar names.
Published by Andrew Wong, ACA, CFA
In case you missed it
Previously, I highlighted the opportunity I see in Mortgage Advice Bureau (Holdings) plc (MAB1 LN).

I first started investing in 2021. Despite outperformance, looking back, I realised how naive I was.
If I could send a post back in time to 2021, what would I tell myself?

Disclaimer
This publication is for informational, educational, and entertainment purposes only and does not constitute financial, investment, legal, or tax advice. The content herein is a record of my personal research and investment process, and all analysis, forecasts, and opinions expressed are solely my own.
I make no representation or warranty, express or implied, as to the accuracy, completeness, or timeliness of the information provided. The stock market is highly volatile, and my forecasts, estimates, and assumptions may prove incorrect.
I am not acting as your financial advisor or fiduciary. You should not rely on any information in this publication to make investment decisions. Under no circumstances will I be held liable for any direct, indirect, or consequential losses or damages arising from your reliance on the content of this publication.
At the time of publication, I do not hold any positions in GENS SP or 2020 HK, either long or short. I may change my views, predictions, or personal portfolio positioning at any time without notice.
References
Bloomberg