

Every Monday, I share my first take on 2 to 3 attractive ideas.
As usual, if you want me to dig deeper into an idea, vote for it. Use the poll at the end of this email.
Canada Goose Holdings Inc. (GOOS CN)
Shares sold off because management extrapolated strong demand and overstocked.
However, the market may be overlooking early signs of recovery.
Inventory days have started falling and is now below historical median. Customer perception of the brand remains healthy.
In August 2025, GOOS received takeover offers valuing it at twice today’s share price.
Major shareholder Bain Capital first invested in 2013 and has strong incentive to sell soon. CEO bought more shares in September 2026.
About (6 Oct 2026)
Share price: CAD 10.79
Market capitalisation: CAD 1,064 mn (USD 748 mn)
Enterprise value (EV): CAD 1,707 mn (USD 1,201 mn)
Average daily volume (ADV): CAD 3 mn (USD 2 mn)
NTM P/E: 12x
My initial estimate suggests ~ 7% free cash flow yield on enterprise value.
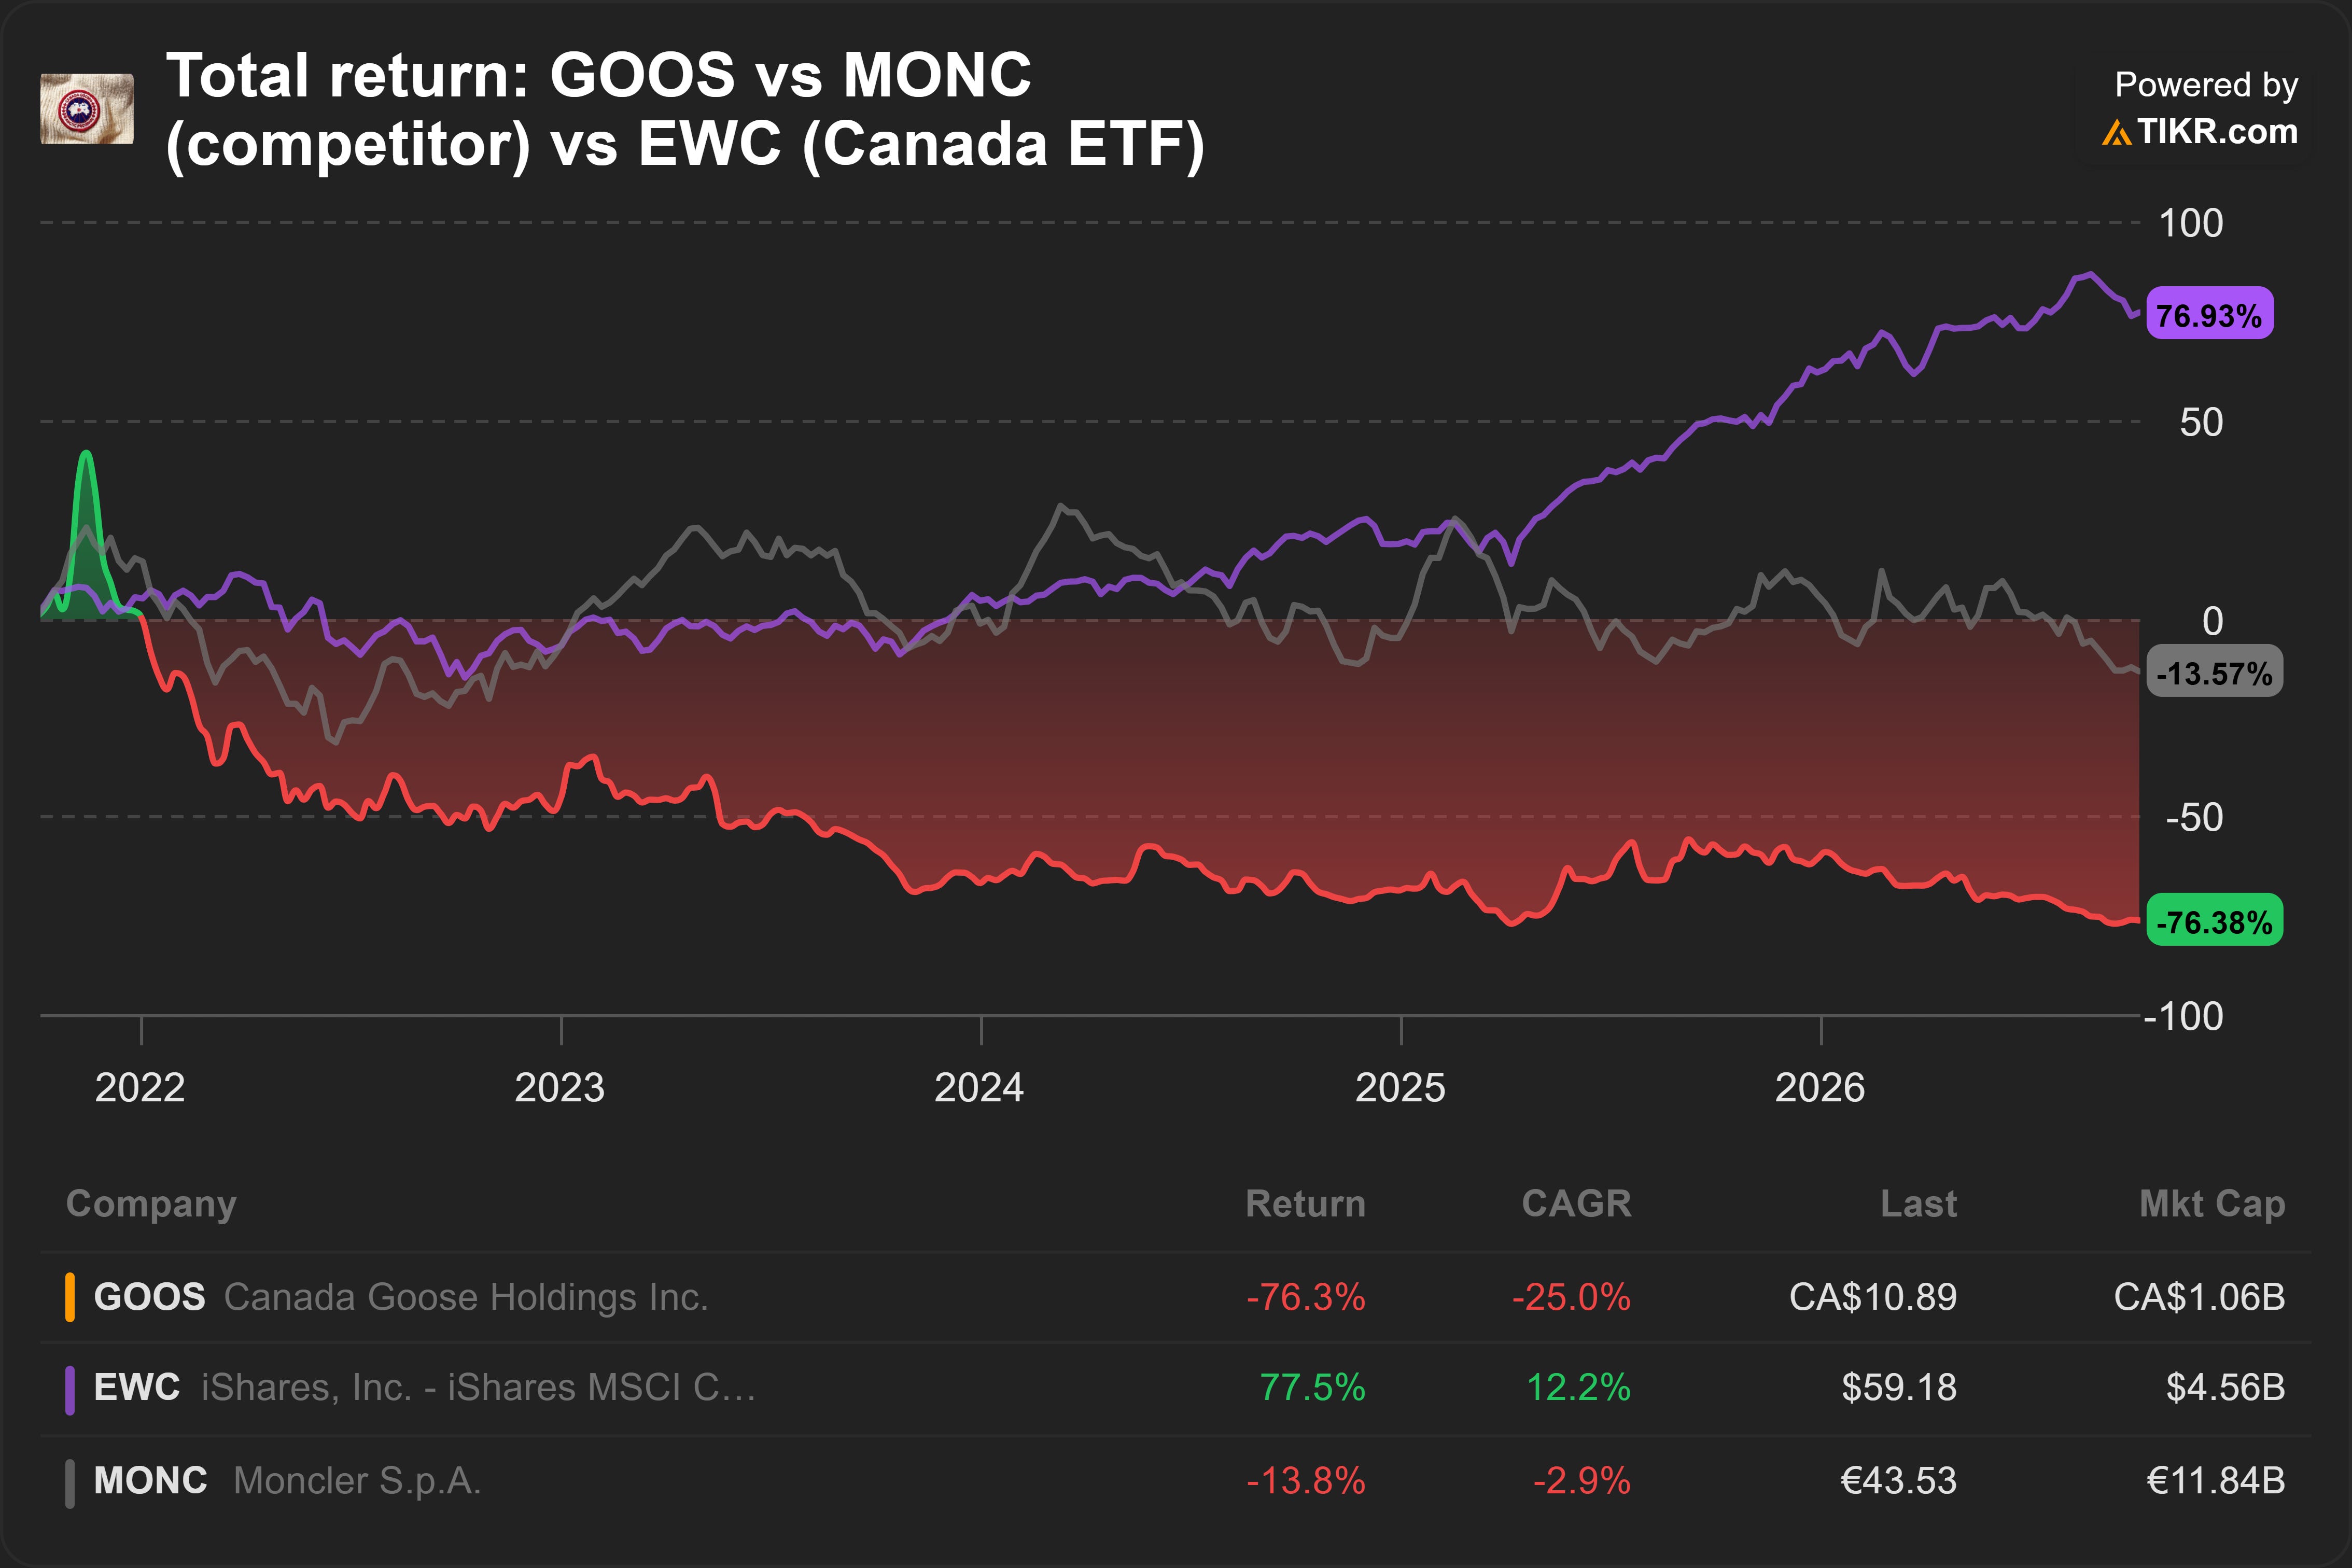
The shares have fallen over the past 5 years on the back of decelerating revenue growth.
GOOS manufactures and sells luxury performance outerwear. It is famous for its parkas.
It earned CAD 1,528 mn revenue in FY2026 (+13% YoY):
76% direct-to-consumer (DTC) (+16% YoY)
19% wholesale (+12%)
5% Others (-10%)
Good business, temporary headwinds?
The business seems to be facing a temporary headwind.
Coming off a period of high demand during 2017-2018, they seem to have overestimated demand and overstocked inventory
However, there appear to be early signs of recovery. Inventory days have started coming down.
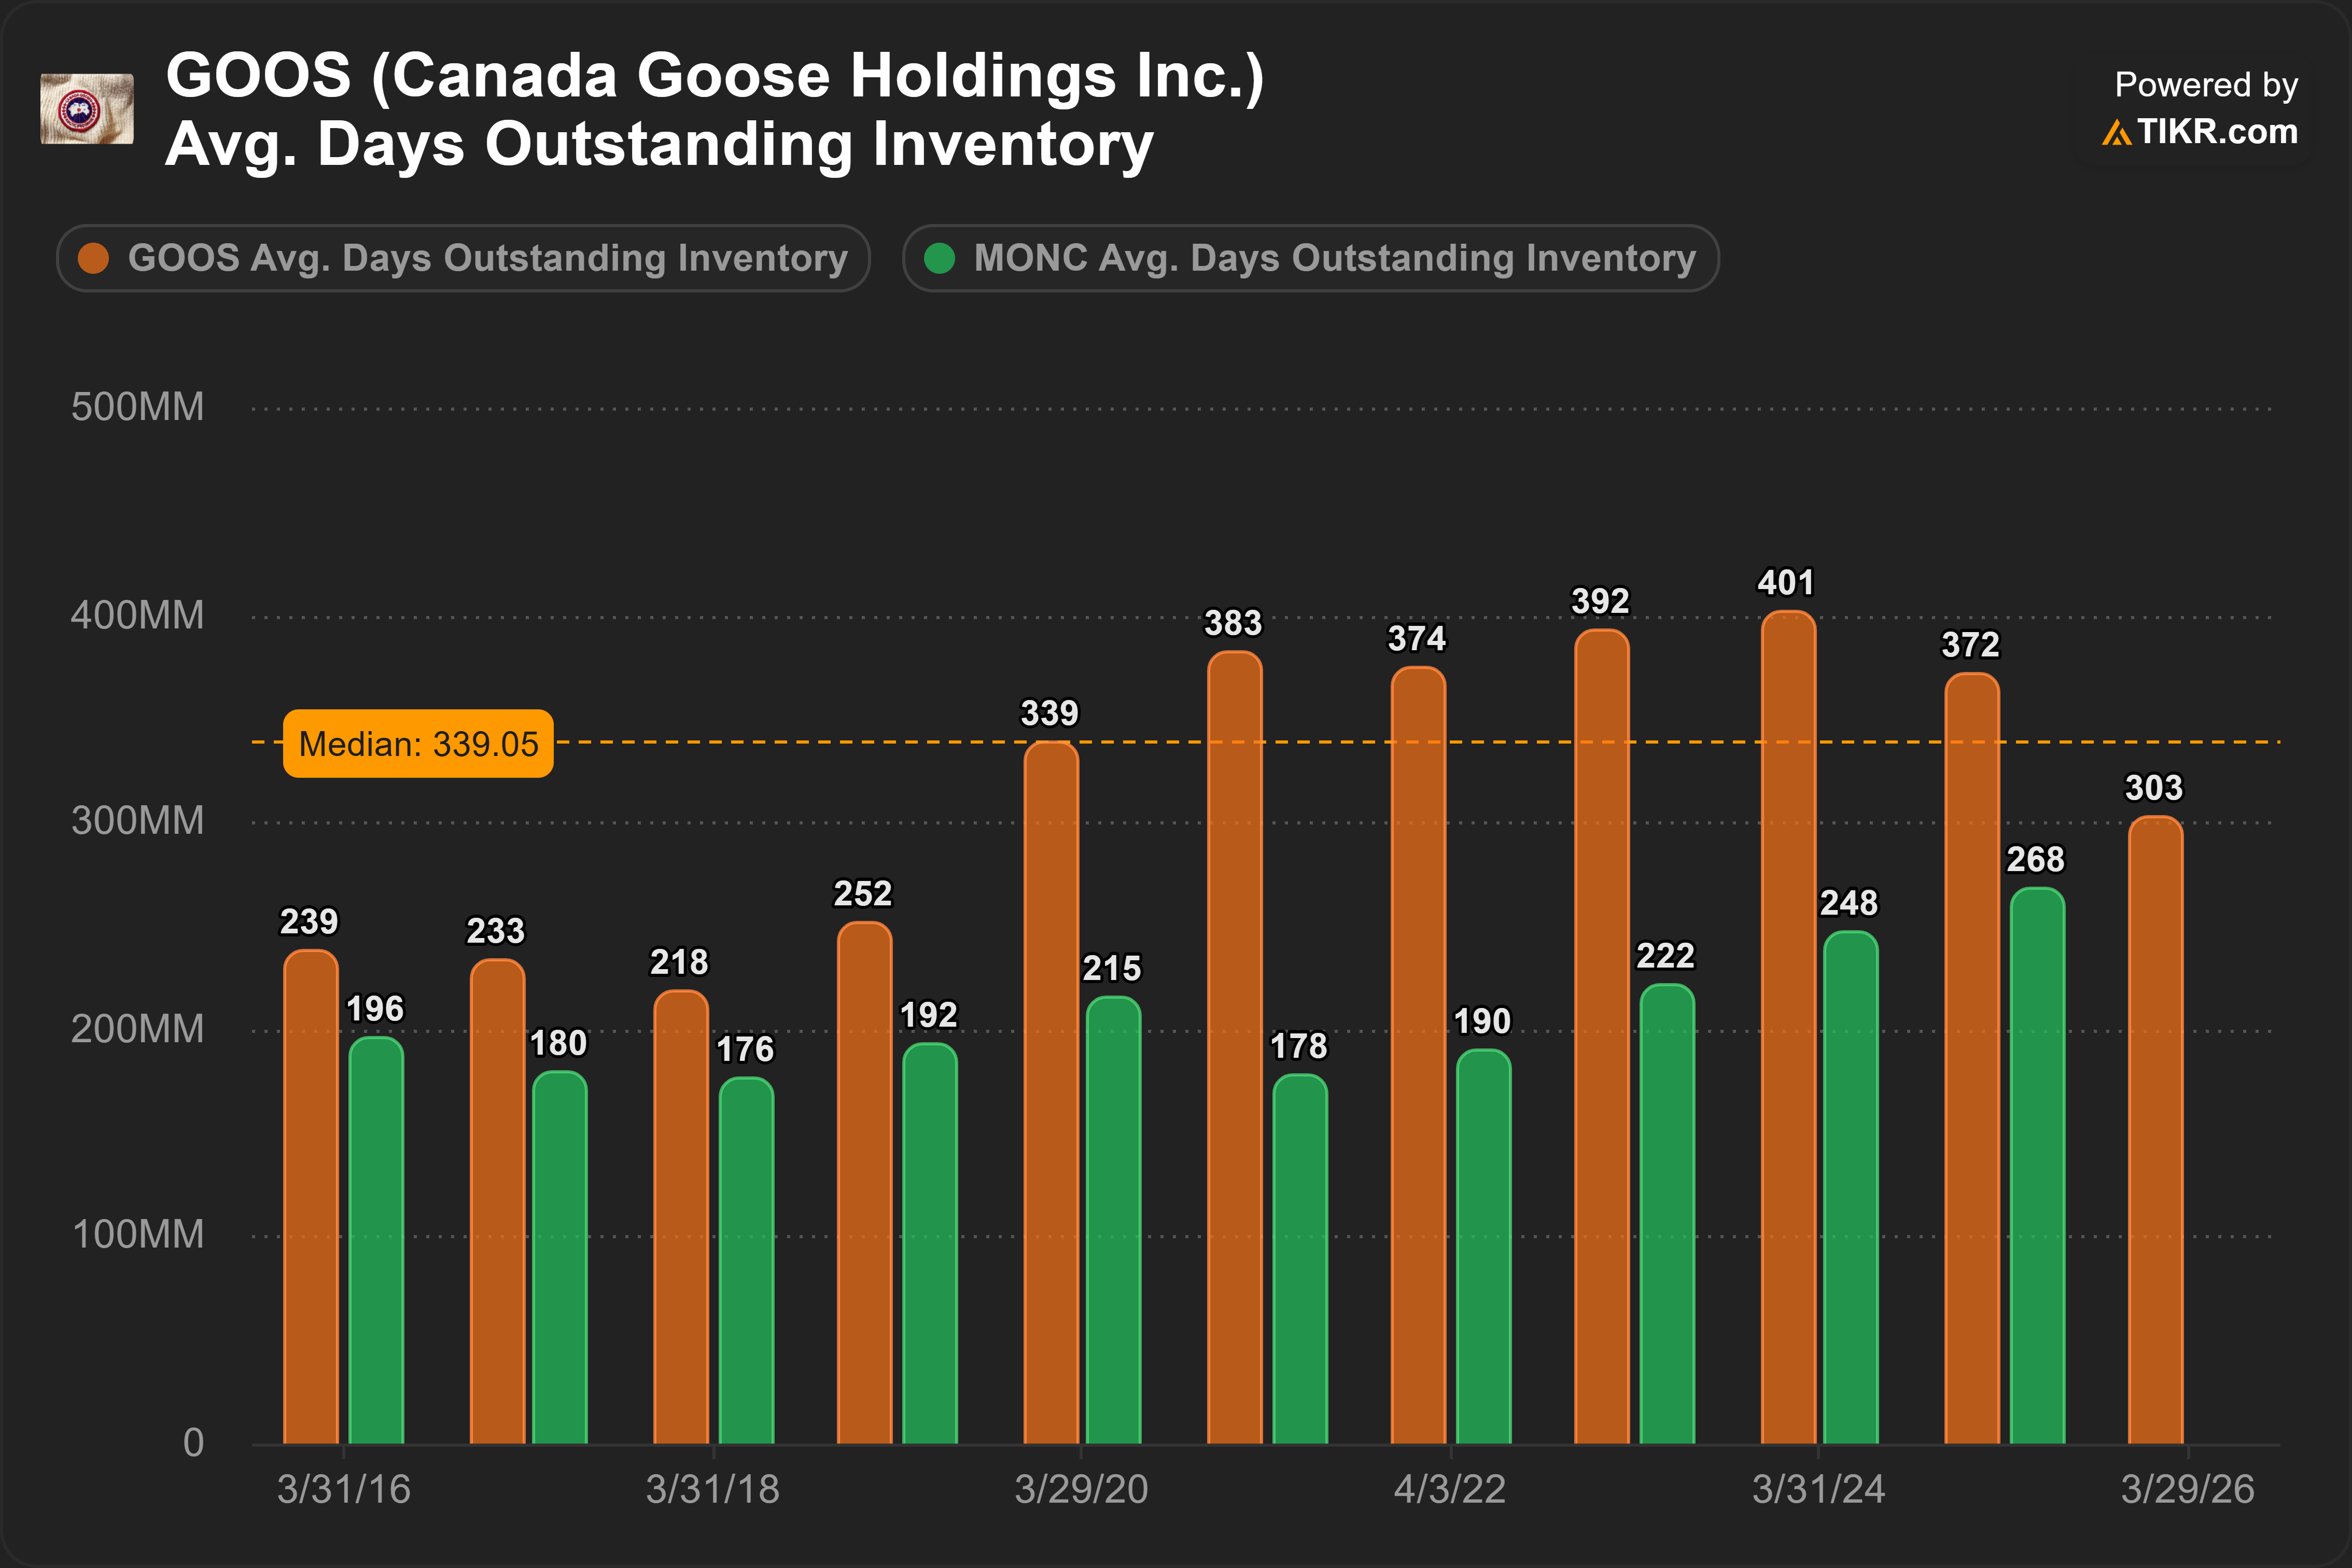
By FY2026, inventory days have fallen below median levels, and is much closer to Moncler S.p.A. (MONC IM).
The brand remains intact. Online reviews are generally favourable.1
Return on asset (ROA) should improve significantly as GOOS continues destocking. ROA in FY2026 was also depressed by a one-time arbitration settlement of CAD 44 mn.
Potential sale?
In August 2025, CNBC reported GOOS received takeover offers at ~ CAD 20 per share.2 This is almost twice of today’s share price.
The controlling shareholder, PE firm Bain Capital, has engaged Goldman Sachs to advise and get better offers.
I suspect a sale will likely happen sooner than later. It has been 13 years since Bain Capital first invested in GOOS.
On 9 September 2026, CEO Dani Reiss acquired 100,000 more shares at ~ CAD 10.62. He owns ~ 22% of shares outstanding.3
Factors to focus on
What are the short-sellers betting on? Although short interest has fallen off its peak around 2023, it still remains on the high side ~12%.
Receivable days started increasing from FY2024. Why?
Headline receivable days ~ 25 days. But this likely understates the true figure because it includes retail sales.
According to my initial estimates, wholesale receivable days is ~ 115 days in FY2026, up from ~30 days in FY2023. What happened?
US tariffs on Canadian goods (GOOS manufactures mainly in Canada)
WH Group Limited (288 HK)
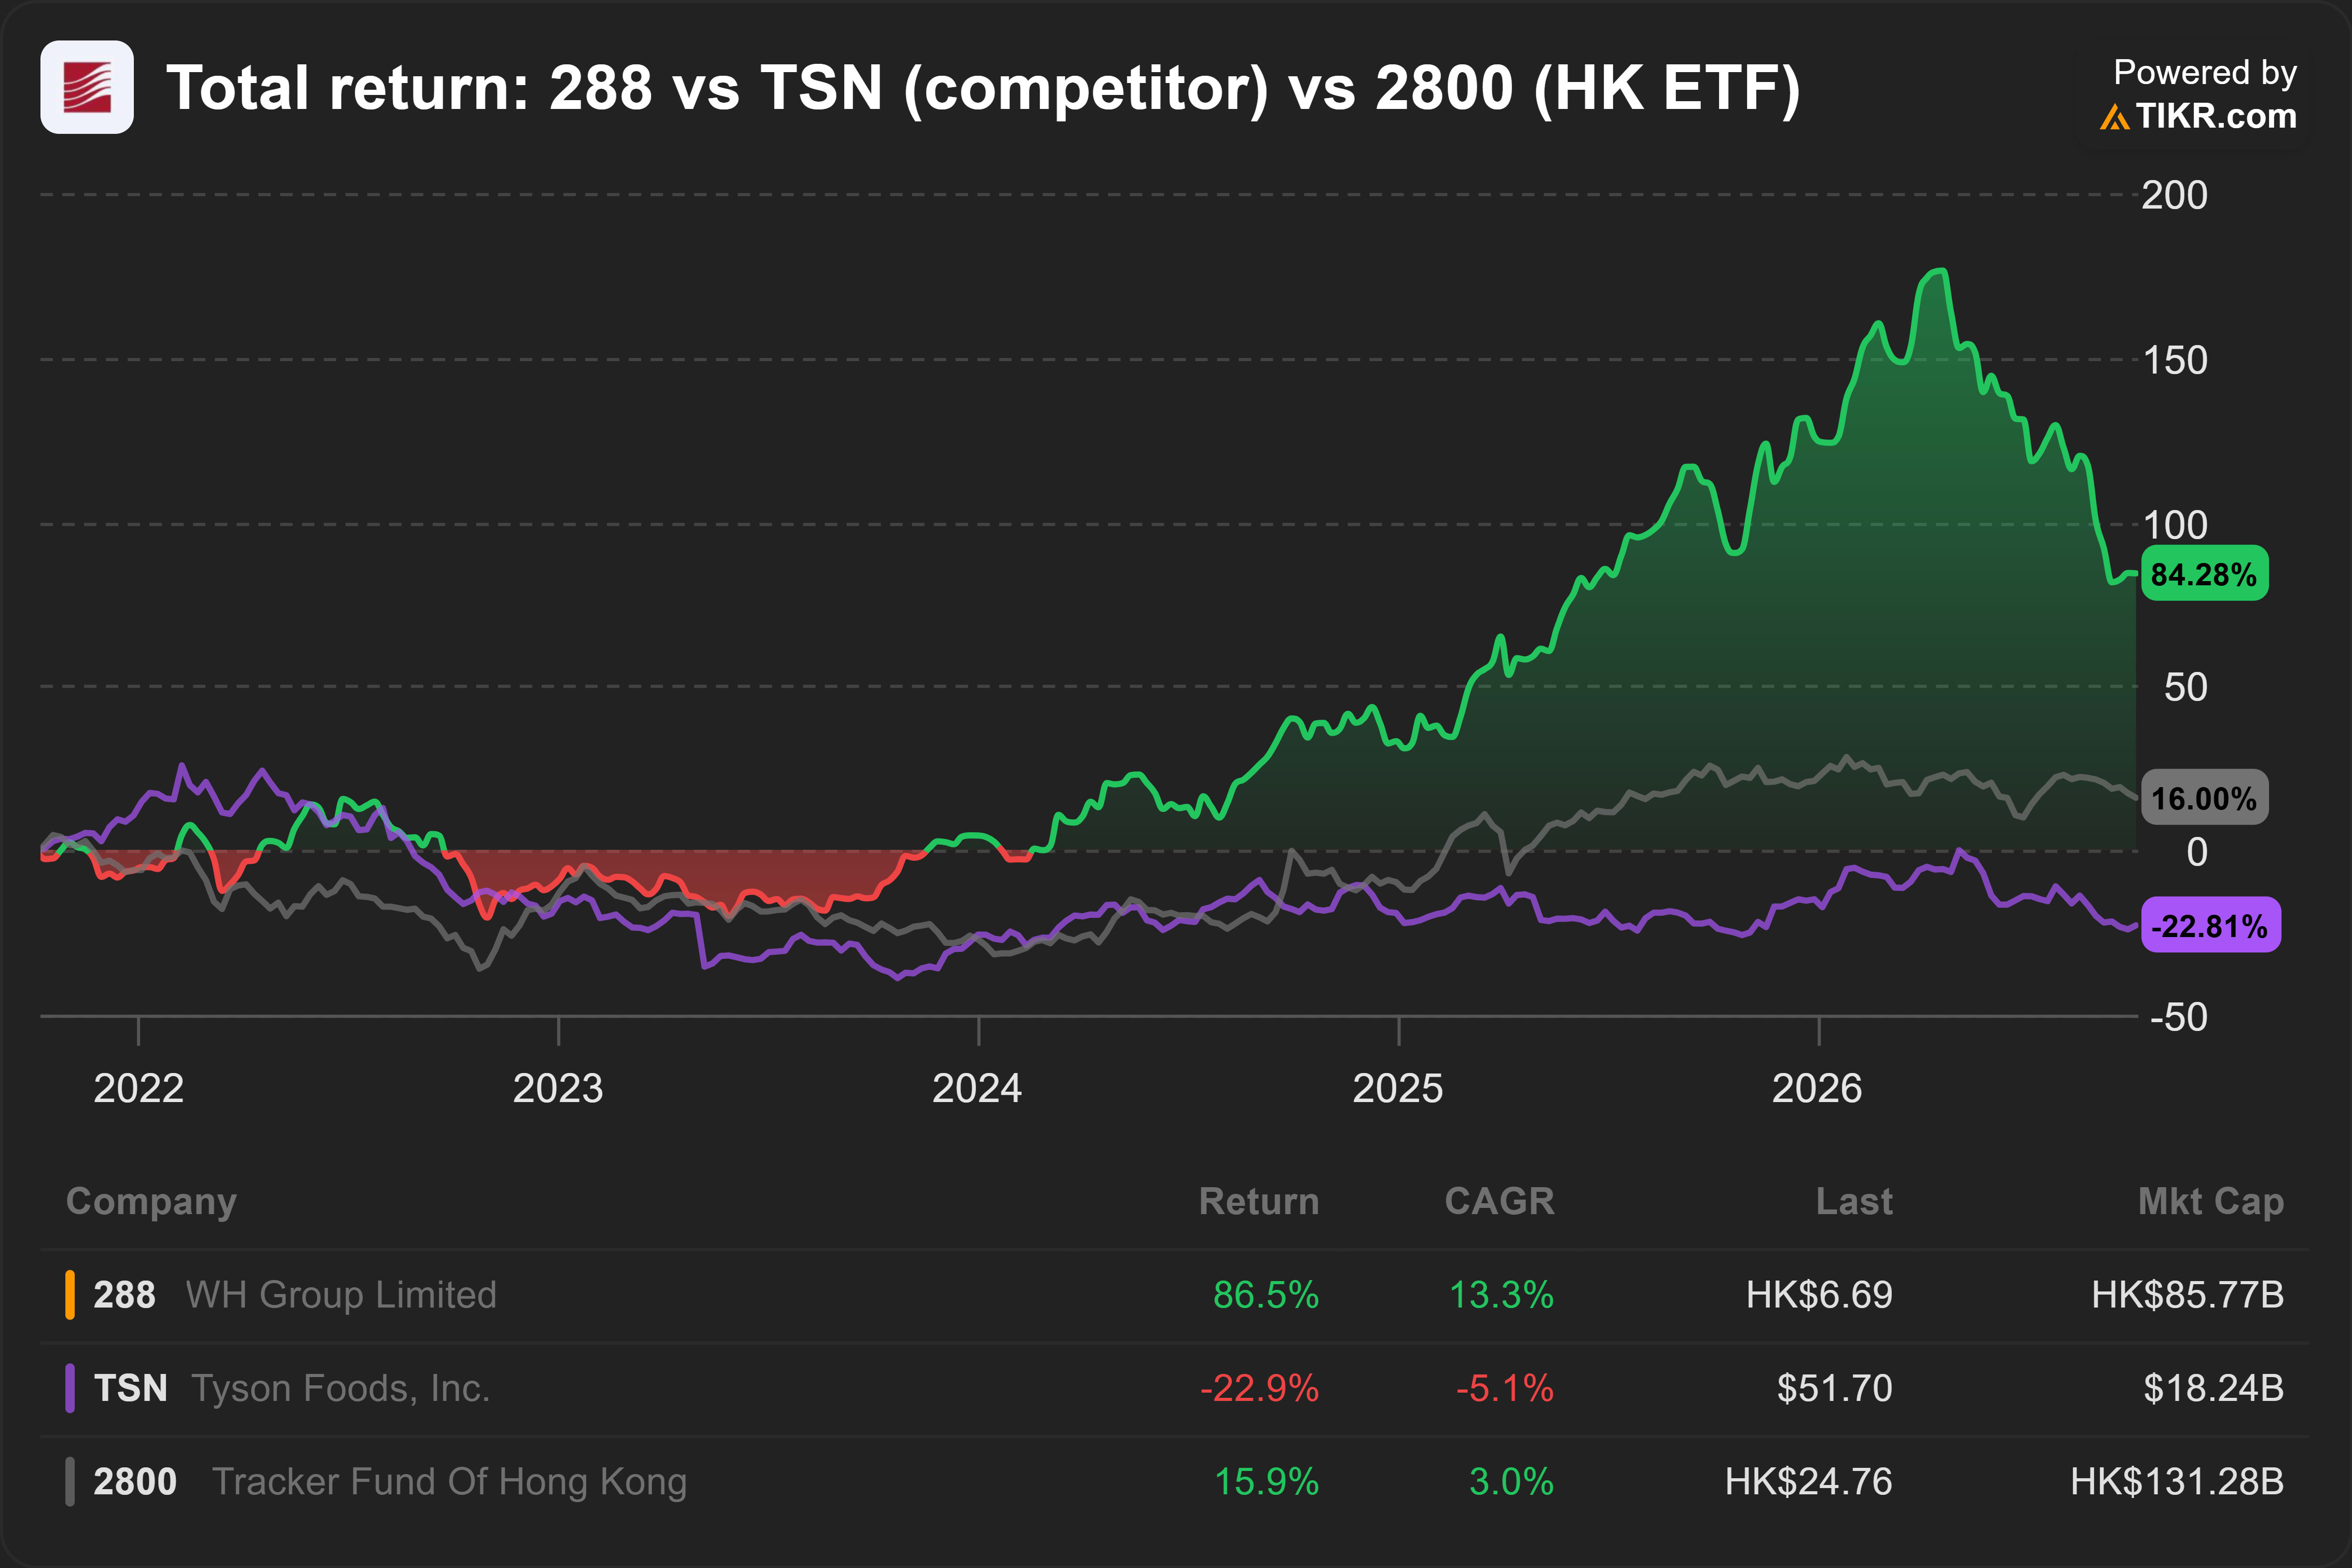
At ~11% FCF yield, the market seems to be pricing WH like a volatile fresh pork producer.
They are ignoring the shift in focus to packaged meat products. These produce much more stable and resilient cash flows. Branded retail products offer stronger pricing power than commoditised fresh pork.
9.3% dividend yield is attractive and looks sustainable.
Management is focusing on capital returns. They IPO’d their US subsidiary, and used the proceeds to pay special dividends.
Future capex needs will be lower. Packaged meat products are less capital intensive than fresh pork.
About (7 Oct 2026)
Share price: HKD 6.57
Market capitalisation: HKD 85,770 mn (USD 10,928 mn)
Enterprise value (EV): HKD 107,916 mn (USD 13,750 mn)
Average daily volume (ADV): HKD 311 mn (USD 40 mn)
NTM P/E: 7x
My initial estimate suggests ~ 11% free cash flow yield on enterprise value.
WH is the world’s largest pork processor, with operations in packaged meats, fresh pork, and hog production.
The company derives over 50% of its revenue from packaged meats and about 40% from fresh pork and hog production.
In 2025:
China contributed 30% to revenue under Henan Shuanghui Investment & Development Co. Ltd. (Shuanghui), with 38% from packaged meat and 44% from fresh pork.
The U.S. contributed 54% under Smithfield, with 58% from packaged meat and 42% from fresh pork.
Europe contributed 15%, with 50% from packaged meat and 27% from fresh pork.4
Attractive capital returns
WH has been raising capital returns over the past few years. Today, it trades at ~ 9.3% dividend yield, a 7.6 percentage points premium over China 10y government bond.
Such a high premium suggests investors are doubting whether WH can sustain its dividends.
WH looks very exposed to volatile hog prices. In 2023, unfavourable hog prices caused operating losses at the fresh pork segment in the US. Group operating profits fell -30%.
WH started scaling back on its fresh pork segment, focusing on its packaged meat segment.
This segment is much more stable and resilient. In 2023, operating profits from packaged meat remained stable. Branded retail products carry much stronger pricing power than commoditised fresh pork.
As a result, WH’s cash flows today are much more stable and resilient.
Management is also focusing more on capital returns. It IPO’d its US subsidiary, Smithfield Foods, Inc. (SFD 0.00%↑ US) in 2025 and used the proceeds to pay special dividends of HKD 1.08 per share.
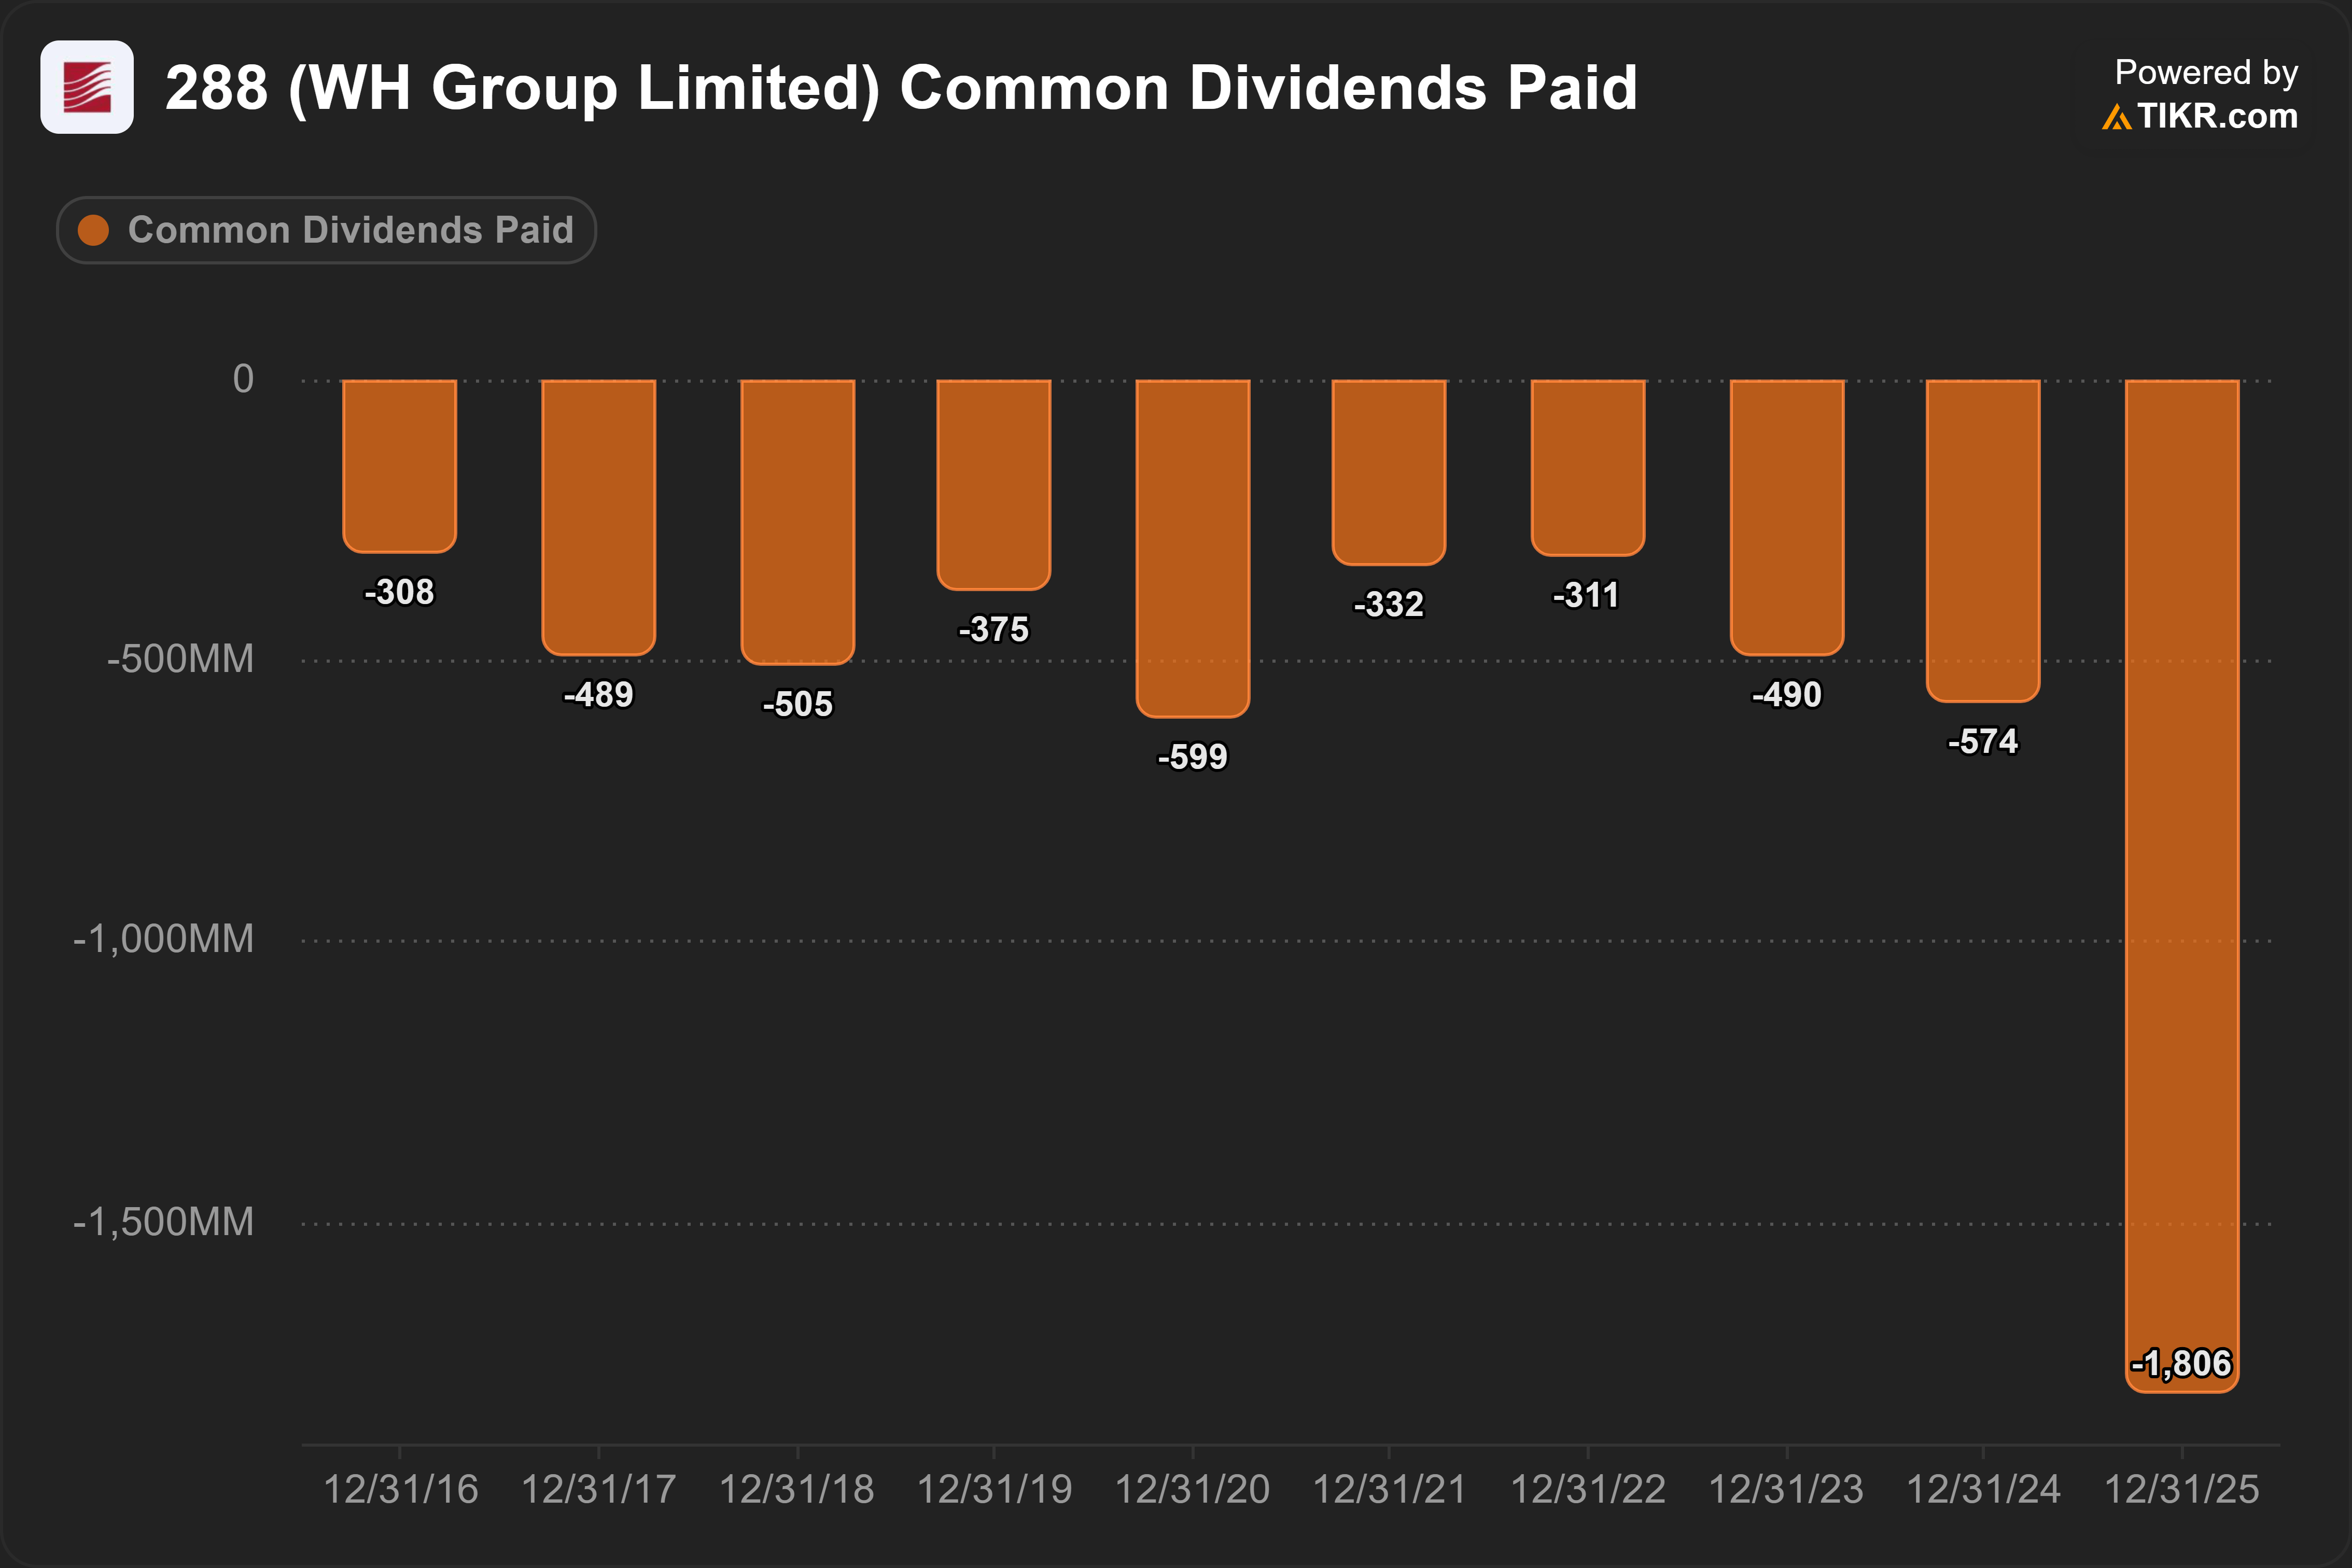
Management focusing on capital returns. Huge jump in cash outflow for dividends (USD’M) in 2025, funded by SFD’s IPO
There may be more dividends or share buybacks. Cash today is ~ 13% of revenue, above historical average of mid-single digit. Capex needs are lower. Packaged meat is more capital-light than producing fresh pork.
All these factors together suggest the 9.3% dividend yield is likely much more sustainable than what the market is currently pricing in.
Factors to focus on
More evidence that the cash flows today are more resilient and stable to hog prices
Impact of US tariffs. Risk seems low because production is mostly done locally
Vote for the best idea
If you want me to dig deeper into an idea, vote for it.
Coming up next
I will look deeper into Genting Singapore (G13; GENS SP) this week. This was the idea you voted as the most interesting in my previous email.
Investors seem to be expecting revenue to continue declining through 2026 and beyond.
However, they are overlooking the inflection points in several key indicators. The percentage of receivables not past due has recovered to its historical average. Contract liabilities, another leading indicator, has already inflected.
Revenue growth, therefore, has likely already bottomed out.
In 2022, international peers like MGM Resorts indicated interest in buying GENS. The major shareholder declined.
Today, high financial leverage at the major shareholder may cause a rethink.
Subscribe to get the analysis when I publish.
Subscribe for 2 to 3 analyses of global SMID equities every week.
Discover overlooked ideas and rethink familiar names.
Published by Andrew Wong, ACA, CFA
In case you missed it
Previously, I highlighted the opportunity I see in Li Ning Company Limited (2331 HK).

3 reasons why buying stocks just because of low P/E can blow up your portfolio.

Disclaimer
This publication is for informational, educational, and entertainment purposes only and does not constitute financial, investment, legal, or tax advice. The content herein is a record of my personal research and investment process, and all analysis, forecasts, and opinions expressed are solely my own.
I make no representation or warranty, express or implied, as to the accuracy, completeness, or timeliness of the information provided. The stock market is highly volatile, and my forecasts, estimates, and assumptions may prove incorrect.
I am not acting as your financial advisor or fiduciary. You should not rely on any information in this publication to make investment decisions. Under no circumstances will I be held liable for any direct, indirect, or consequential losses or damages arising from your reliance on the content of this publication.
At the time of publication, I do not hold any positions in GOOS CN or 288 HK, either long or short. I may change my views, predictions, or personal portfolio positioning at any time without notice.