

Every Monday, I share my first take on 2 to 3 attractive ideas. (Sorry for this week’s delay).
As usual, if you want me to dig deeper into an idea, vote for it. Use the poll at the end of this email.
Raffles Medical Group Ltd (BSL; RFMD SP)
RFMD is one of the largest private healthcare providers in Singapore. Its share price sold off as COVID-19 related revenue rolled off.
In July 2026, the sell-off accelerated when a new public hospital absorbed patient volume, causing revenue at its Healthcare segment to decline unexpectedly.
However, the decline in Healthcare revenue obscured the growth at the other segments. Hospital segment profits grew +11% YoY. The Insurance segment inched closer towards break-even, with operating losses falling -64% YoY.
Furthermore, management reported Healthcare volume has stabilised in Q3’26.
Management is returning capital to shareholders. I expect higher capital returns as RFMD completed construction of new hospitals.
About (23 Oct 2026)
Share price: SGD 0.82
Market capitalisation: SGD 1,500 mn (USD 1,173 mn)
Enterprise value (EV): SGD 1,269 mn (USD 993 mn)
Average daily volume (ADV): SGD 2 mn (USD 2 mn)
NTM P/E: 24x
My initial estimate suggests ~ 7% long-term free cash flow yield on enterprise value, ~ 5% premium over the Singapore 10-year government bond. Looks attractive.
RFMD is one of the largest private healthcare providers in Singapore.
2025 revenue of SGD 765 mn:
40% Hospital (+6% YoY)
35% Healthcare (e.g. general practitioner clinics) (-4% YoY)
24% Insurance (+4% YoY)
1% Investments (-5% YoY)
Under-recognised growth?
Over the past 3 years, RFMD (or BSL) shares trailed ES3 (Singapore ETF). Revenue growth decelerated as COVID-19 revenue rolled off.
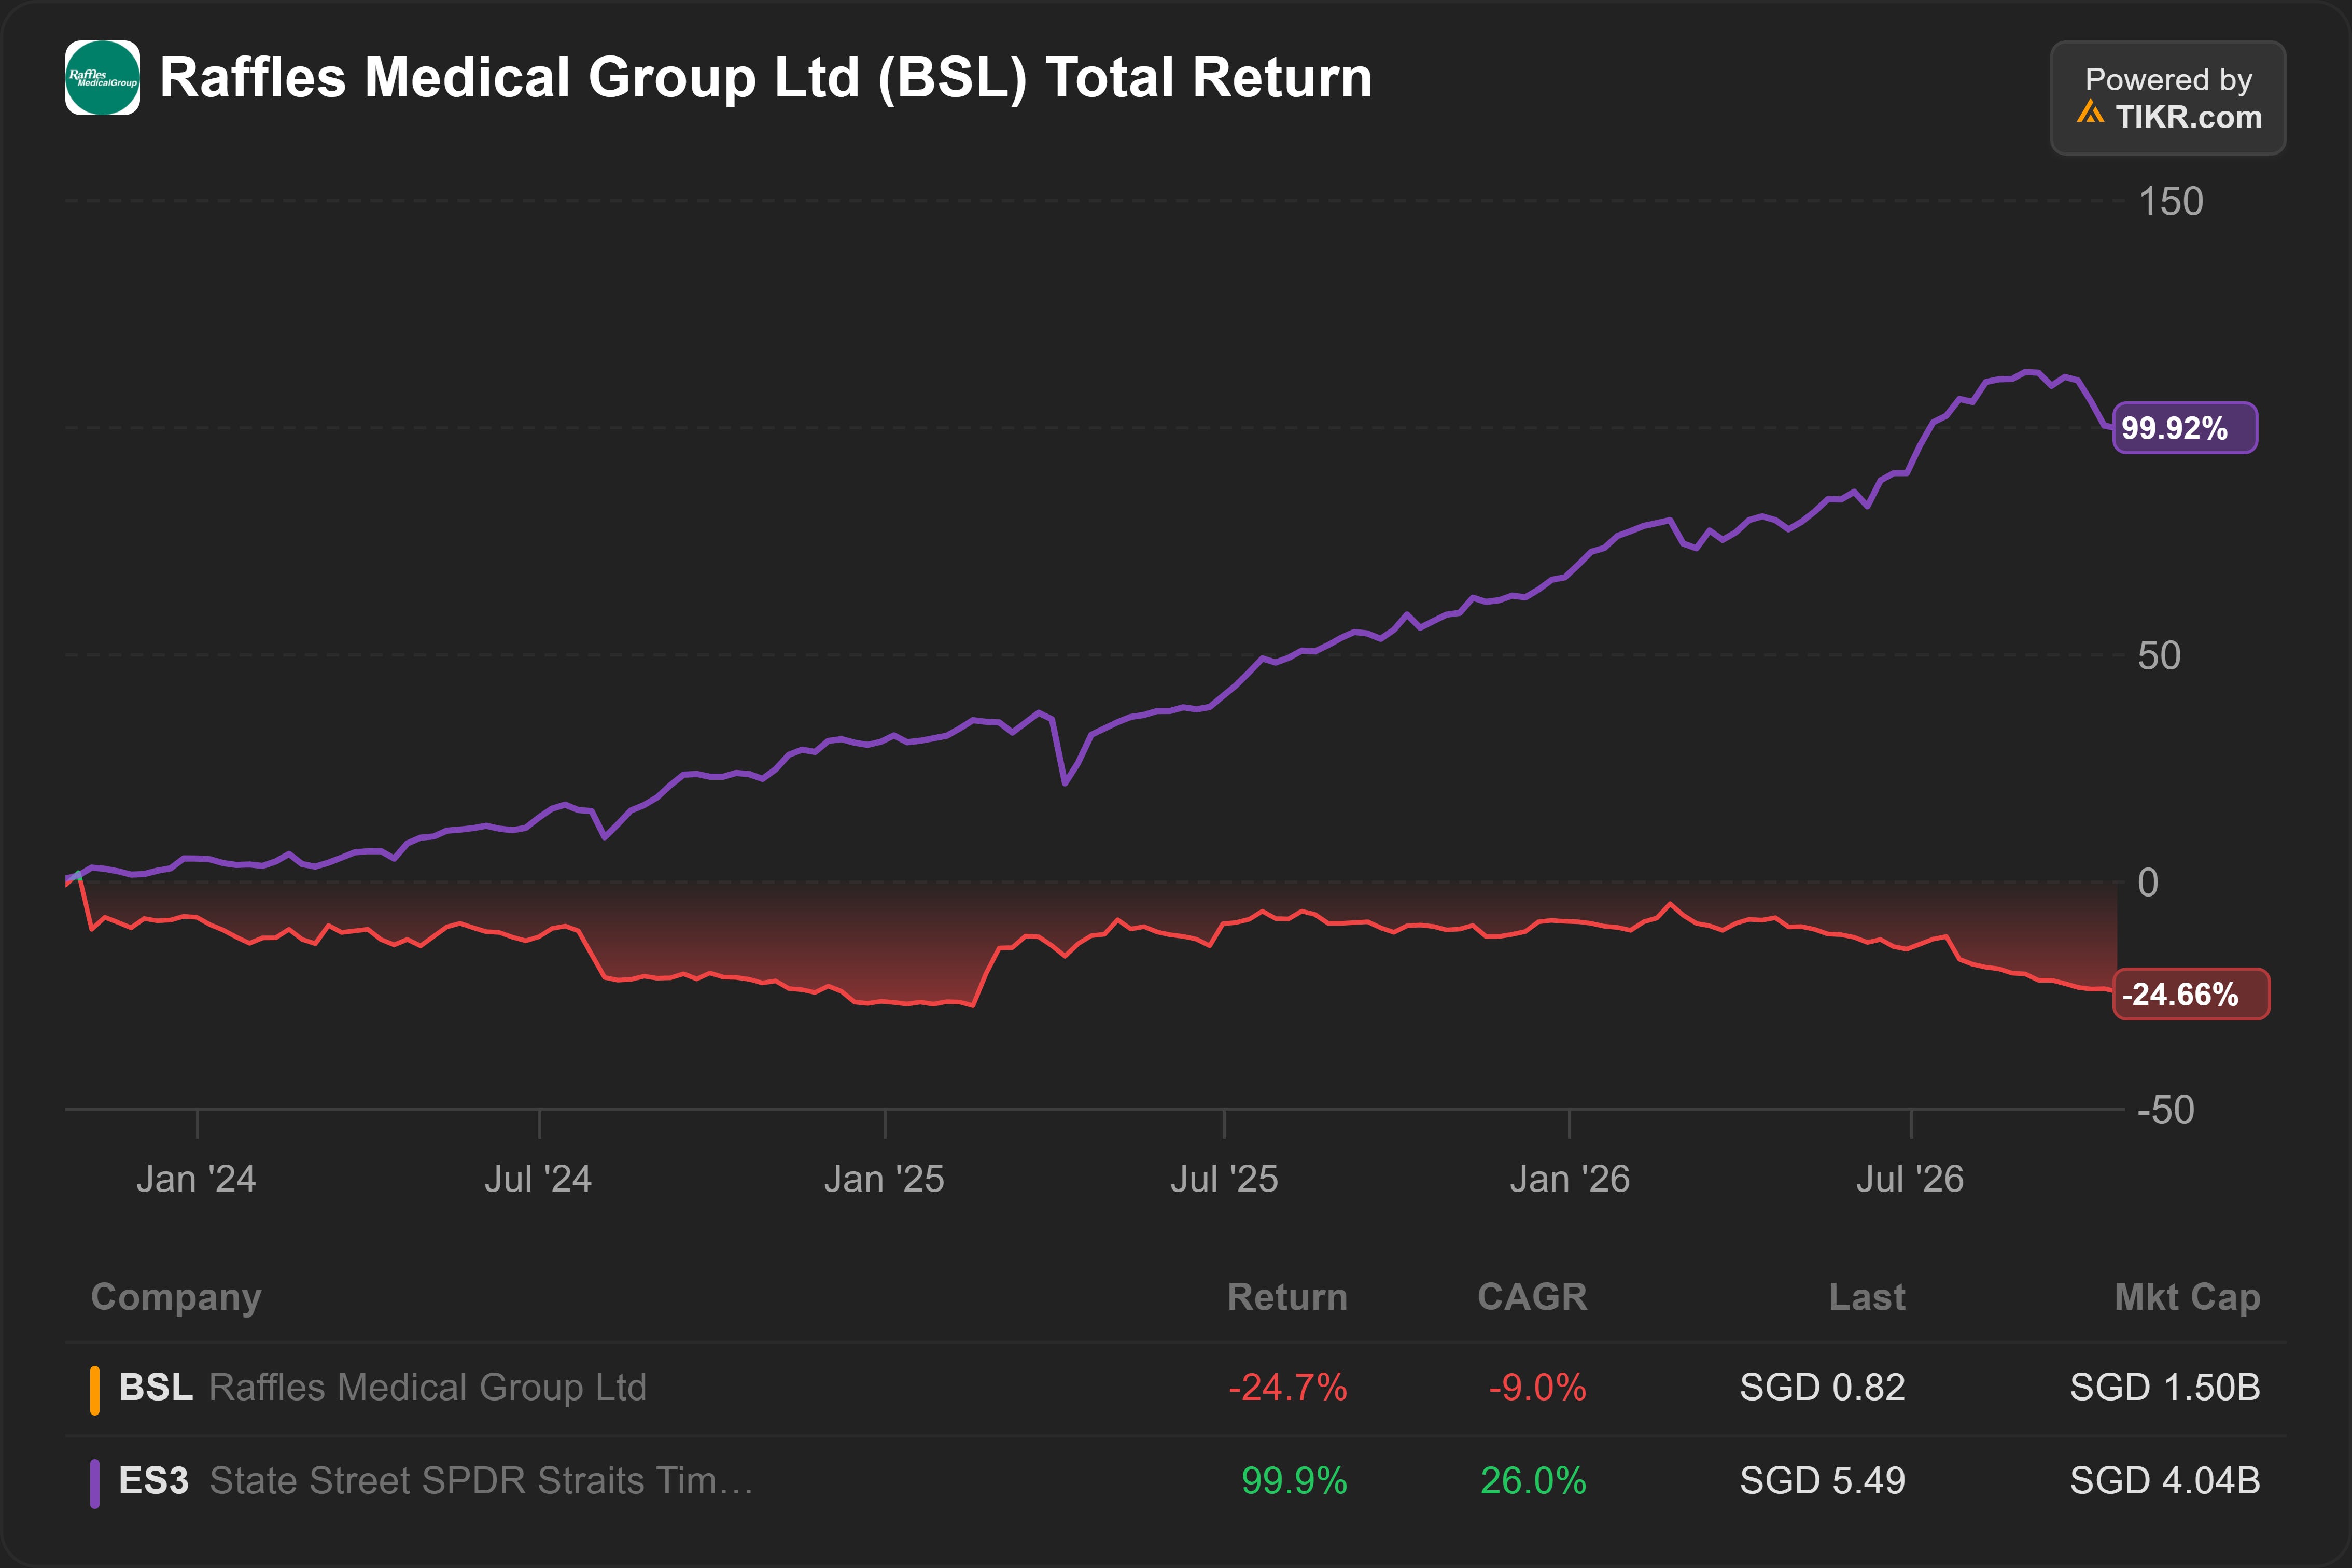
The sell-off accelerated in July 2026.
During that month, RFMD reported Healthcare revenue declined -16% YoY during H1’26. Profits fell -37% YoY.
The main driver was lower occupancy at transitional care facilities (TCF). A new public hospital, Woodlands Hospital, absorbed patient volume that was previously routed to RFMD’s TCF.
However, the decline in Healthcare obscured the growth at the other segments.
Hospital profits grew +11% YoY. The Insurance segment inched closer towards break-even, with operating losses falling -64% YoY.
Management reported that TCF occupancy has stabilised in Q3’26.1 If this is true, headline revenue and profits will return to growth soon.
Capital returns?
RFMD is returning more capital to shareholders.
Dividend yield reached 3.7%, an all-time high. I believe there is room for further increase.
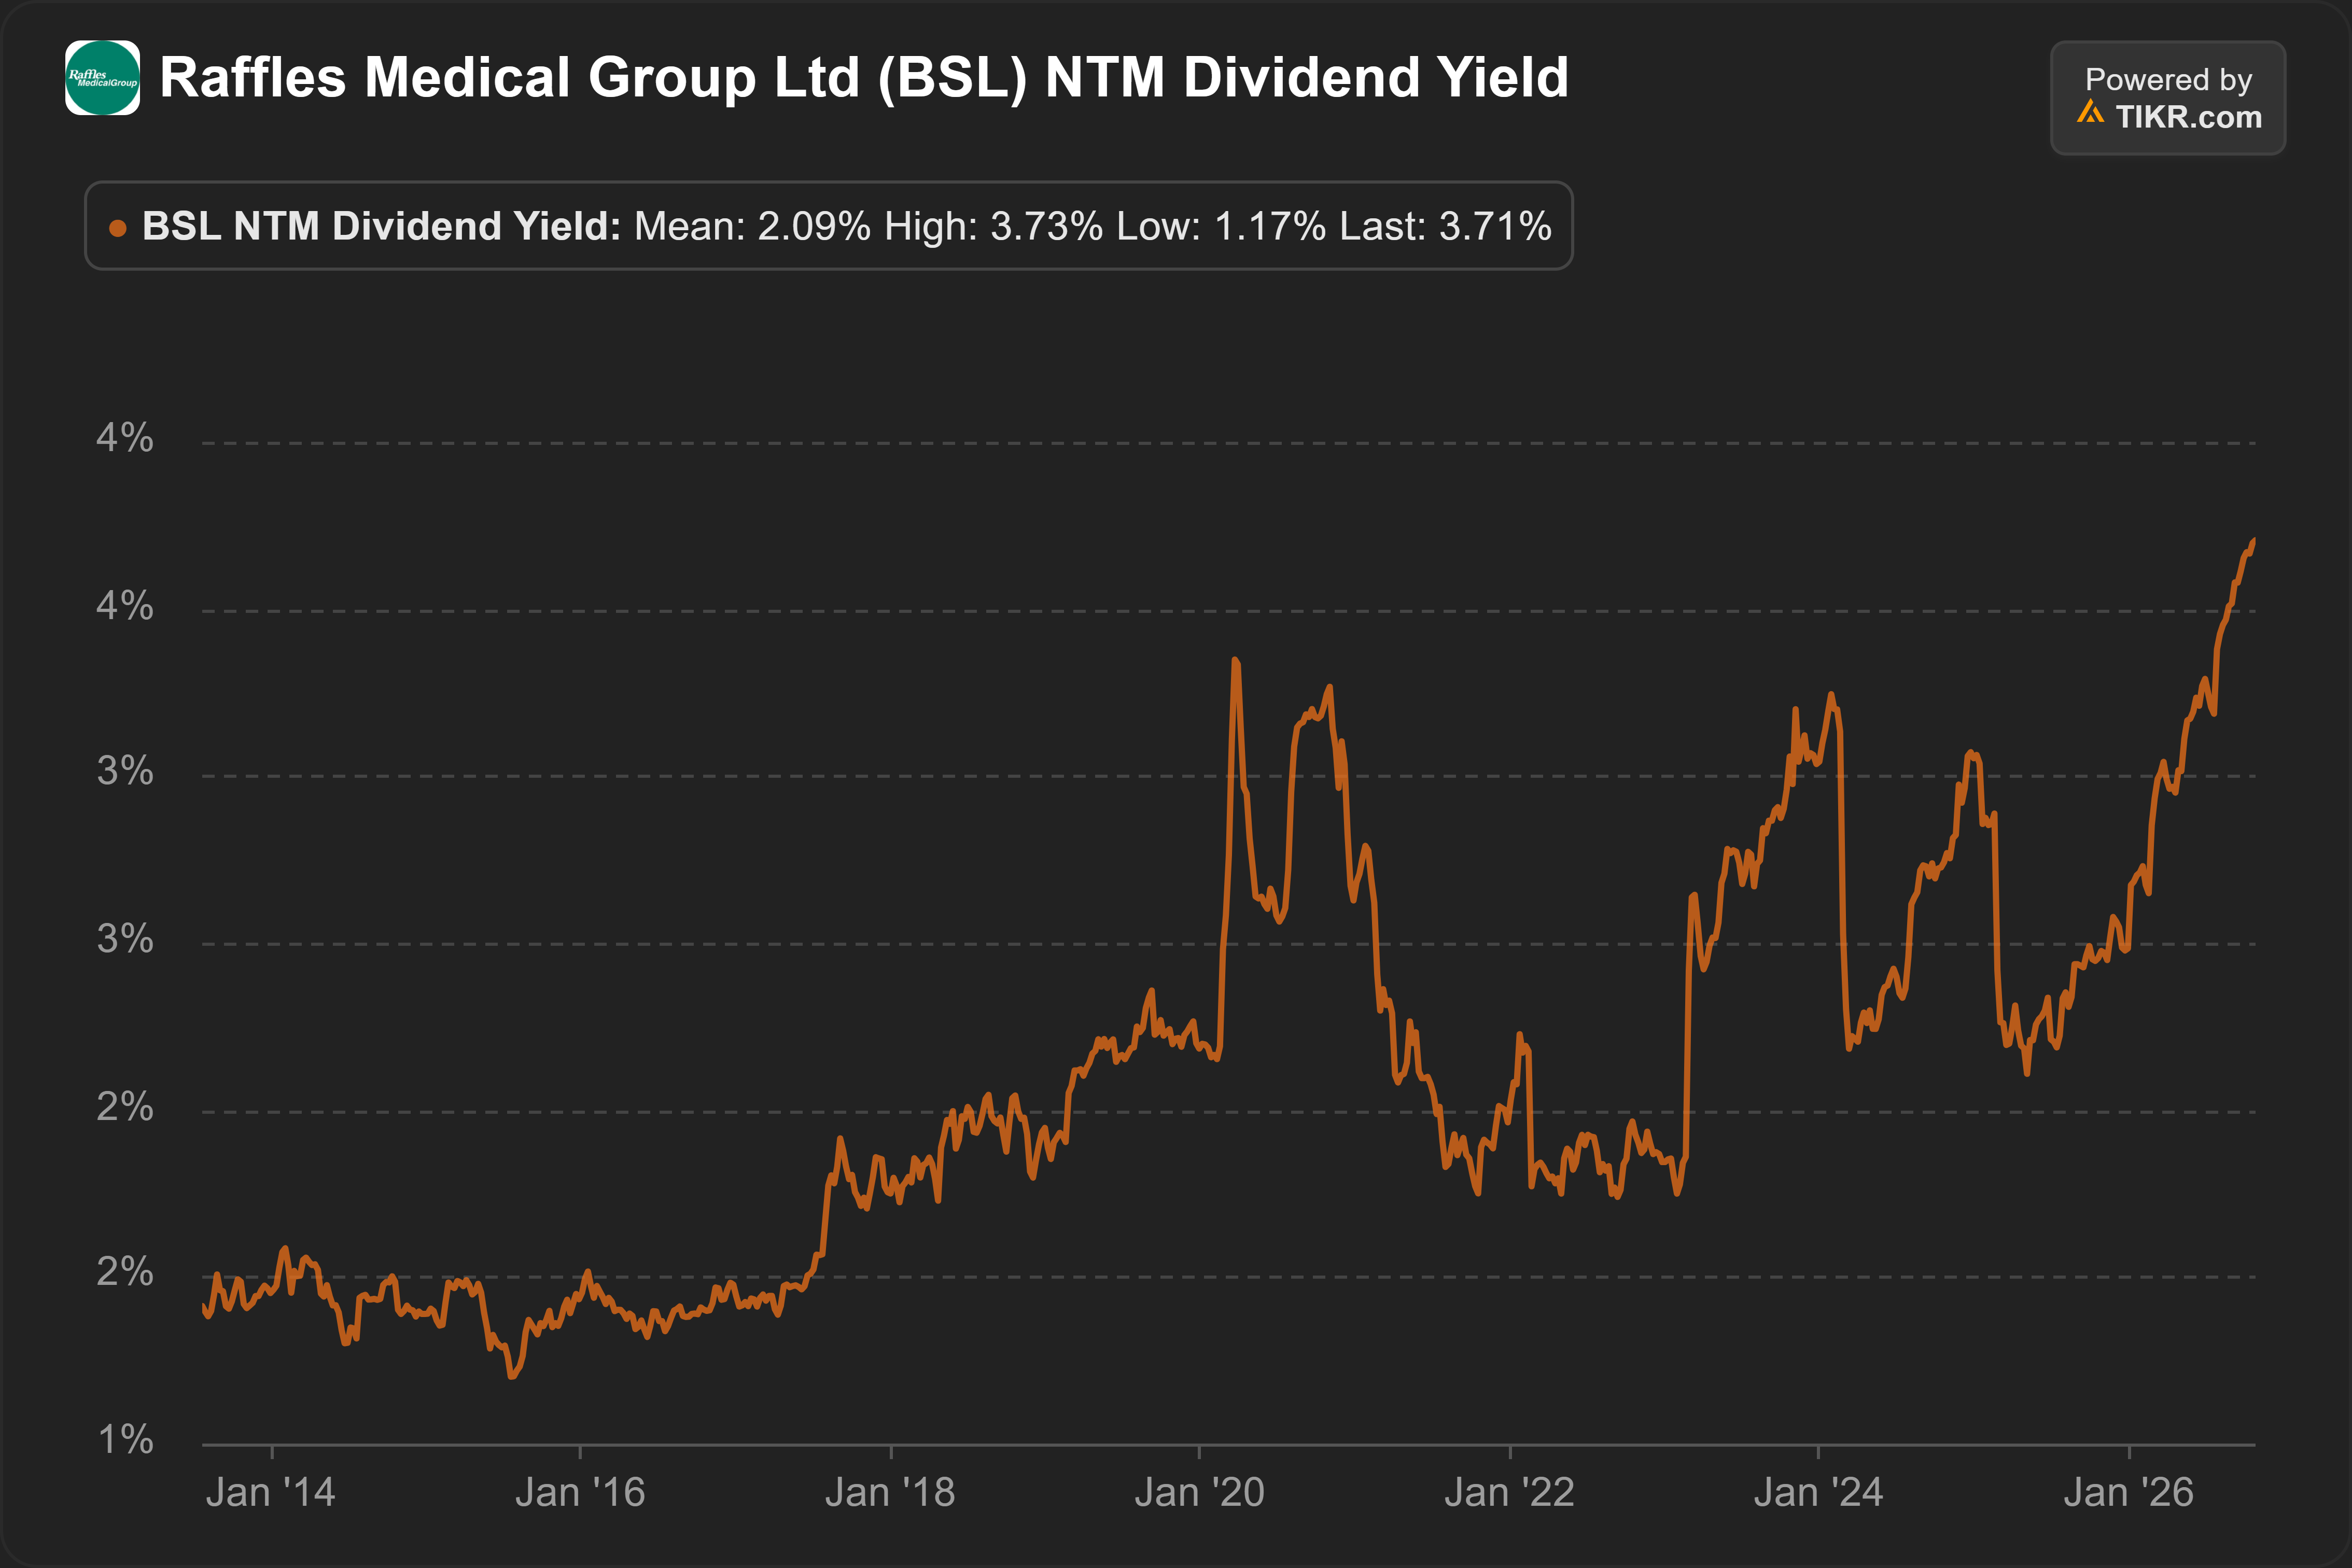
RFMD is able to return more capital because capital expenditure requirements are now lower. The company just completed construction of its hospitals in China.
Starting from 2021, management committed to dividend payout ratio of up to 50% of the average sustainable profit after tax and minority interest (PATMI).
From 2025 onwards, RFMD revised its dividend policy to commit to paying out at least 50% of its sustainable earnings annually.2
In April 2026, RFMD also launched a share buyback program.
Factors to focus on
Outlook for Healthcare segment, especially TCF
Growth opportunities at Hospital segment
Break-even at Insurance segment
Potential for higher capital returns