

[Shortlist] Riverstone Holdings Limited (AP4; RSTON SP)
Last week, you highlighted a potential opportunity in RSTON. What’s your suggestion?
Shortlist RSTON: cyclical inflection and capital returns.
Over the past few years, shares have sold-off over industry oversupply.
Recently, peers started recovering. However, investors seem to ignore the positive industry read-through.
Other evidence of cyclical inflection: positive shift in management commentary, inflection in working capital trends and upcoming volume production at customers’ new factories.
7% dividend yield is likely sustainable due to management’s commitment to 100% payout ratio, supported by strong balance sheet.
Liquidity?
29 Oct 2026
Share price: SGD 0.74
Market capitalisation: SGD 1,104 mn (USD 862 mn)
Enterprise value (EV): SGD 922 mn (USD 720 mn)
Average daily volume (ADV): SGD 2 mn (USD 1 mn)
NTM P/E: 15x
What does RSTON do?
RSTON makes gloves.
Healthcare gloves are used by doctors and nurses for medical examinations, etc.
Cleanroom gloves are used in the semiconductor and pharmaceuticals industries, where technical requirements are more stringent. According to management, RSTON holds ~ 40% market share worldwide.1
It allocates roughly 80% of production capacity to healthcare gloves and 20% to cleanroom gloves, but the cleanroom segment contributes around 70% of the group’s gross profit.2
CGS International, a broker, estimates RSTON’s cleanroom gloves yield ~ 46% gross profit margin (GPM), almost 3x the GPM achieved by healthcare gloves.3
In effect, RSTON’s profits are driven more by semiconductor trends rather than healthcare.
Customers open more factories and/or higher utilisation rate => higher demand for RSTON’s cleanroom gloves.
Cyclical inflection
Ansell Limited (ANN AU) is a direct competitor to RSTON’s cleanroom segment while Top Glove Corporation Bhd. (TOPGLOV; TOPG MK) competes against RSTON in its healthcare segment.
ANN reported accelerating revenue growth. In H2’26, its Cleanroom revenue grew +17% YoY, up from +3% YoY in H1’26.4 ANN’s financial year ends in June.
TOPG reported better-than-expected earnings for the quarter ended 31 August 2026.
In early October 2026, TOPG’s management explained:5
“Demand and supply growth are now becoming more balanced, contributing to a healthier market environment and providing a more stable foundation for margin recovery after several challenging years,”
Both ANN and TOPG shares started rallying. But not RSTON.
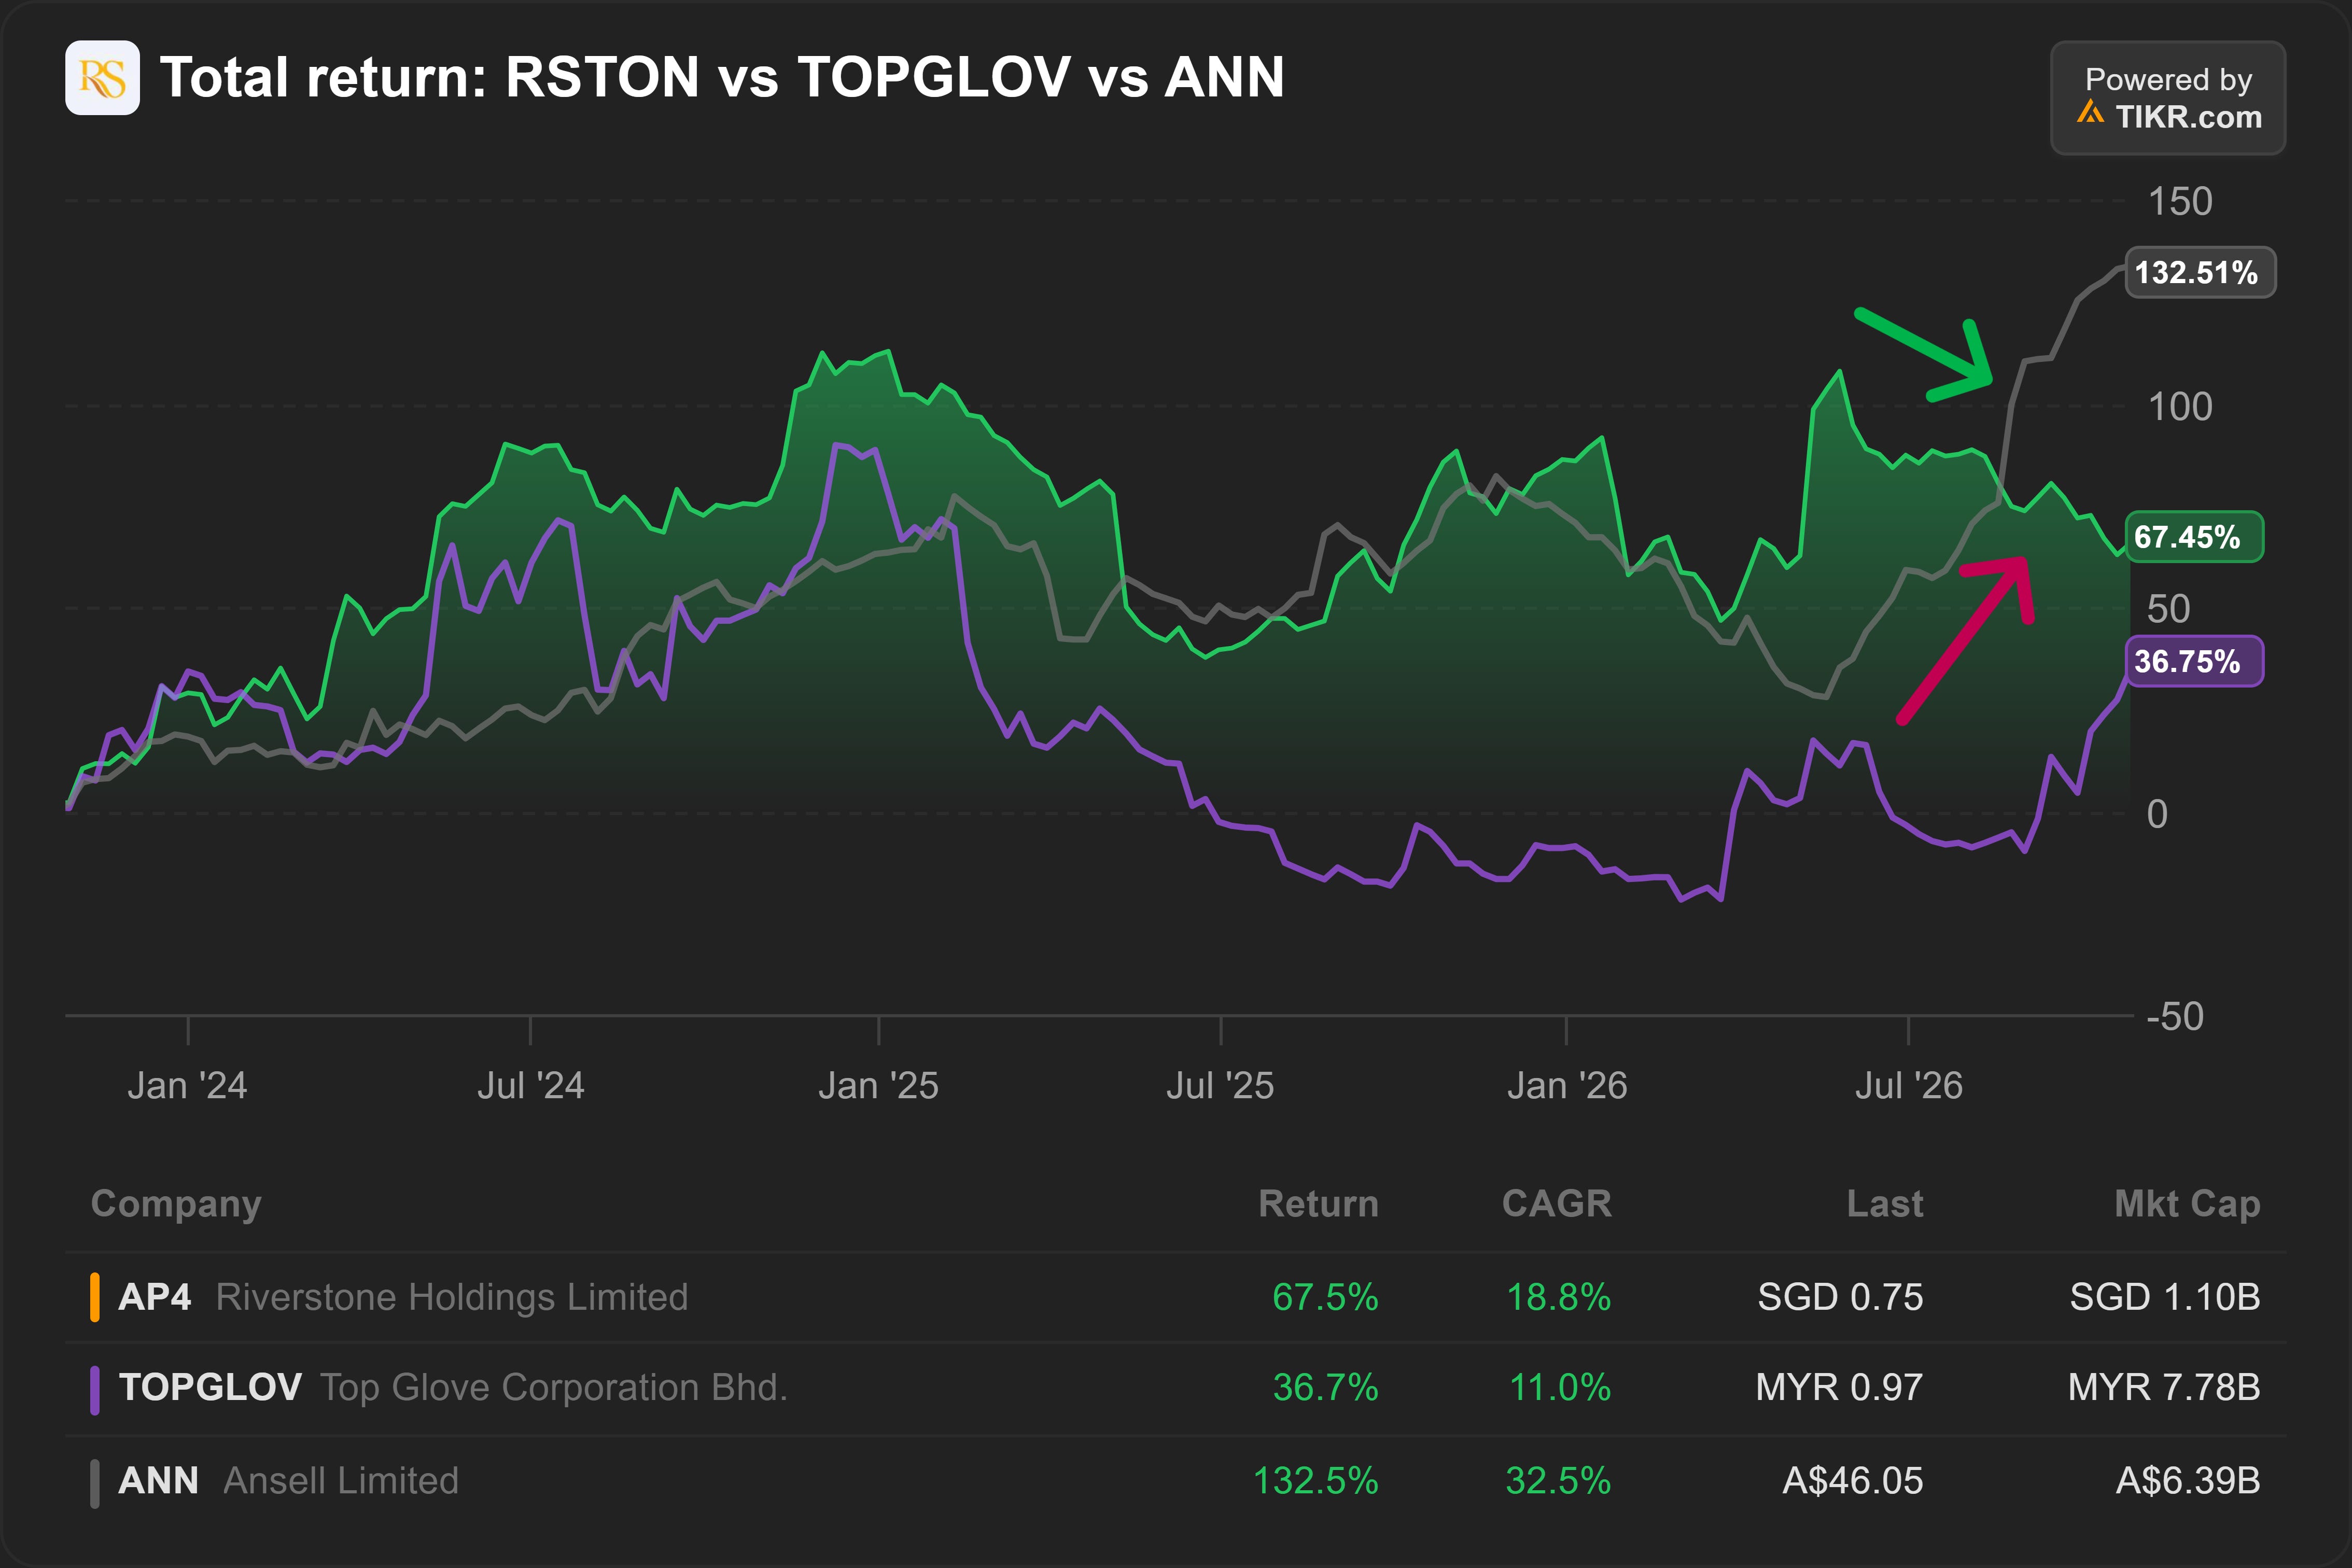
Why? RSTON’s business is not recovering?
Business is recovering.
In H1’26, management reported improvements in gross profit margin (GPM). GPM increased to 33% in H1’26, up from 30% prior year.
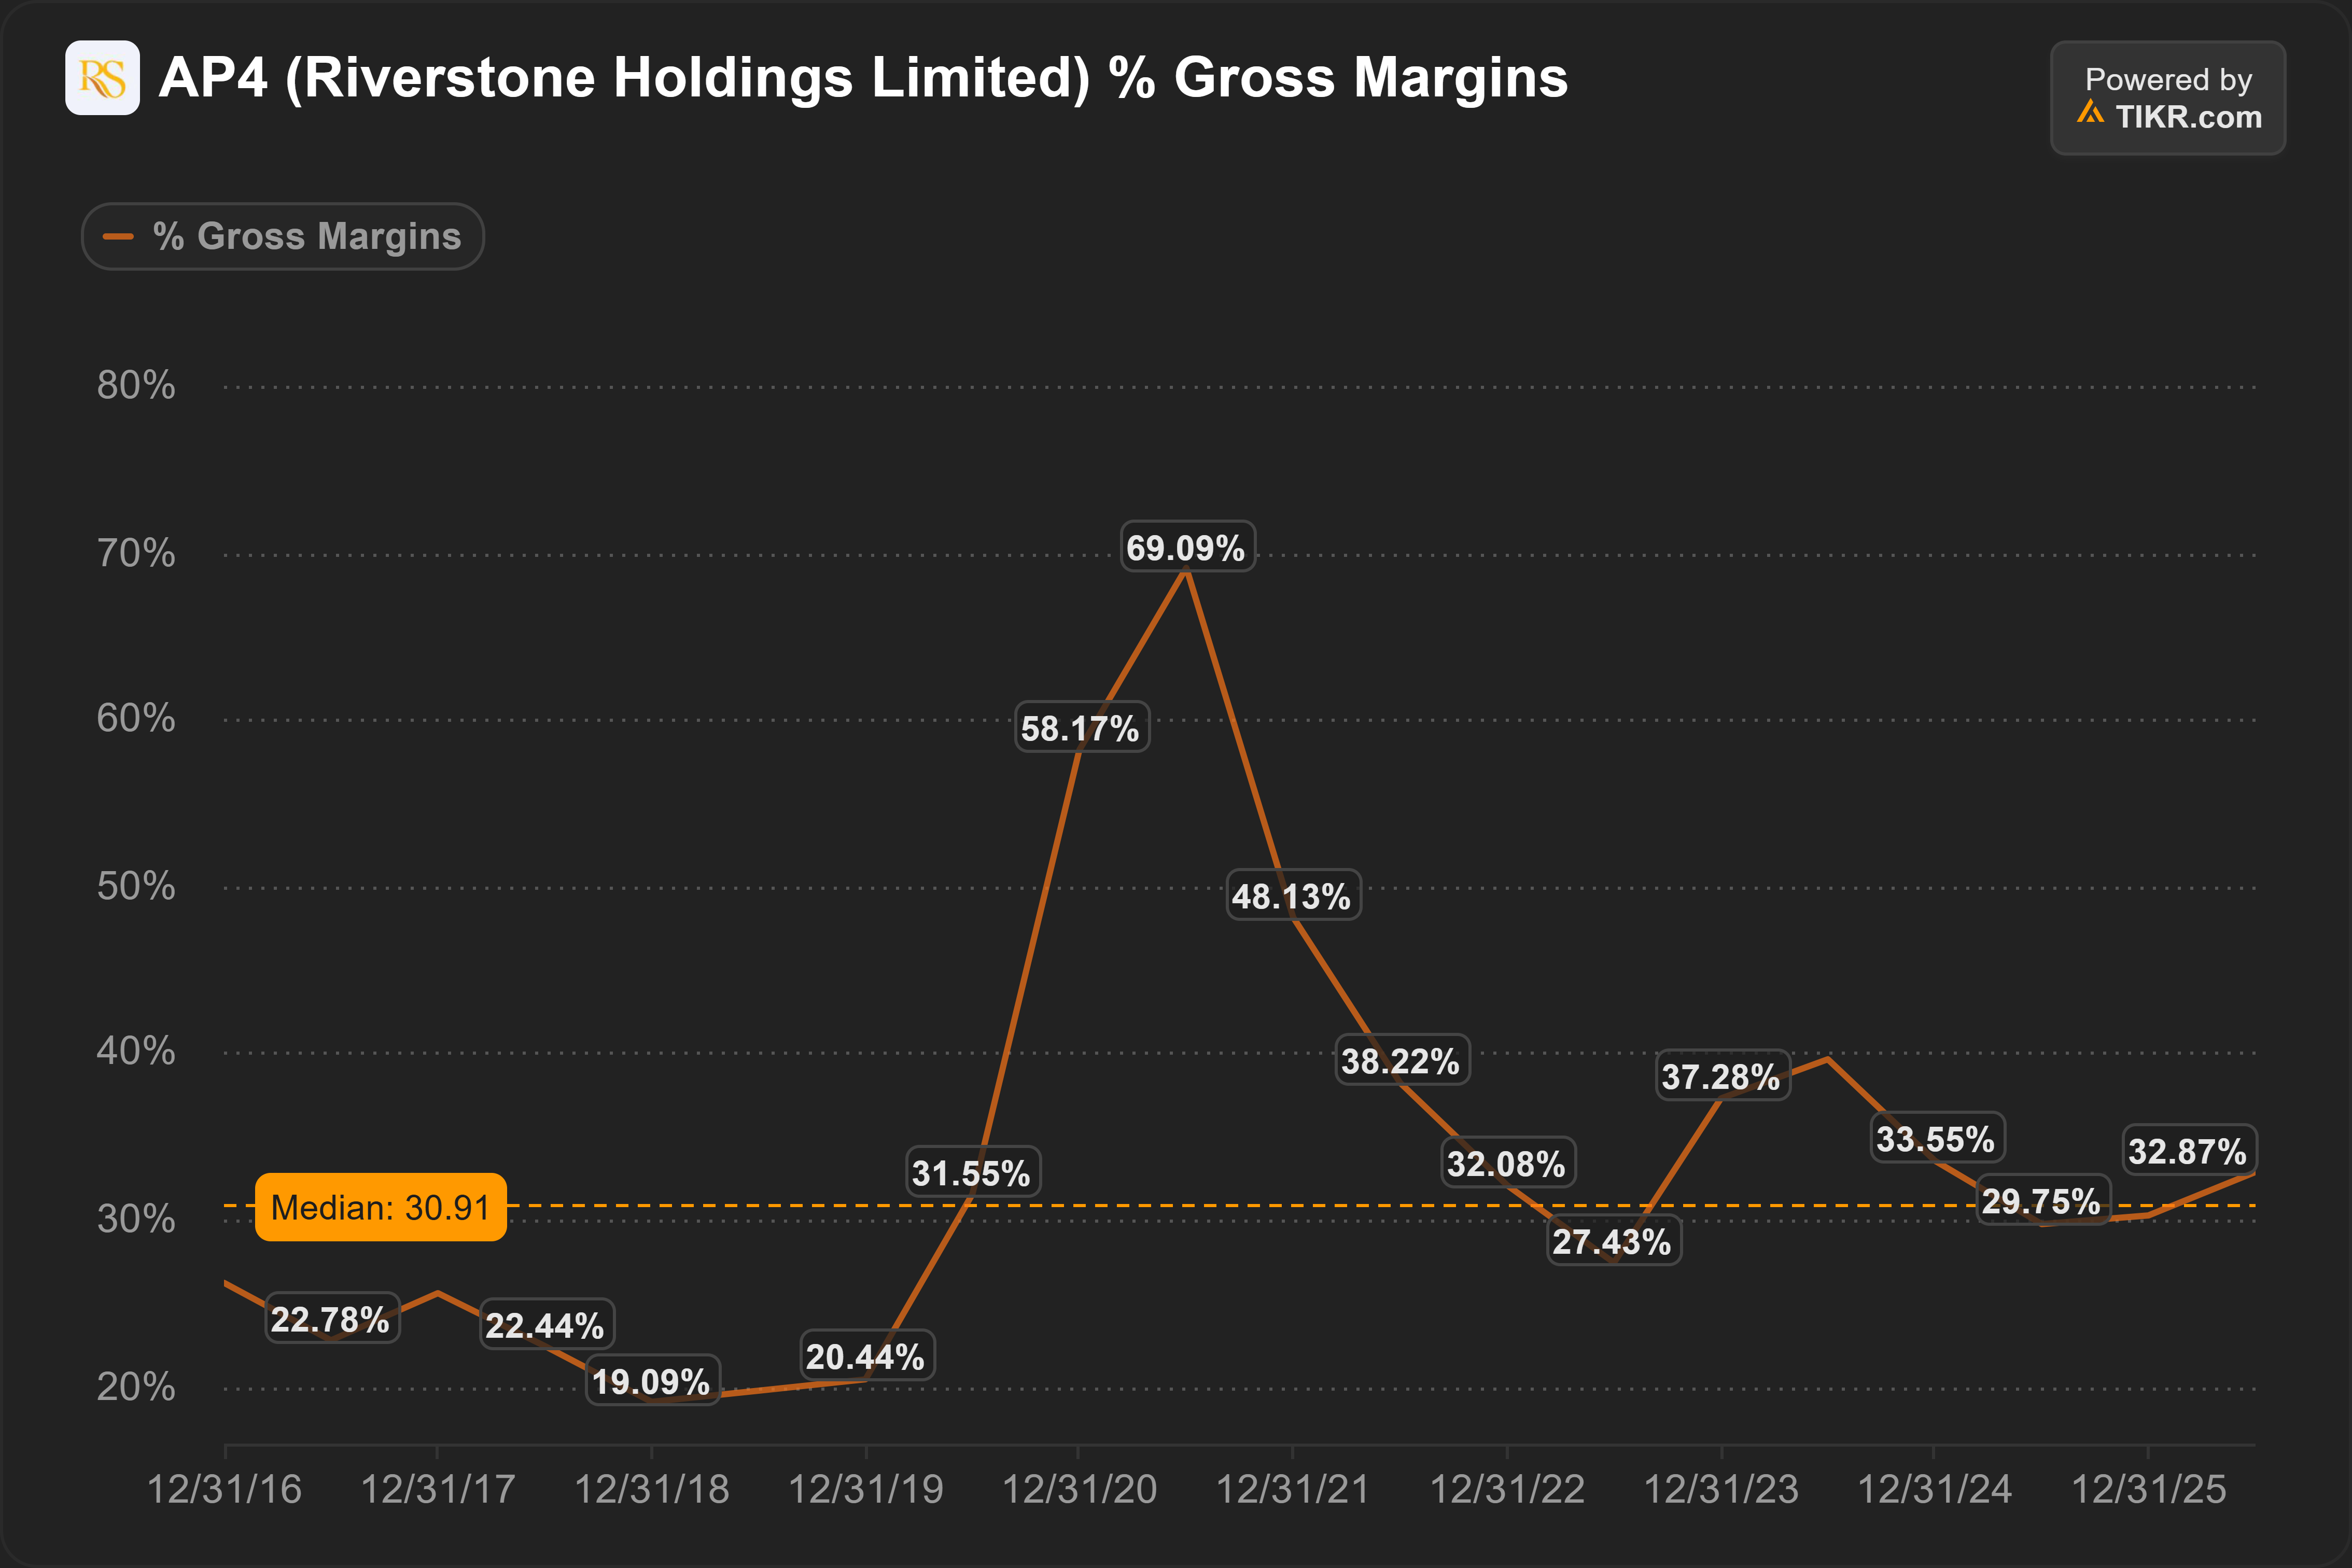
Management explained the improvement was mainly driven by higher average selling price (ASP). This suggests oversupply is starting to ease.
Compare management’s commentary to just 6 months ago.
In March 2026, management described cleanroom gloves ASP “remained resilient” while ASP for healthcare gloves “moderated” during 2025.6
We never take management’s words at face value. Do working capital trends support their commentary?
Yes.
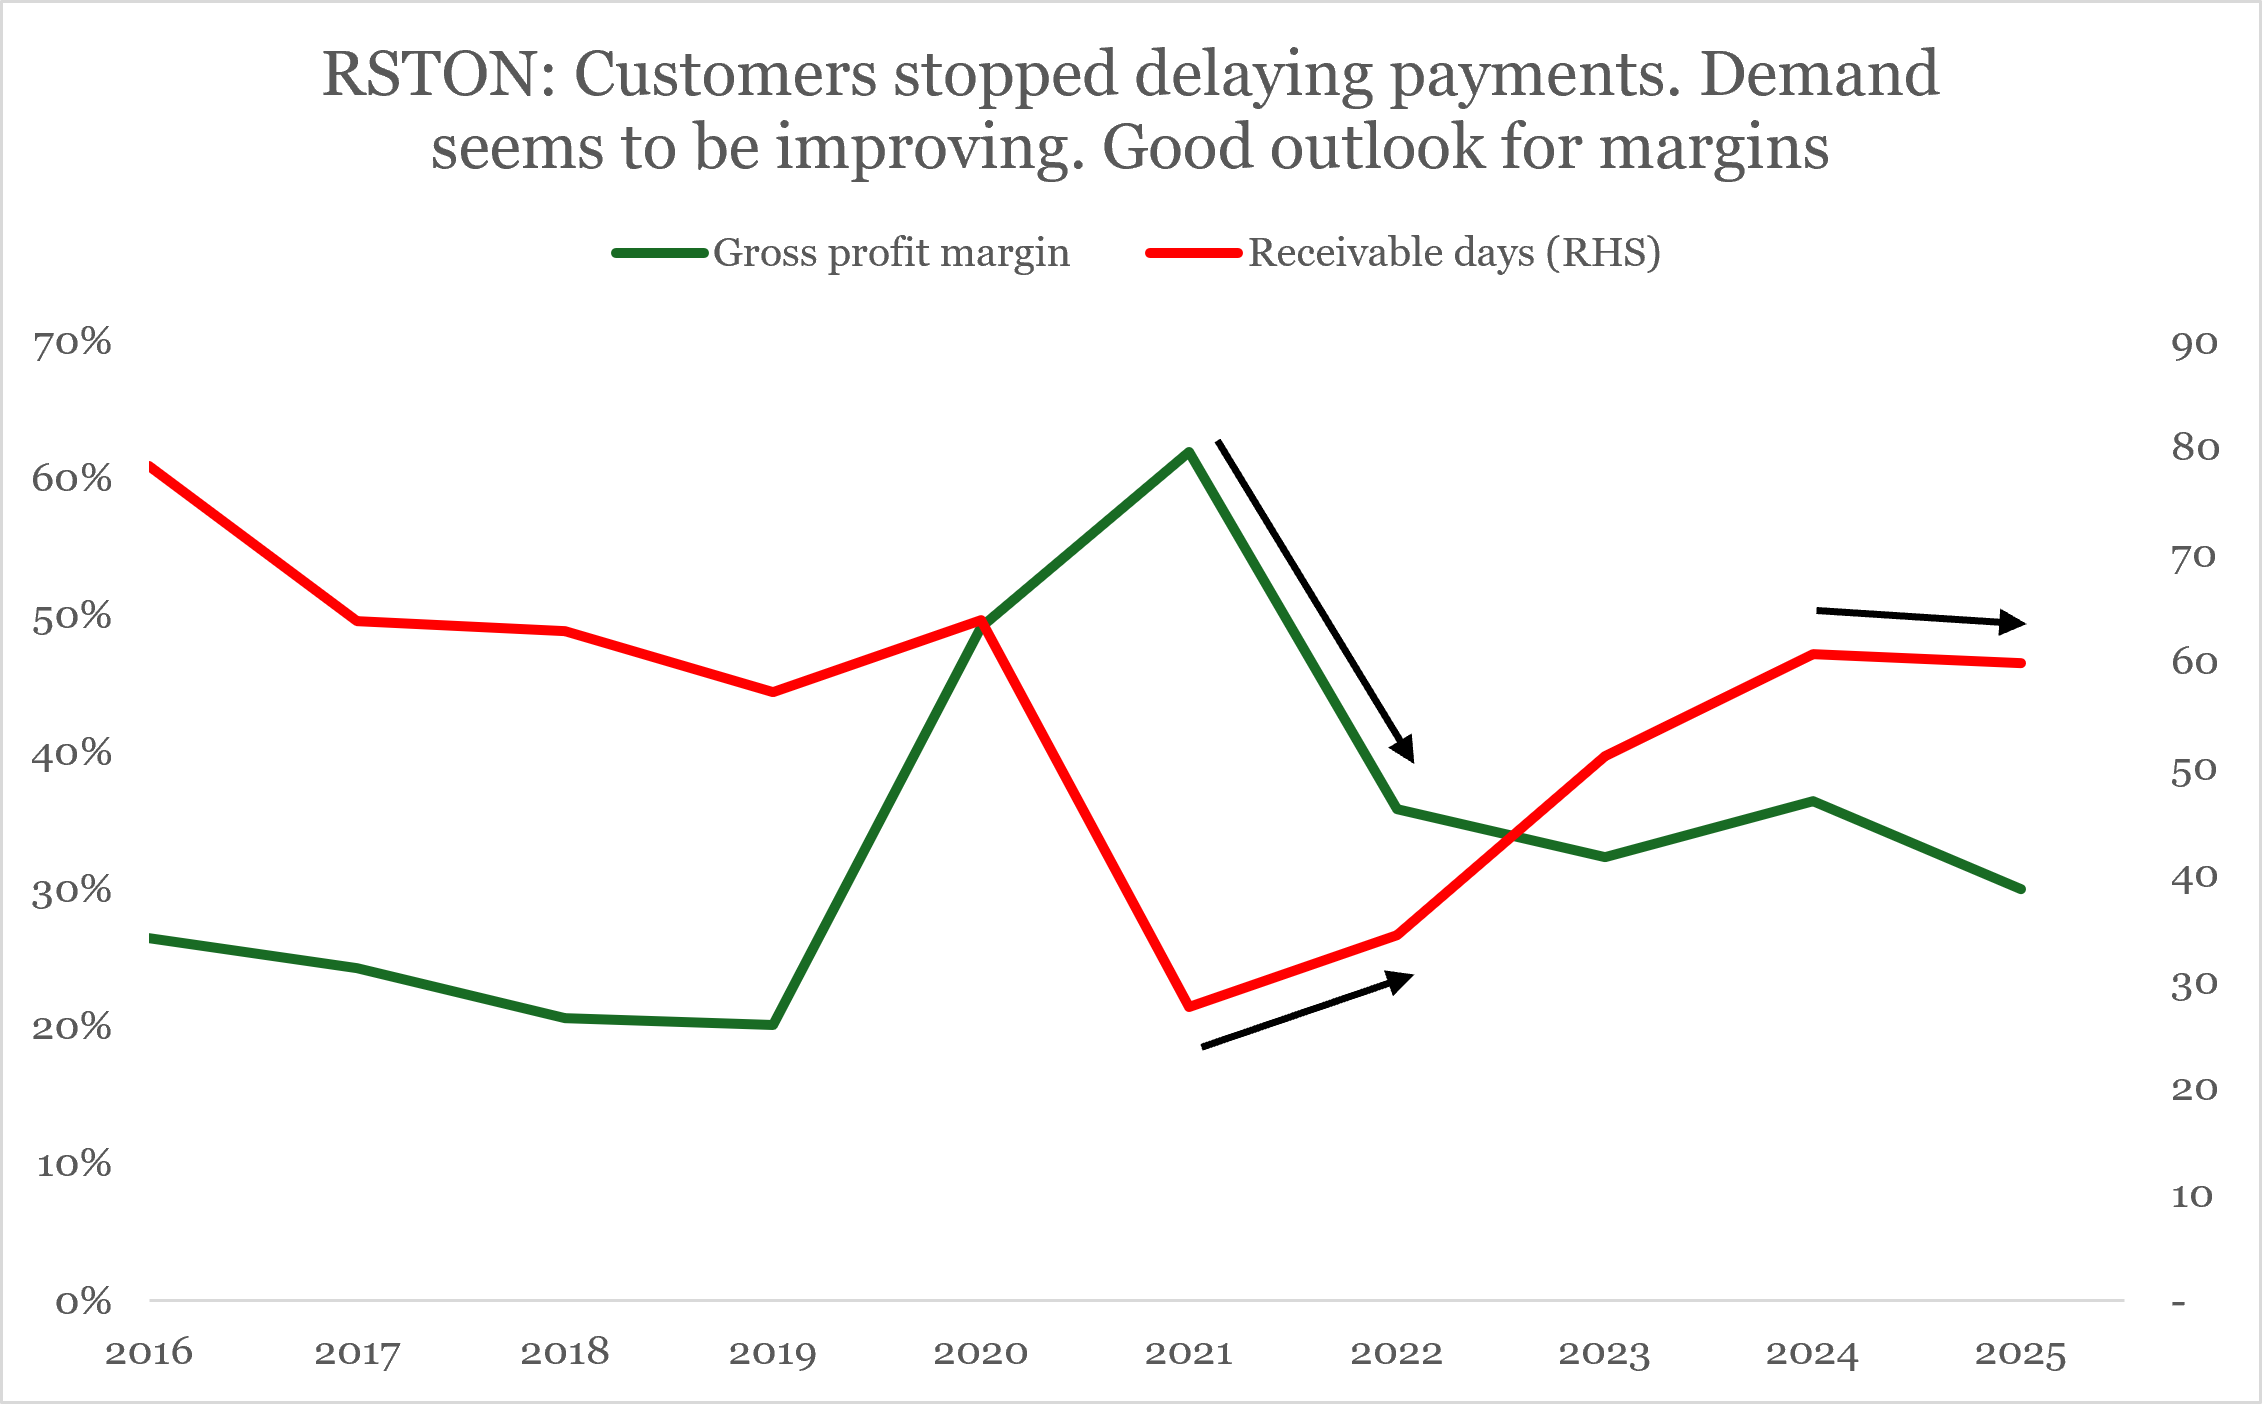
Customers stopped delaying payments. In 2026, receivable days have stabilised at 60 days, down slightly from 61 days during the prior year.
This suggests improving demand. Good for future margins.
How about inventory trends?