

[Shortlist] Raffles Medical Group Ltd (BSL; RFMD SP)
Last week, you highlighted a potential opportunity in RFMD. What’s your suggestion?
Shortlist RFMD.
Good business, temporary headwinds. Revenue and operating profits fell in H1’26, driven by the opening of more beds at a competing public hospital. However, the decline is unlikely to continue into H2’26. The public hospital is near full capacity.
Under-recognised growth. From Apr 2026, private healthcare insurance became more affordable. This should drive higher utilisation rate at private hospitals like RFMD, and accelerate revenue growth.
Attractive capital return. RFMD is also returning more capital to shareholders.
Liquidity?
5 Nov 2026
Share price: SGD 0.84
Market capitalisation: SGD 1,491 mn (USD 1,165 mn)
Enterprise value (EV): SGD 1,261 mn (USD 985 mn)
Average daily volume (ADV): SGD 2 mn (USD 2 mn)
NTM P/E: 24x
What does RFMD do?
RFMD is one of the largest private healthcare providers in Singapore. It holds ~ 22% market share in the private sector.1
2025 revenue of SGD 765 mn (+2% YoY):
40% Hospital (+6% YoY)
35% Healthcare (e.g. general practitioner clinics) (-4% YoY)
24% Insurance (+4% YoY)
1% Investments (-5% YoY)
Good business, temporary headwinds
Why is BSL share price falling?
Over the past 3 years, RFMD (or BSL) shares trailed ES3 (Singapore ETF). Revenue growth decelerated as COVID-19 revenue rolled off.
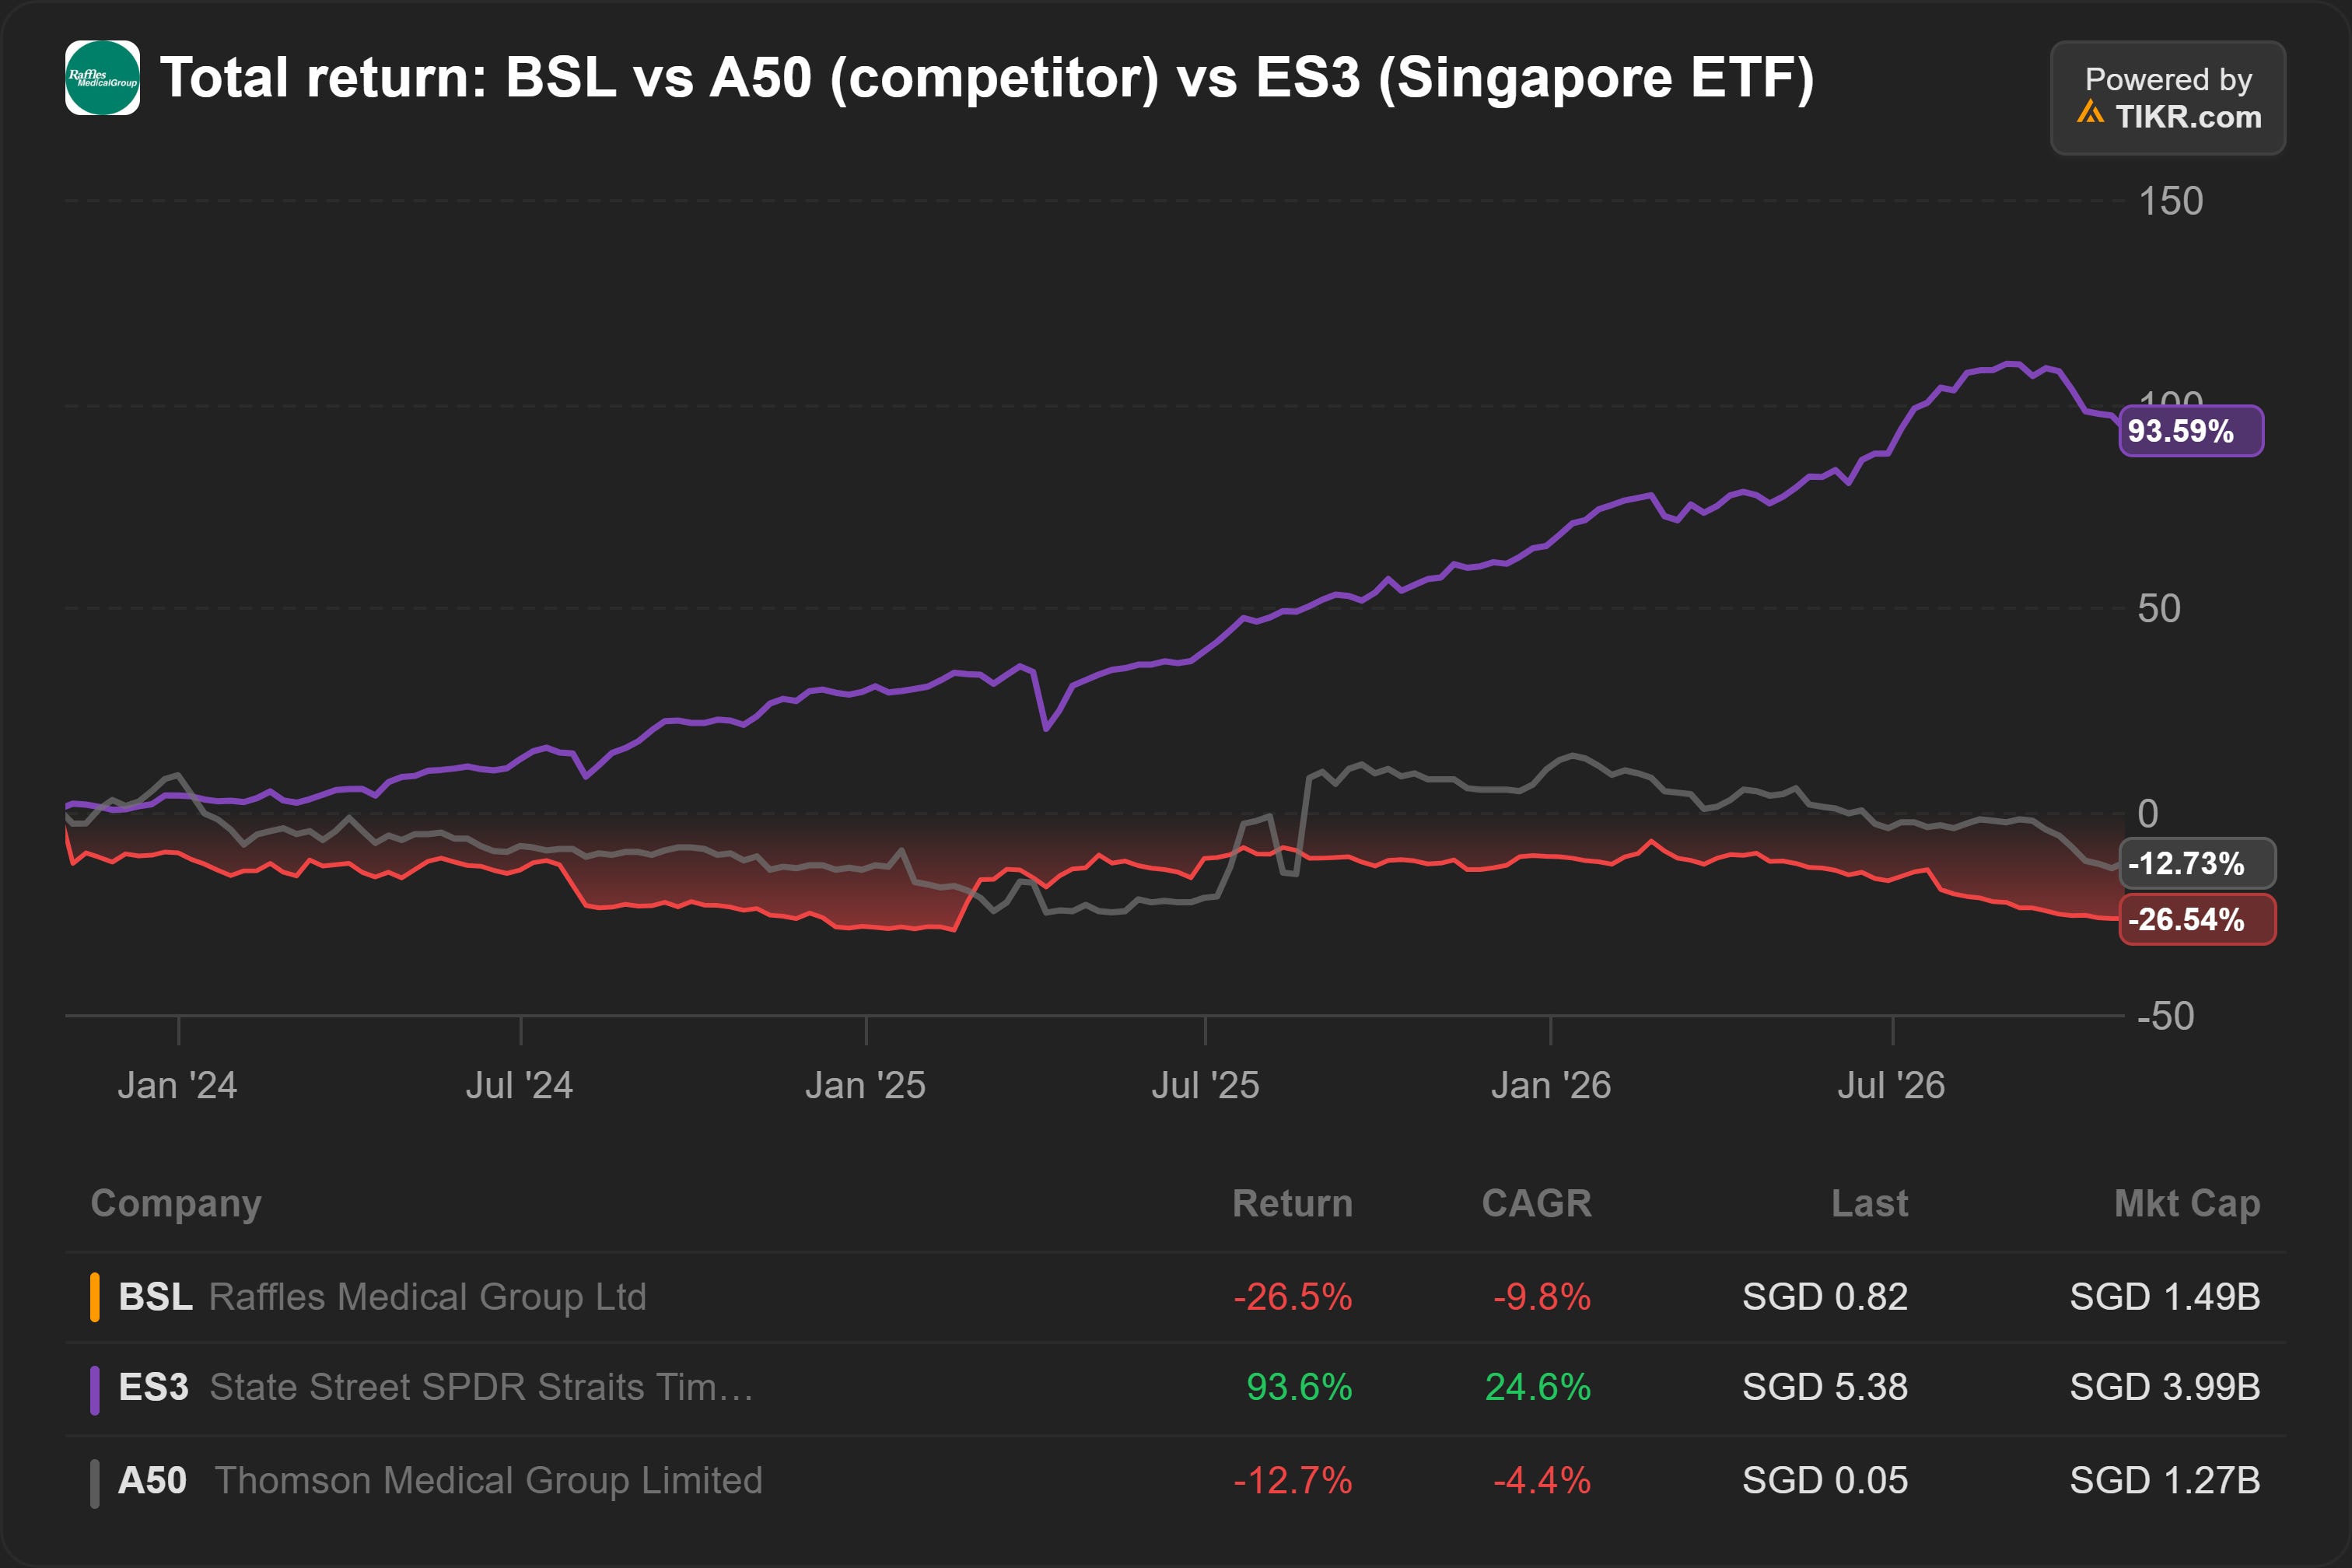
The sell-off accelerated in July 2026. RFMD reported Healthcare revenue declined -16% YoY in H1’26. Profits fell -37% YoY.
The main driver was lower occupancy at transitional care facilities (TCF). A new public hospital, Woodlands Hospital (WH), absorbed patient volume that used to be routed to RFMD’s TCF.
What will stop the share price from falling further?
According to UOBKH, a broker, “management noted that the bed occupancy at its Singapore TCF has already stabilised at a lower (yet still profitable) equilibrium level”2
In my previous email, I commented that if this is true, headline revenue and profits will return to growth soon.
I now have good data that supports this.
As far as I am aware, only one sell-side broker has looked at this data. Even AI failed to find this data for me: Daily Bed Occupancy Rate (BOR).
Daily BOR is the % of beds that are occupied. BOR is always less than 100% as it includes the special use of beds for paediatric, neonatal and delivery needs.
However, 85% is usually the threshold for comfort. BOR sustained above 85% may increase the risk of poor clinical outcomes due to the reduced access to hospital care.3