
"If you spend 13 minutes a year on economics, you’ve wasted 10 minutes."
Peter Lynch
New investors love using his quote to justify ignoring macroeconomic factors.
They are wrong.
Macroeconomic factors are important. Oil prices, interest rates, gold prices, etc. affect profits and share prices.
Long oil producers = long oil
Here’s the 3-year total return from investing in oil producers like ExxonMobil (green) and BP (purple).
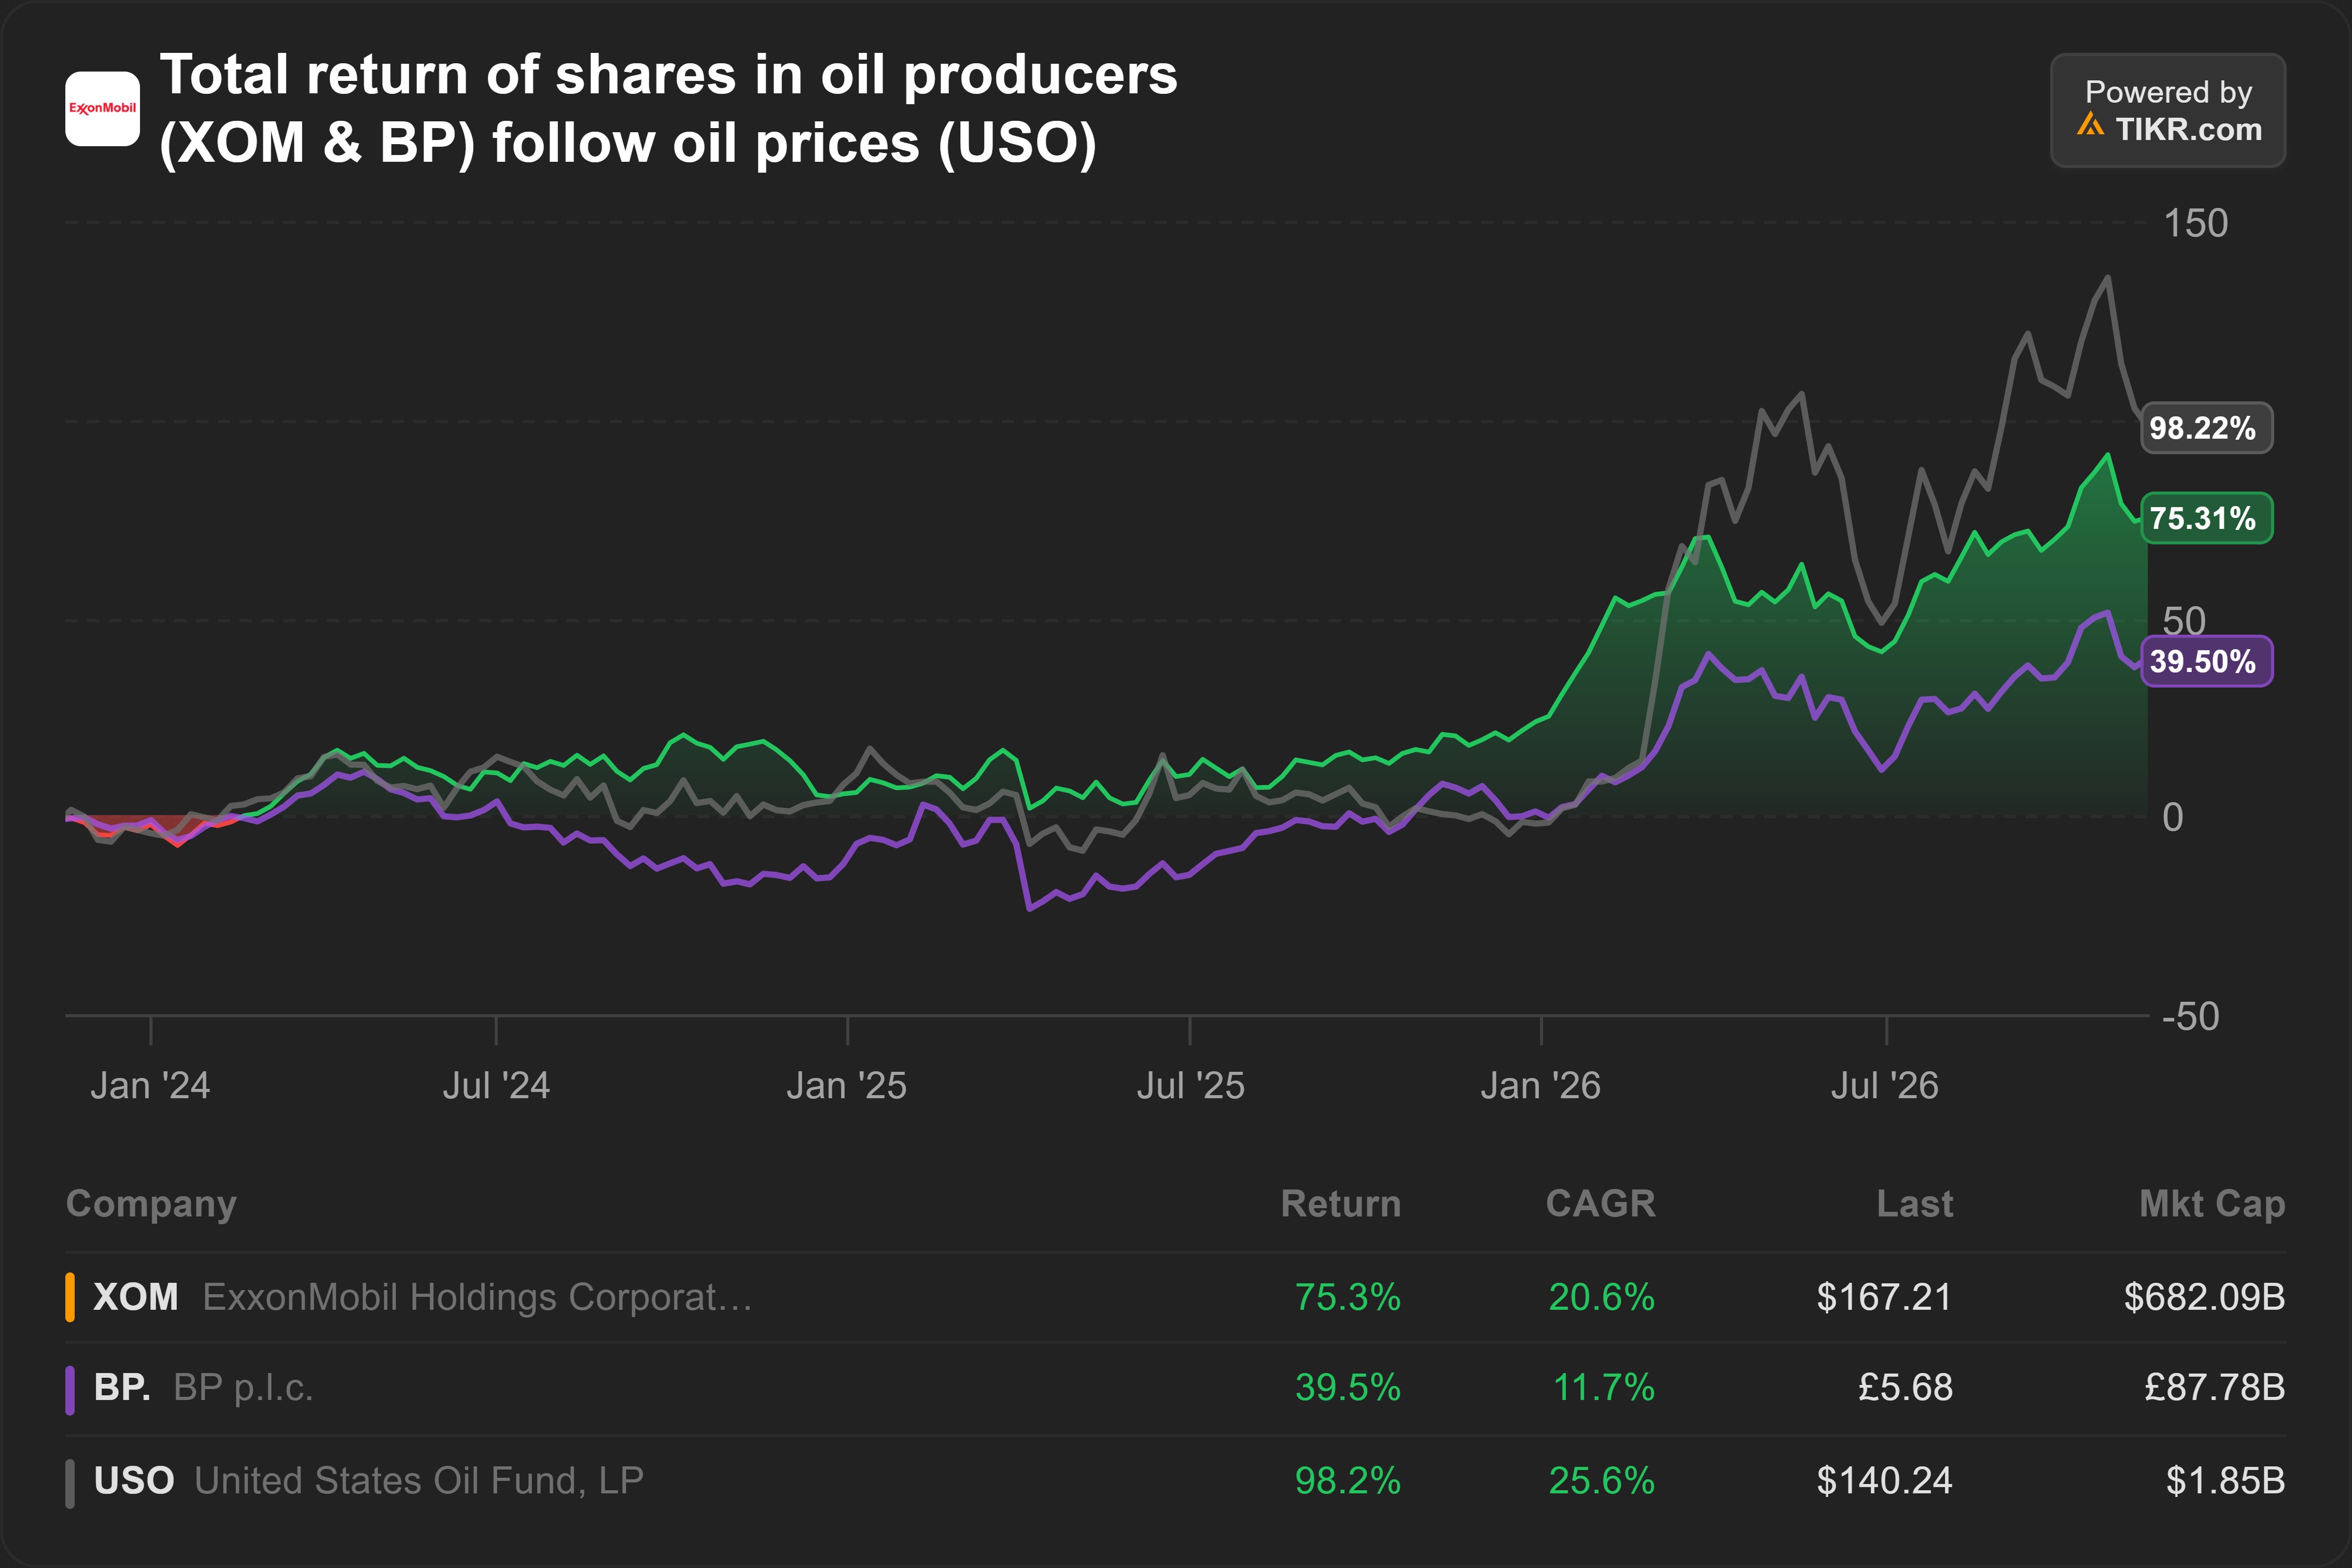
The grey line shows USO ETF. This tracks oil prices.
Shares in oil producers are highly correlated with oil prices. That makes sense. Higher oil prices mean higher profits for oil producers.
If you buy shares in oil producers (long oil producers), you are essentially betting on higher oil prices (long oil).
“Well, that much is obvious!”
Yes. Most people already know this. But what I am about to explain next, fewer people know.
Long airlines = short oil
When an equity guy is playing airlines, he’s making an embedded macro call on oil.
Scott Bessent
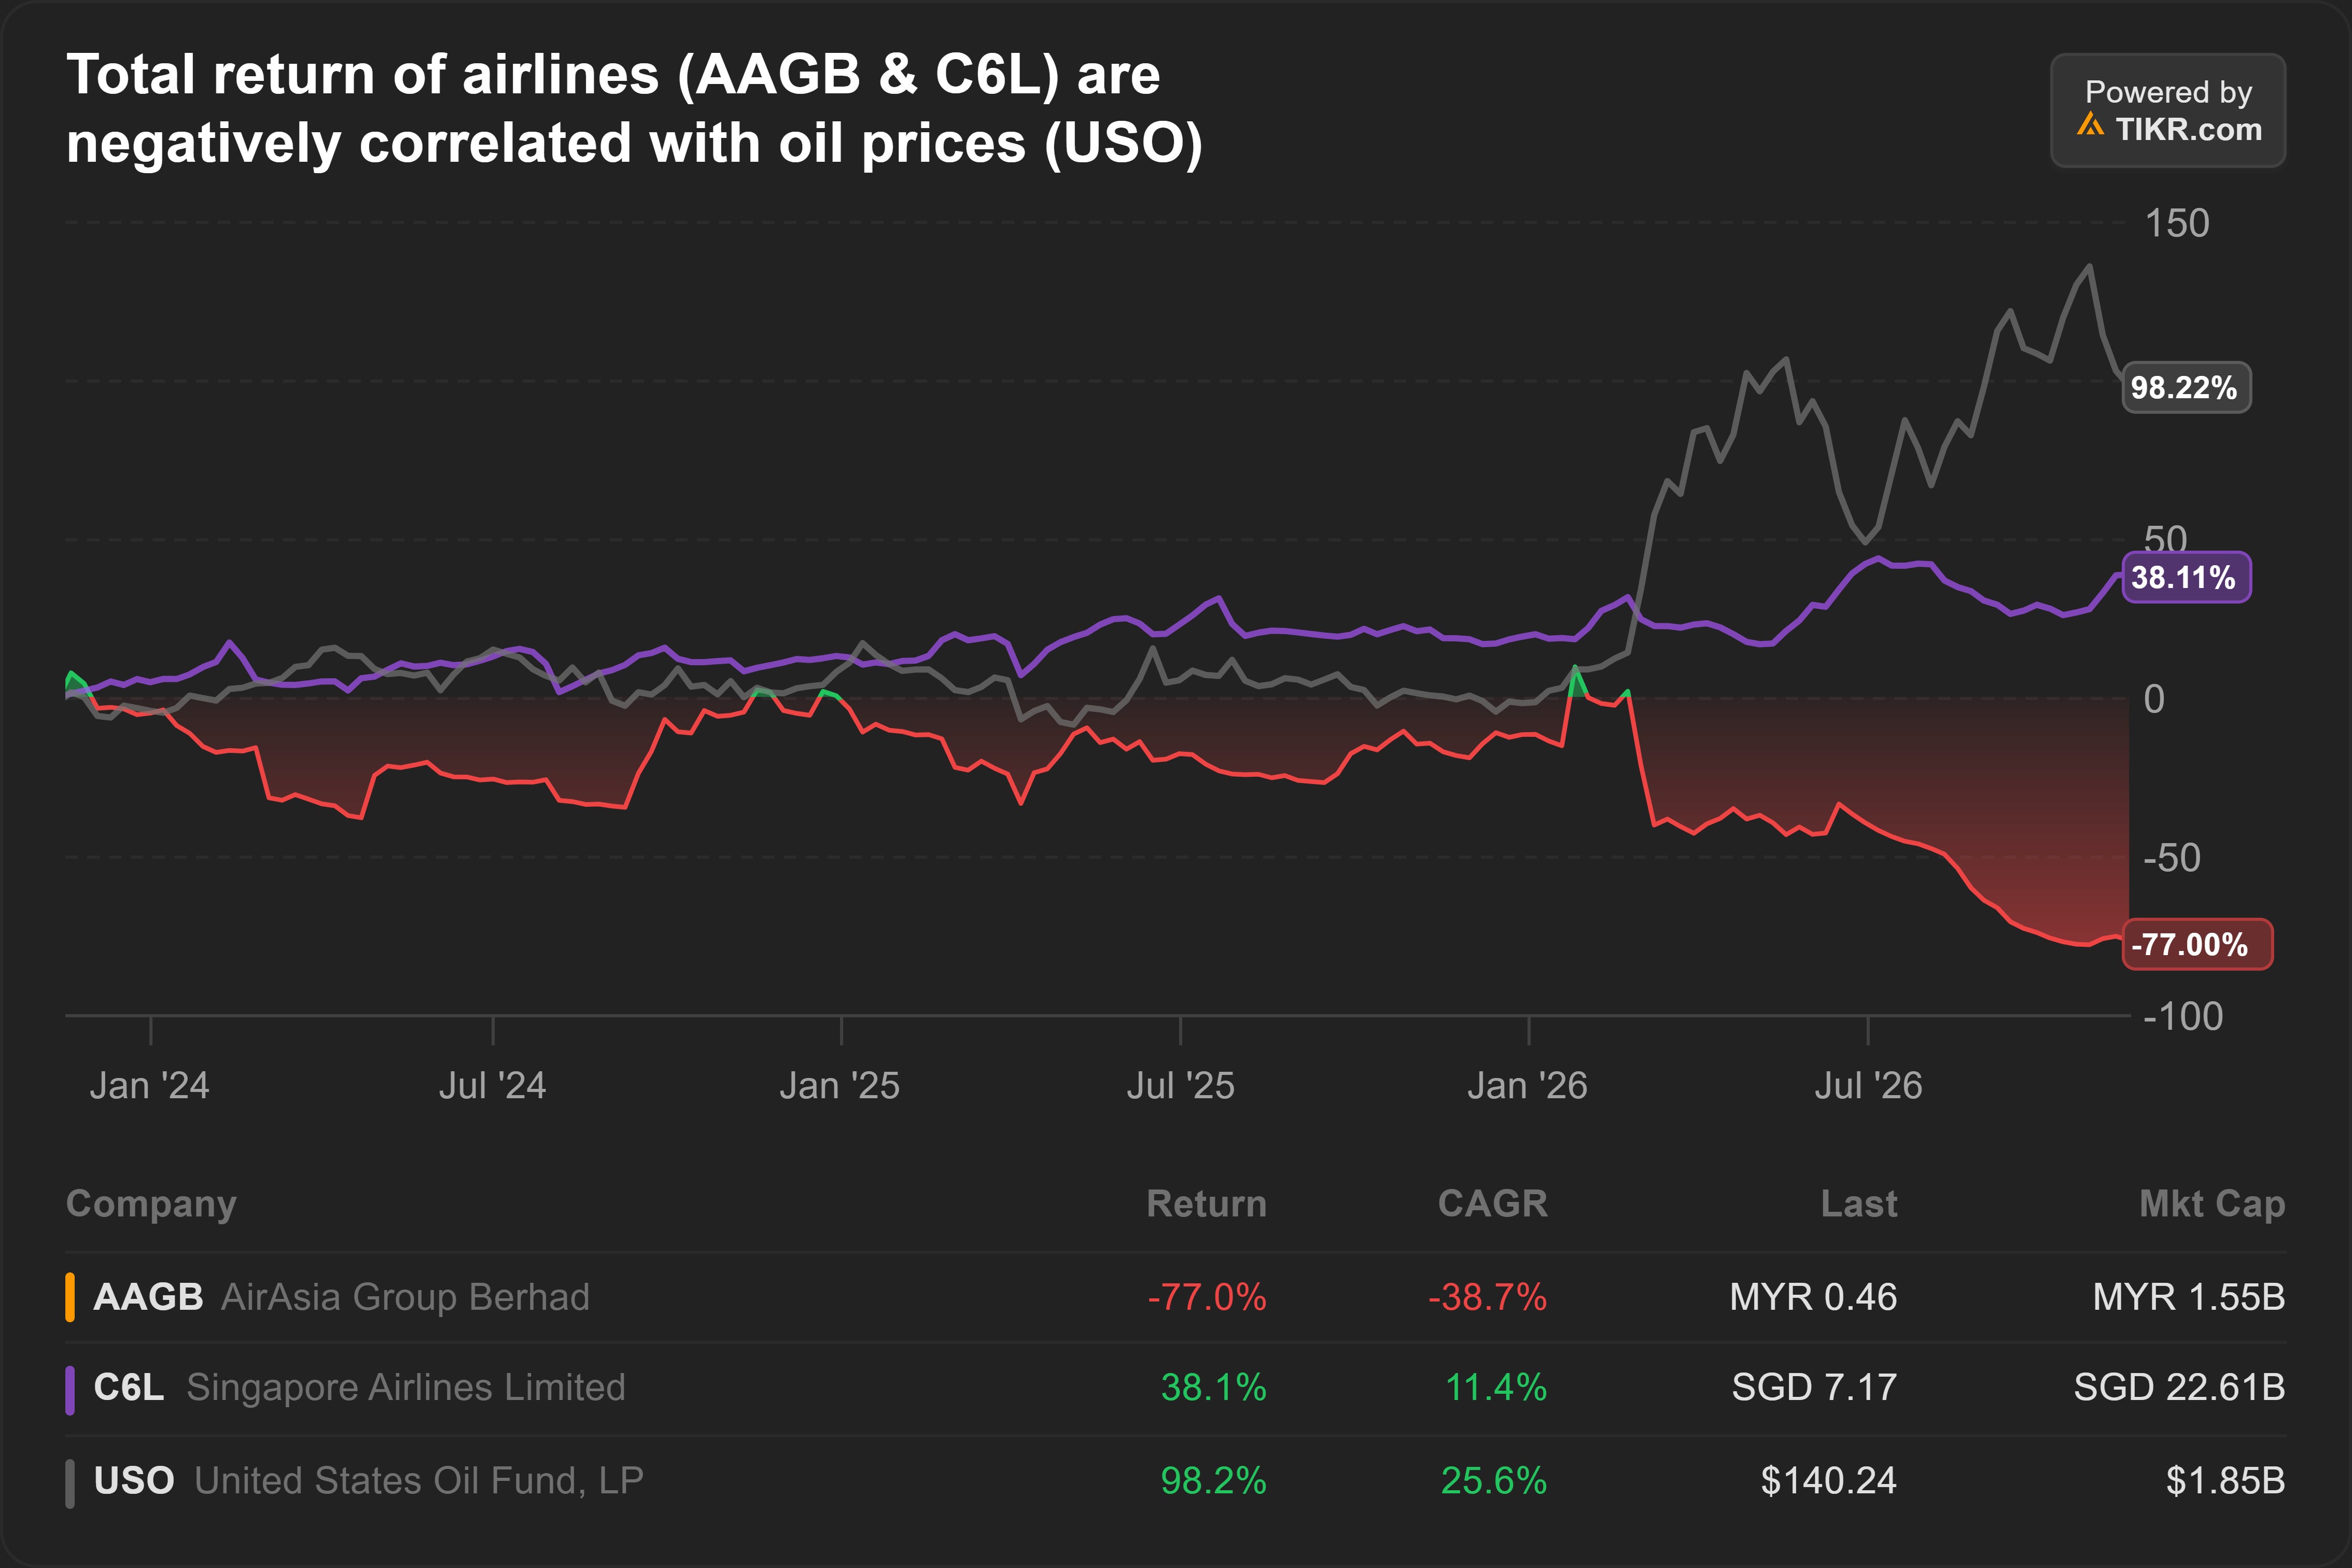
When oil prices surged in early 2026, shares in airlines like AirAsia (AAGB MK) (red) and Singapore Airlines (C6L; SIA SP) (purple) collapsed.
Jet fuel is typically one of an airline’s largest expenses, accounting for 25% to 30% of operating costs.1
As for why AirAsia is much more sensitive to oil prices, the short answers are: (a) it does not hedge jet fuel and (b) it is a budget airline.
Long banks = long interest rate
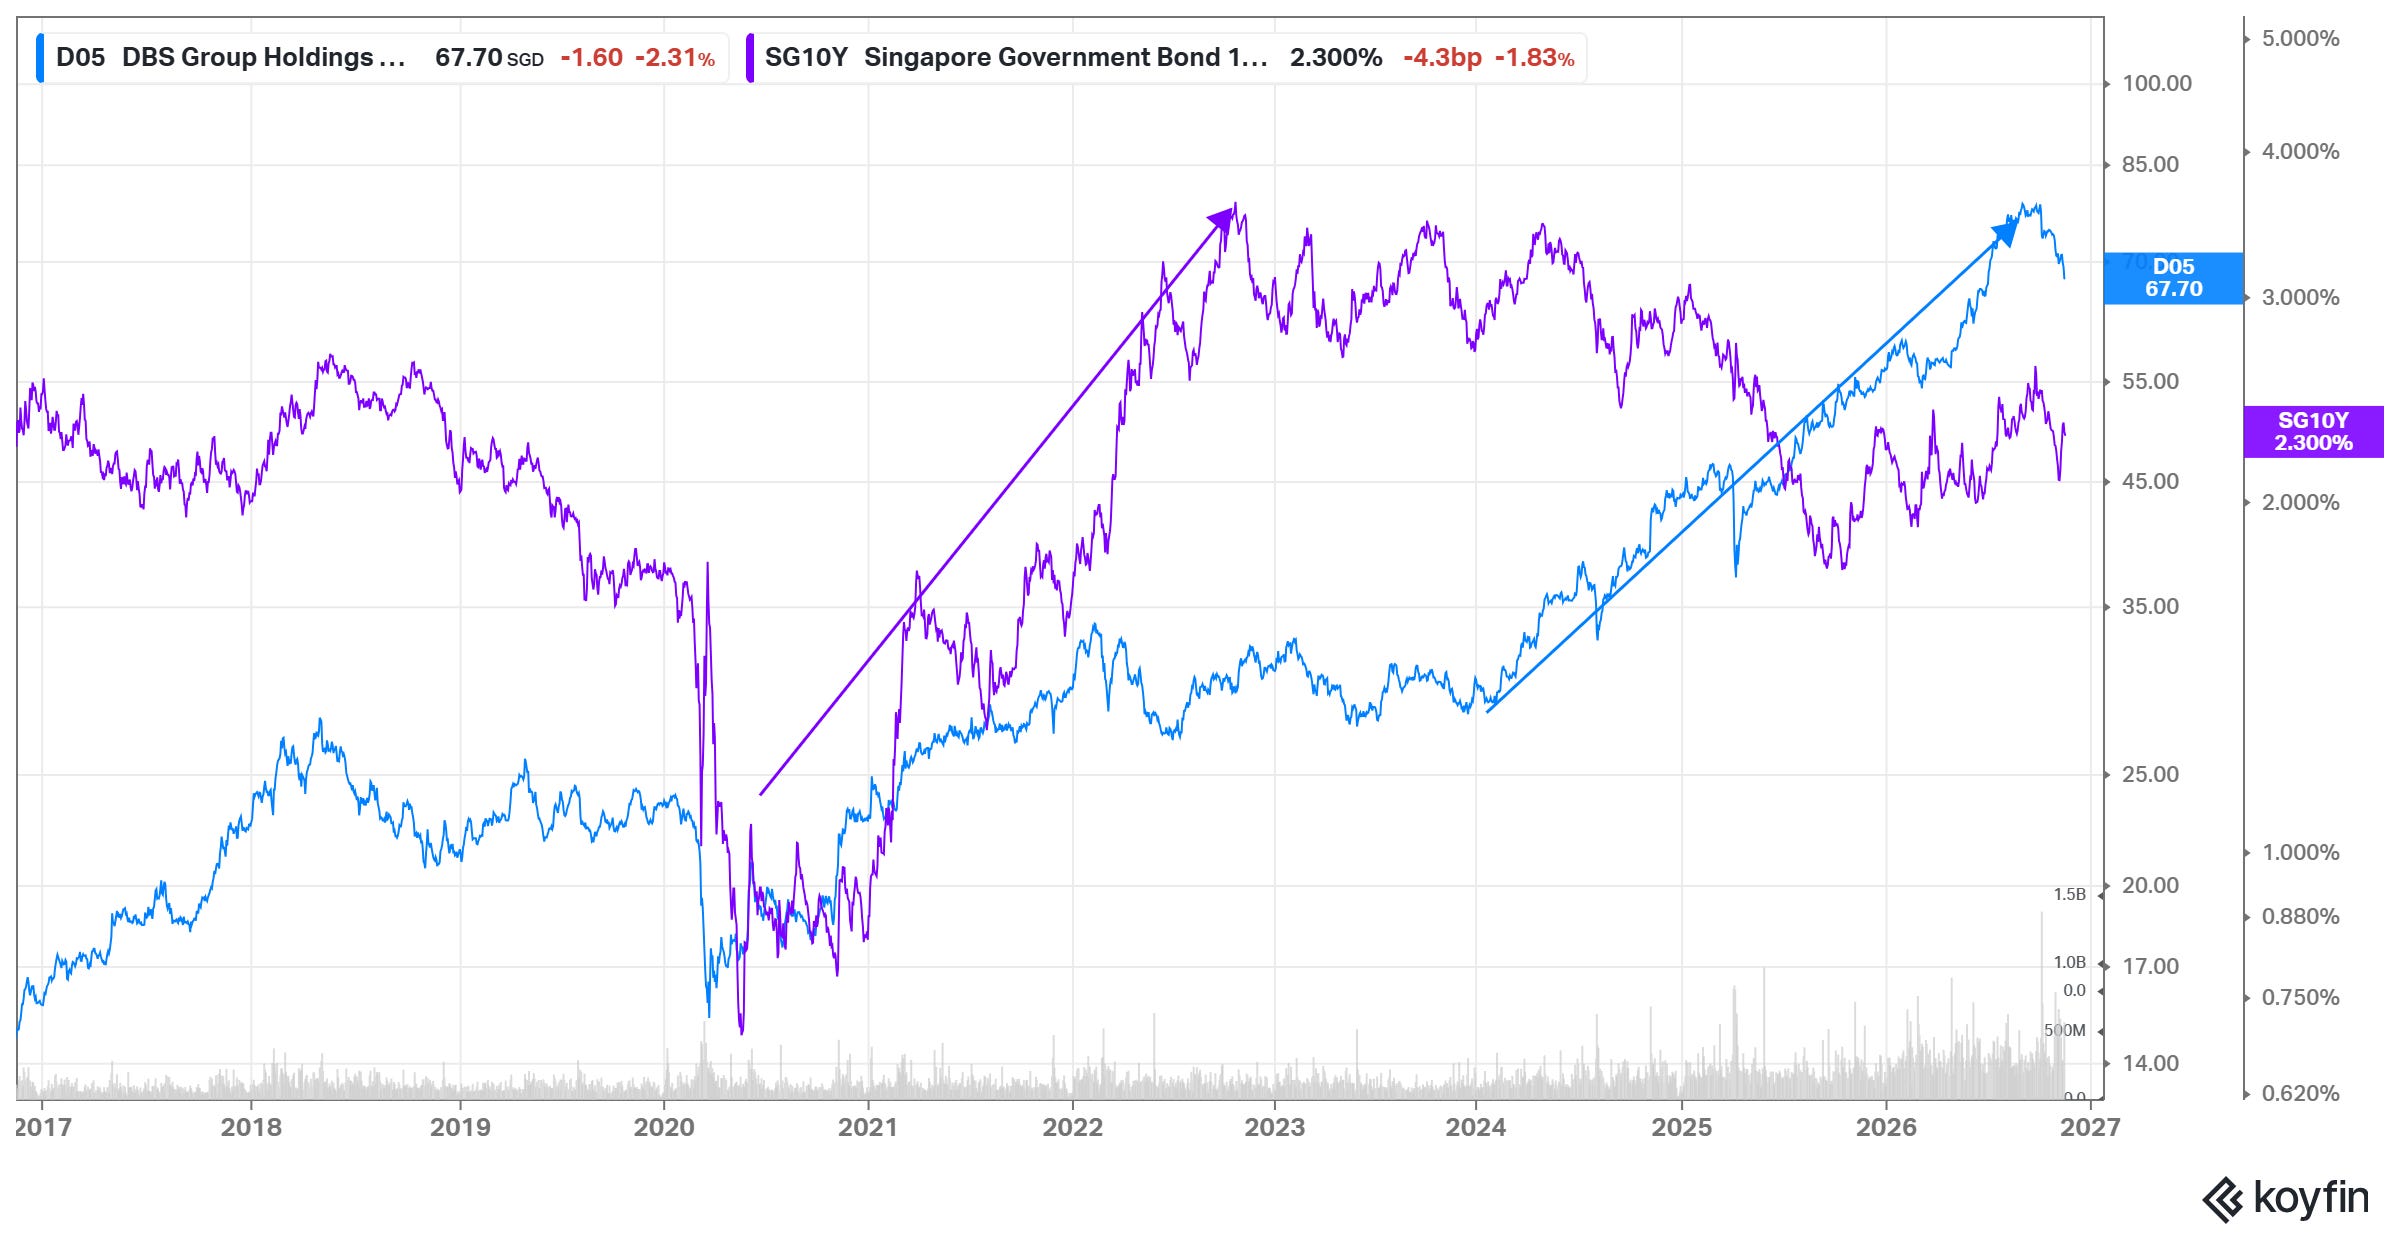
Generally, a bank like DBS (D05; DBS SP) (green) earns more profits after a period of sustained interest rate increases (purple).
Short explanation: Loans to customers typically reprice faster than deposits from customers.
Long REITs = short interest rate
All assets are sensitive to interest rates.
To oversimplify, when interest rates rise, bonds become more attractive. To maintain their attractiveness vs. bonds, the prices of other assets like stocks must fall.
Interest rates are to asset prices, you know, sort of like gravity is to the apple
Warren Buffett
Real estate investment trusts (REITs) are especially sensitive to interest rates.
Because real estate is generally stable but low-yielding, REITs typically carry a lot of debt to juice their return to shareholders. But higher debt also means higher sensitivity to interest rates.
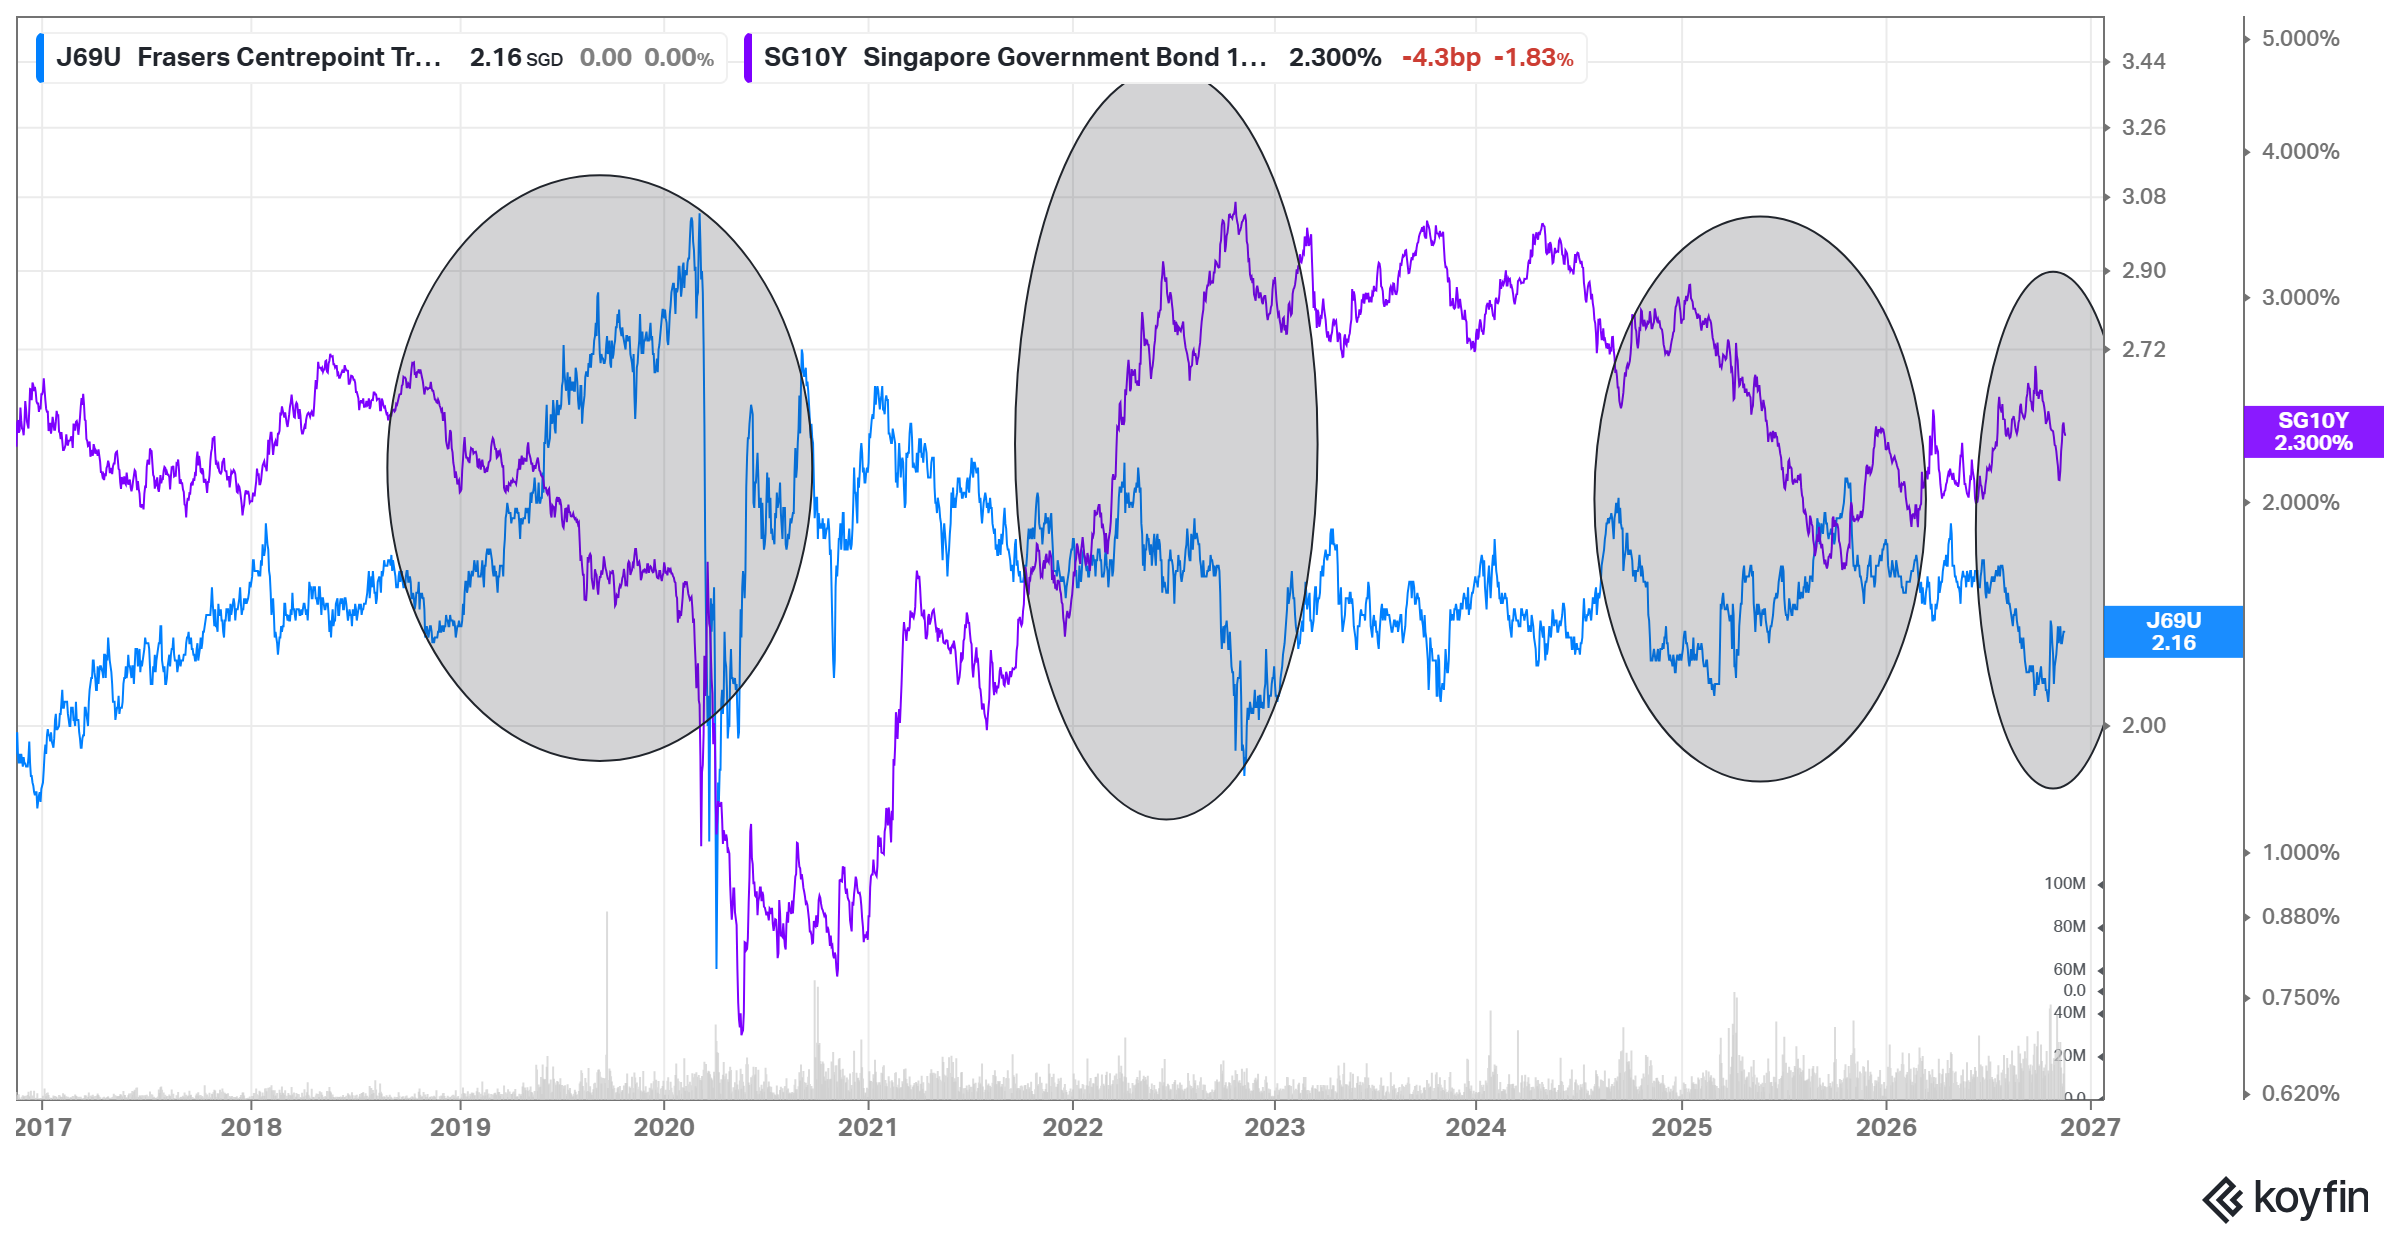
The price of Frasers Centrepoint Trust (J69U; FCT SP), a REIT in Singapore, moves inversely to the 10y government bond yield.
Long pawnbrokers = long gold
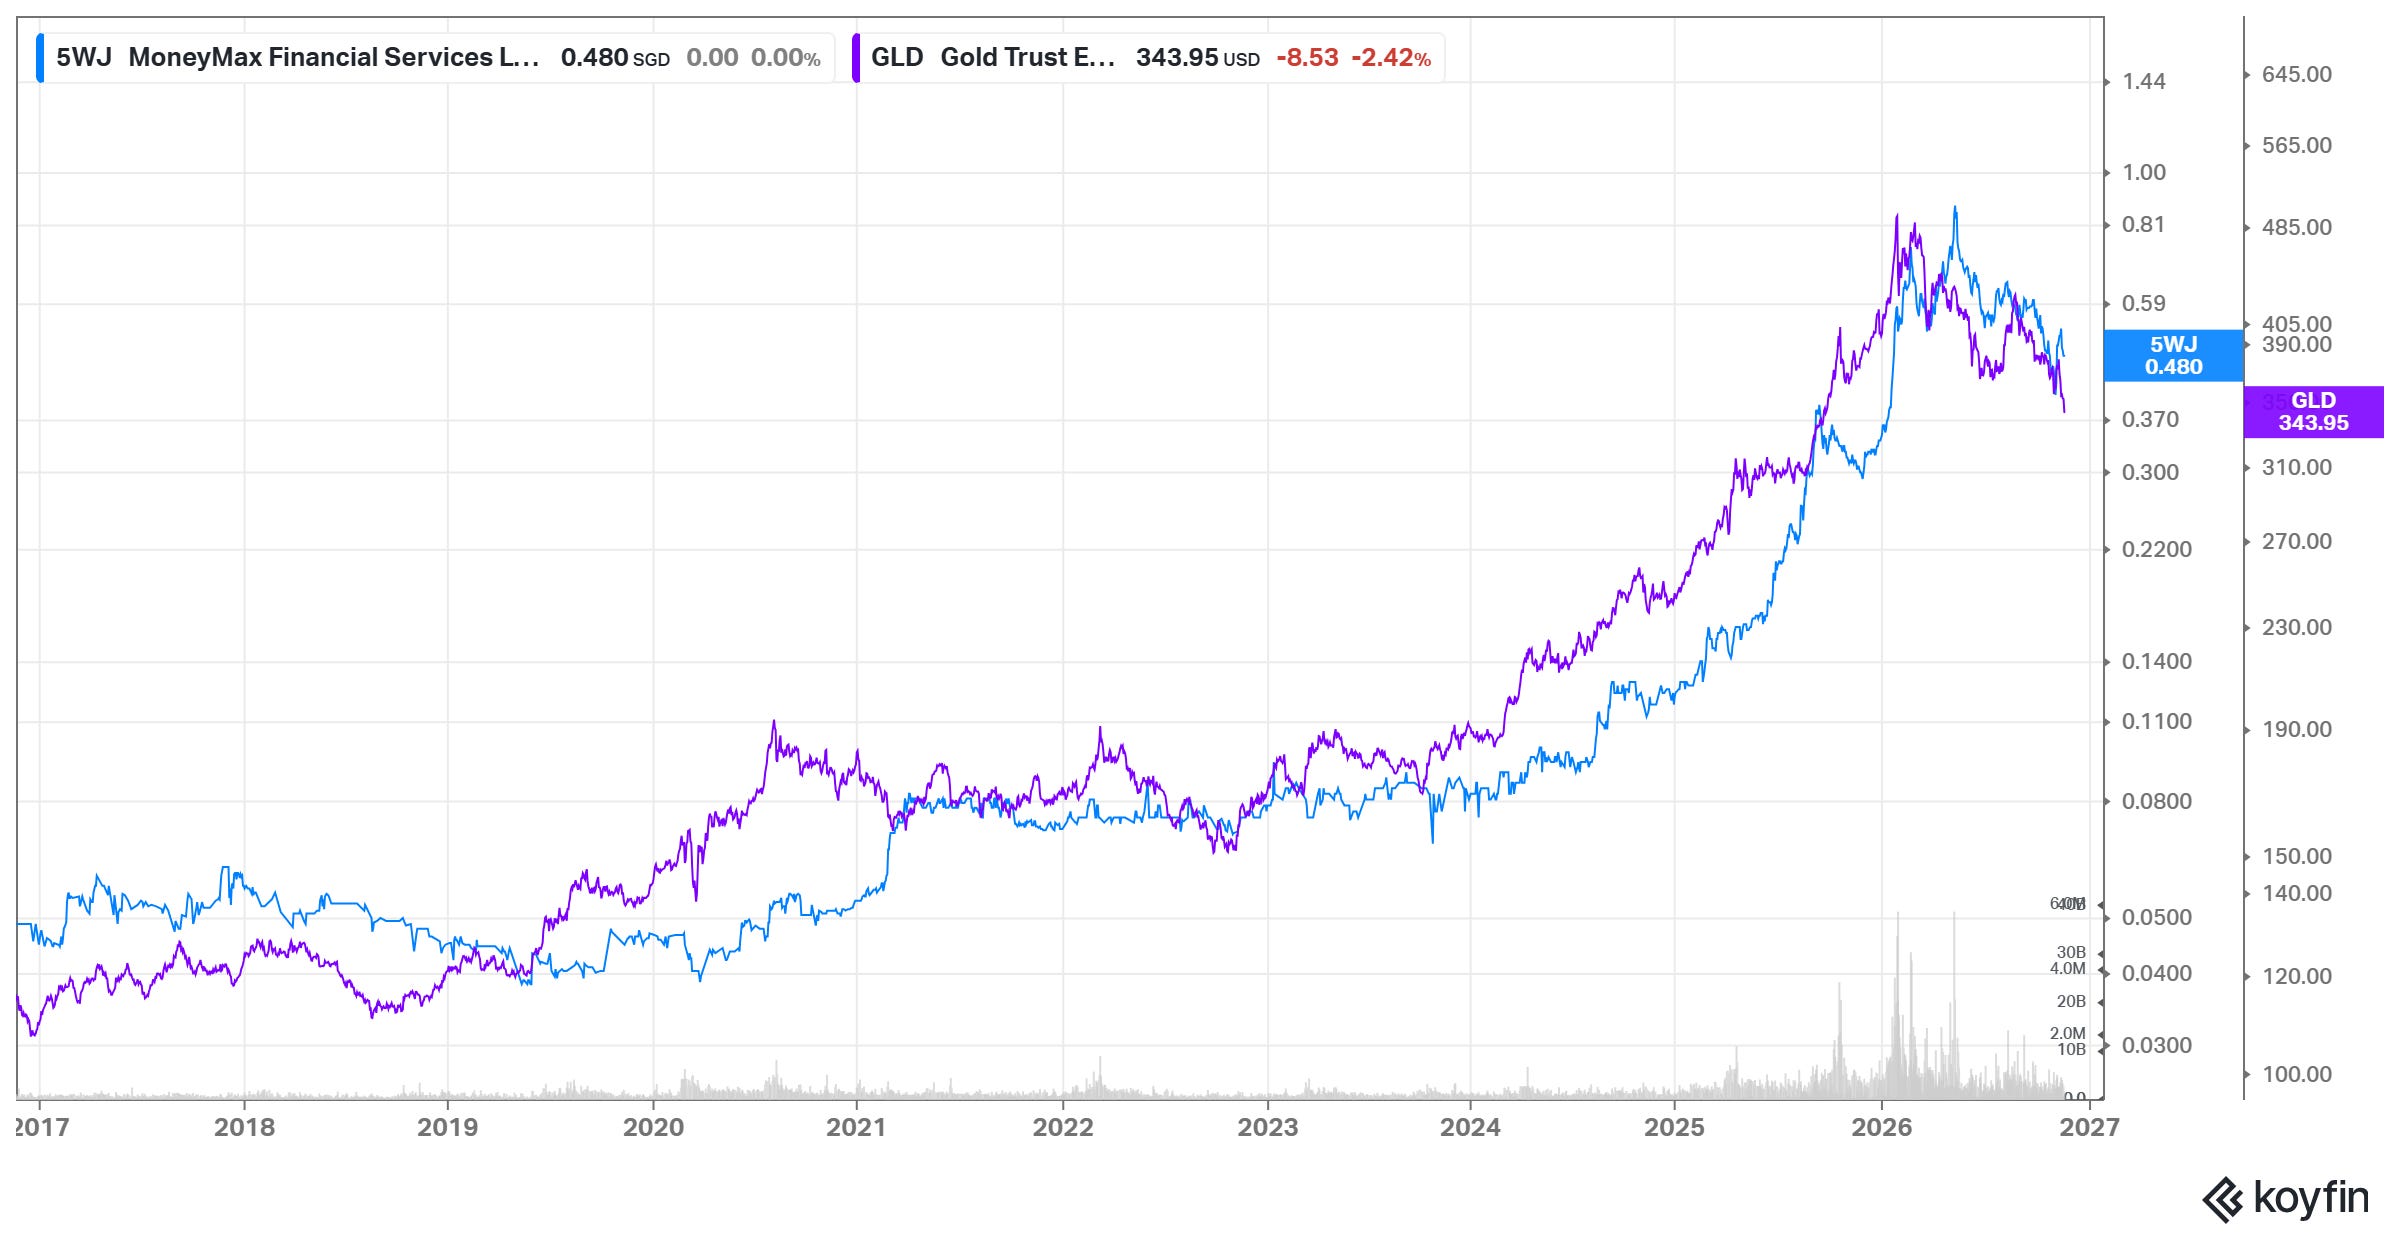
Rising gold prices are good for pawnbrokers because of (a) higher gold trading volume and margins and (b) higher loan value.
Does that mean we must forecast interest rates, gold prices and oil prices?
Not necessarily.
Peter Lynch is actually not wrong. He never said economics is not important. He said: