Small and mid-caps (SMIDs) are inefficient
On Sun 15 Nov 2026, I explained why I bought shares in Riverstone Holdings Limited (AP4; RSTON SP), a Singapore SMID.
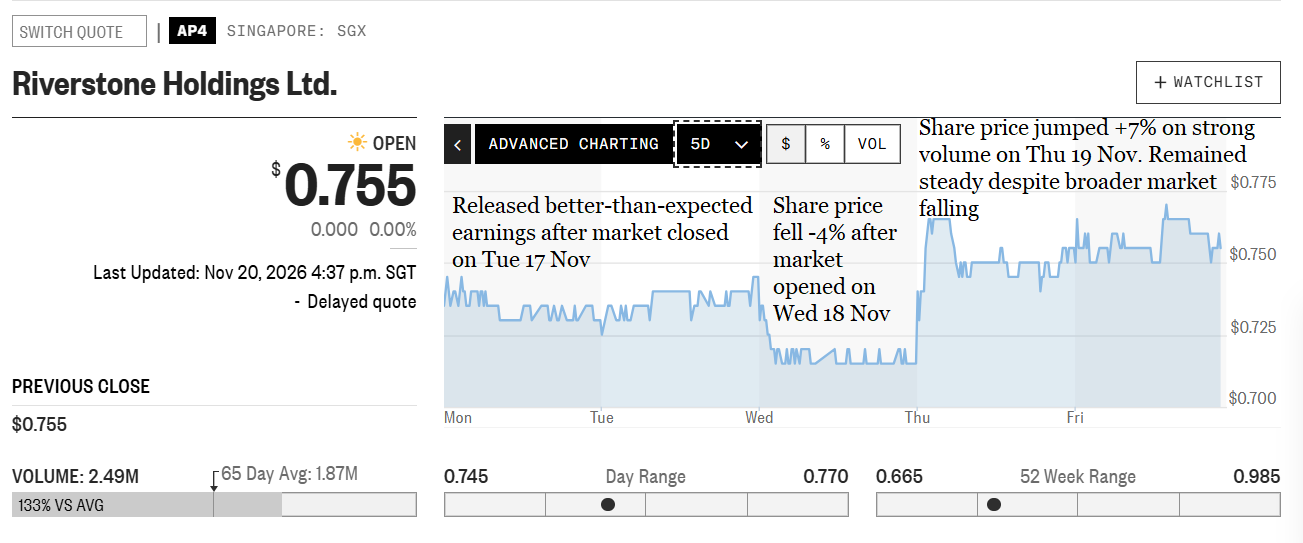
After market closed on Tue 17 Nov, RSTON reported better-than-expected earnings.
It took one whole day before investors reacted to the earnings!
My main business is not trading around quarterly earnings. When I wrote my thesis, I was looking at an investment horizon of 2 to 3 years.
I simply thought this is a good example of the higher inefficiencies in SMIDs.
But this doesn’t mean SMIDs will automatically outperform large caps.
It simply means there are more mispricing in SMIDs. The mispricing cut both ways.
I’ve seen SMIDs trumpeting guidance that’s clearly too optimistic. Quite many were full of red flags. Some were eventually exposed as frauds. The rest are still hidden.
It takes superior financial analysis, experience and hard work to spot and avoid these frauds.
It takes even more skill and more hard work to find opportunities with good odds like RSTON: working capital analysis, supply-demand analysis, industry read-throughs, channel checks, assessment of management quality and governance, etc.
This is the kind of alpha I can help generate.1
As regular readers know, I have started interviewing for my next equity analyst role. If you know a fund where my skills can add value, let me know.
After placing this ‘ad’ on my previous emails, I have received introductions and an interview. Thank you! Please keep them coming.
Screening for opportunities in Singapore SMIDs
The Fullerton / SGX Value-Up Singapore Equities Challenge is a virtual investment competition running from 7 Dec 2026 to 29 Jan 2027. The winner gets SGD 3,000 cash.
The goal is to achieve the highest total return by picking stocks from a list of SMIDs.
I will be joining for fun. I am not sponsored.
Honestly, 8 weeks is too short for fundamental stock-picking. Luck will play a bigger role in such a short period.
The organisers probably realise this too. The goal of the challenge is not so much on identifying the next Warren Buffett, but rather to ‘deepen understanding of Singapore’s equity markets’.
In that spirit, let us go through their list of SMID stocks. There’s only 96 stocks.2
Using the framework I described previously, I will spend ~ 15 minutes analysing each stock and decide whether it’s attractive enough for further investigation.
If you find yourself saying, “His analysis is too surface level! He doesn’t know this stock well enough!”, please remember this is intentional. This is just the initial stage of my idea generation process, not the full thesis stage.
Enough talk. Let’s begin!
This is just part 1 of the Singapore SMID series. To get the future parts, remember to subscribe.
If you want to skip to the list of SMIDs I found interesting, scroll to the bottom. You can also vote for the best idea.
Addvalue Technologies Ltd (A31)
Pass.
Trades at a high-growth valuation (~3.5% FCFF yield).
But decline in advance payments from customers suggest slowing growth.
AEM Holdings Ltd. (AWX)
Pass.
We’re near or have already passed the peak of the semiconductor cycle.
Very heavy capitalisation of intangibles. Without this, AEM would have shown losses in the past two years
Why is customers taking longer and longer to pay? In LTM, days receivable reached 126 days. How collectible?
Why inventory days so high? Reached 405 days in 2024, but has since decreased to 261 days in LTM.
Extremely high customer concentration. ~ 70% of revenue from just two customers.
Investors typically underestimate the risks from customer concentration. Look at Topsports (6110 HK), GTAT (defunct) and Imagination Technologies (sold)
Aztech Global Ltd. (8AZ)
Pass
Looks cheap: ~ 50% free cash flow yield on enterprise value (FCFF yield)
But this seems to be pricing in for the risk from extreme customer concentration:
Gemini estimates over 80% of total revenue tied to its top two customers and more than 50% derived from a single anchor client.
In October 2026, company disclosed a dispute with a customer for up to USD 19 mn. This is ~ one year’s worth of operating profits
Boustead Singapore Limited (F9D)
Interesting
Looks attractive: ~ 10% FCFF yield
Management quality seems under-appreciated? Dr. Wong Fong Fui carries good track record of turning around businesses
Why cash ~ 50% of revenue?
More capital returns? Returning more cash to shareholders after listing of UI Boustead REIT
Bukit Sembawang Estates Limited (B61)
Pass
Historically, FCFF yield averages ~ 5%
Property development is a very capital intensive business
Bumitama Agri Ltd. (P8Z)
Uncertain
I have to admit: the crude palm oil (CPO) industry is new to me
Working capital trends, crude palm oil (CPO) pricing and capex trends suggest the CPO industry may be entering a shortage?
Current FCFF yield of ~ 10% doesn’t seem that attractive compared to Indonesia’s 10y government bond yield of 7.6%
Might relook into this when I learn more about the CPO industry. Looks very interesting
Centurion Corporation Limited (OU8)
Pass
Provides Purpose-Built Workers Accommodation (PBWA)
Very capital intensive business
Share price rallied due to shortage of beds after COVID-19 lockdowns ended
FCFF yield ~ 5.5% suggests the market is expecting more growth
But growth seems likely to decelerate.
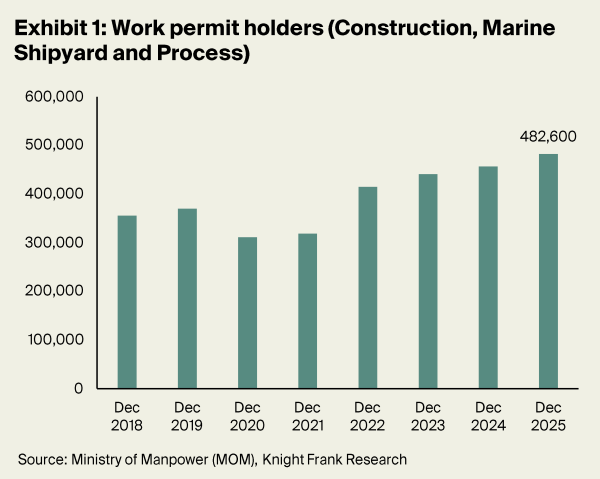
Work permit holders starting to plateau in 2025, and expected to remain around this range:3
More beds expected to come online over the next few years