

[Pass] Canada Goose Holdings Inc. (GOOS CN)
Last week, you highlighted a potential opportunity in GOOS. What’s your suggestion?
Pass on GOOS.
Initially, GOOS looked like a good business with temporary headwinds. It seems to be making good progress in destocking excess inventory.
However, I am concerned about the competition from Chinese brands like Bosideng. The rise of Chinese brands is a pervasive and persistent trend.
I also wonder why wholesale customers are taking longer and longer to pay (all-time high ~ 4 months).
Since my first analysis last week, short interest has increased from 12% to 14%.
Nonetheless, shorting GOOS is not a good idea. The company received takeover offers last year, and the major shareholders seem keen to sell.
Liquidity?
21 Oct 2026
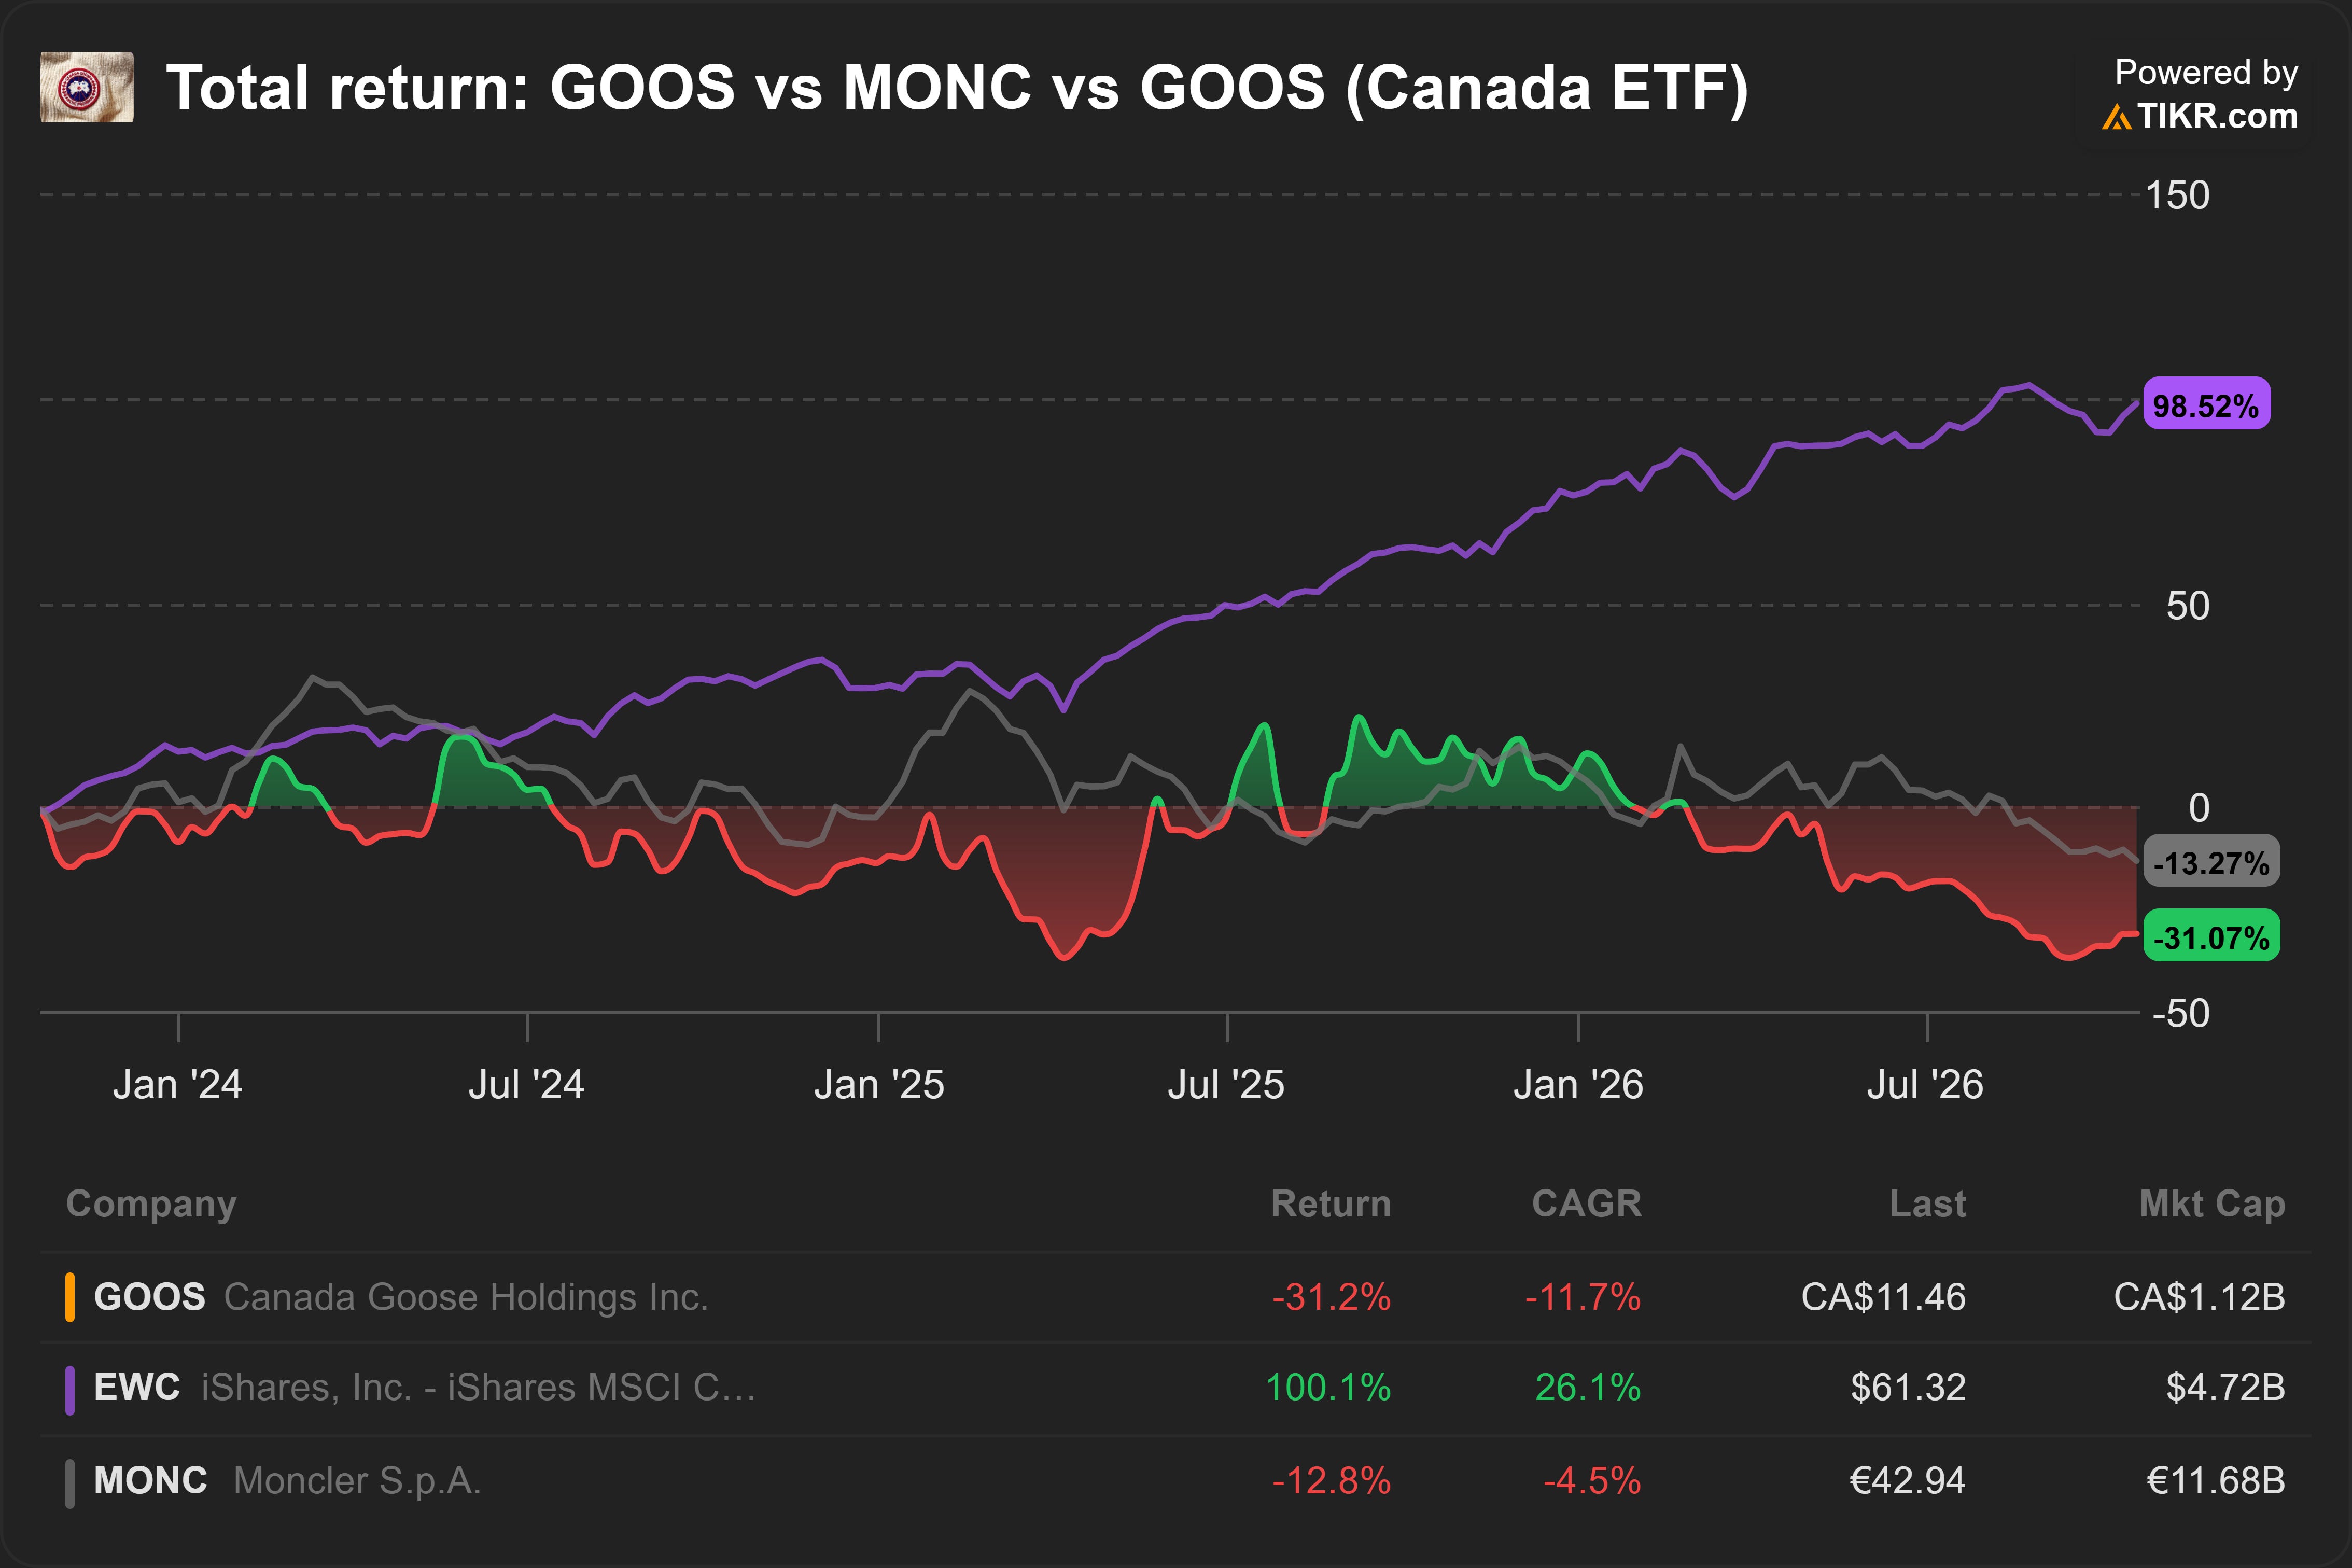
Share price: CAD 11.46
Market capitalisation: CAD 1,119 mn (USD 797 mn)
Enterprise value (EV): CAD 1,763 mn (USD 1,255 mn)
Average daily volume (ADV): CAD 3 mn (USD 2 mn)
NTM P/E: 12x
What does GOOS do?
GOOS manufactures and sells luxury performance outerwear. It is famous for its parkas.
It earned CAD 1,528 mn revenue in FY2026 (+13% YoY):
76% direct-to-consumer (DTC) (+16% YoY)
19% wholesale (+12%)
5% Others (-10%)
What’s your first reason for passing GOOS?
Intense Competition from Chinese Rivals
China is GOOS’ largest and fastest-growing market.
In FY2026, it grew +17% YoY to reach 33% of revenue. Investors are understandably excited over GOOS’ growth prospects in China.
However, I believe they are under-estimating the headwinds Western brands face from local competitors.
In China, consumers increasingly prefer Asian, especially local brands over Western brands. This is a pervasive and persistent trend, driven by growing nationalism (国潮) and quality improvements at Chinese brands.
CNA reports:1
Customer Phoebe Ma, 24, said that when her mother’s generation was young, China “wasn’t so developed” and people were initially familiar with only a handful of luxury brands.
“Consequently, they formed a deep-seated impression that, okay, Louis Vuitton was the absolute best and most prestigious,” the freelancer told AFP.
“I just feel that the (LV) monogram is dated. It suits my mother’s generation, but Gen Z would rather buy trendy Korean brands,” she said.
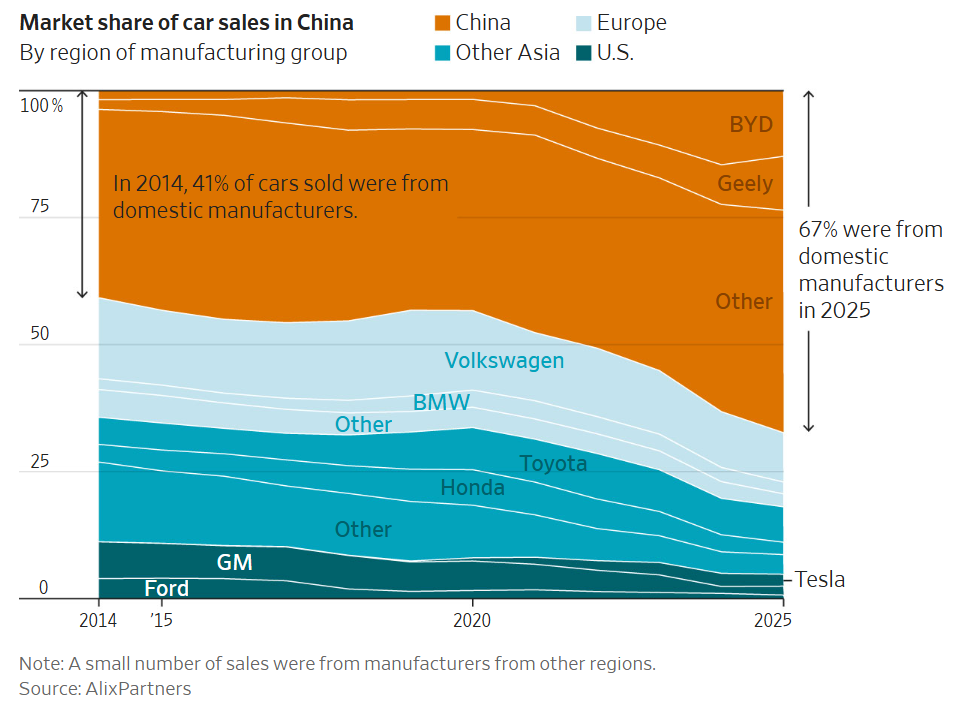
Chinese car brands are also taking market share from Western carmakers:2
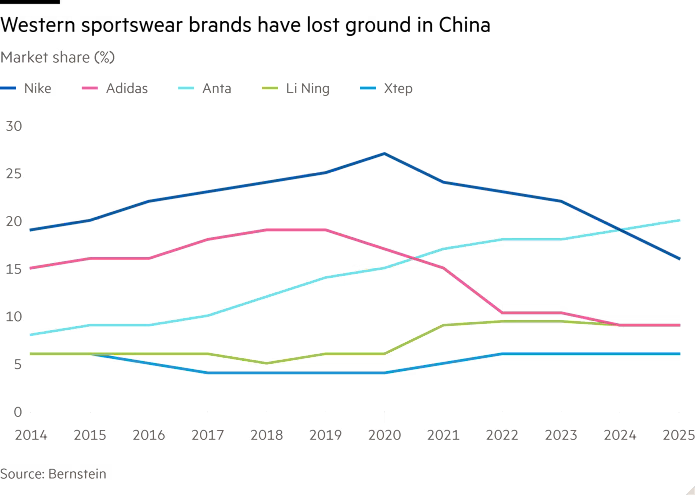
We talked before about how Chinese brands like Anta, Li Ning and Xtep are taking market share from Western brands.
Last month, The Financial Times reported:3
The rise of Chinese brands is not purely based on nationalism. Better quality at lower costs means they are making inroads to international markets too.
Bloomberg reports:4
In fountain pens, Chinese manufacturers including Asvine and Hongdian compare favorably to European and Japanese brands, winning praise from collectors for aesthetics and writing performance at a fraction of the cost.
In folding pocket knives, WE Knife Co. and Reate Knives, which started out as manufacturers for other brands, have earned acceptance with their own designs that rival or exceed the fit and finish of the priciest US and European makers.
The rise of Chinese brands is a pervasive and persistent trend. It’s not a trend to bet against.
Bosideng, GOOS’ main Chinese rival, started pushing into the premium market.
In 2025, ex-Dior designer Kim Jones joined Bosideng, a strategic move that underscores the company’s ambitions to conquer the high-fashion outerwear market.5
Although China is GOOS’ most important and best-performing market so far, I believe there is a higher-than-expected risk of an eventual slowdown.
Your second reason to pass concerns wholesale customers. What about it?
Surging Receivables
Wholesale customers are taking longer and longer to pay their invoices. In FY2026, I estimated receivable days reached 115 days, an all-time high.