

Every week, I share my first take on 2 to 3 attractive ideas.
As usual, if you want me to dig deeper into an idea, vote for it. Use the poll at the end of this email.
Universal Vision Biotechnology Co., Ltd. (3218 TT)
UVB is the largest provider of eye care in Taiwan.
Over the past two years, shares sold off as myopia cases caused by lockdowns started to normalise.
At today’s valuation, the market seems to be pricing UVB like a low-growth business (~10% FCFF yield, 8% premium over Taiwan 10y government bond).
However, investors are ignoring the structural growth trends: (a) aging population; (b) myopia continues to become more prevalent
High frequency data and working capital trends support a re-acceleration of revenue growth in 2026. This exceeds sell-side forecasts.
About (6 Nov 2026)
Share price: TWD 126.50
Market capitalisation: TWD 10,718 mn (USD 326 mn)
Enterprise value (EV): TWD 11,227 mn (USD 342 mn)
Average daily volume (ADV): TWD 25 mn (USD 1 mn)
NTM P/E: 9x
UVB provides vision care services in Taiwan and China through partner clinics.
It is the largest player, with ~ 50% market share in the refractive surgery market. The market share trend is stable.
In 2025, the company earned TWD 4,204 mn revenue (-1% YoY):
50% partner clinic services
26% product sales revenue
15% medical consumables revenue
5% rental revenue
4% consulting revenue
Partner clinic services involve providing brand licensing, technical consulting, medical equipment leasing, and management services to 29 affiliated eye clinics.
These clinics are owned by individual doctors performing SMILE LASIK, cataract surgeries, and orthokeratology (OK) lens fittings.
This business model is high margin, similar to Pets at Home’s Vet segment. We talked about PETS LN in July 2026.
Product sales revenue involves direct retail sales of prescription glasses, fashionable eyewear, and myopia control products across 31 self-owned optical stores.
Under-recognised growth?
My initial estimate suggests ~ 10% long-term free cash flow yield on enterprise value (FCFF yield), ~ 8% premium over Taiwan’s 10-year government bond. Looks attractive.
Over the past 3 years, UVB (3218 TT) underperformed the broader Taiwan market.
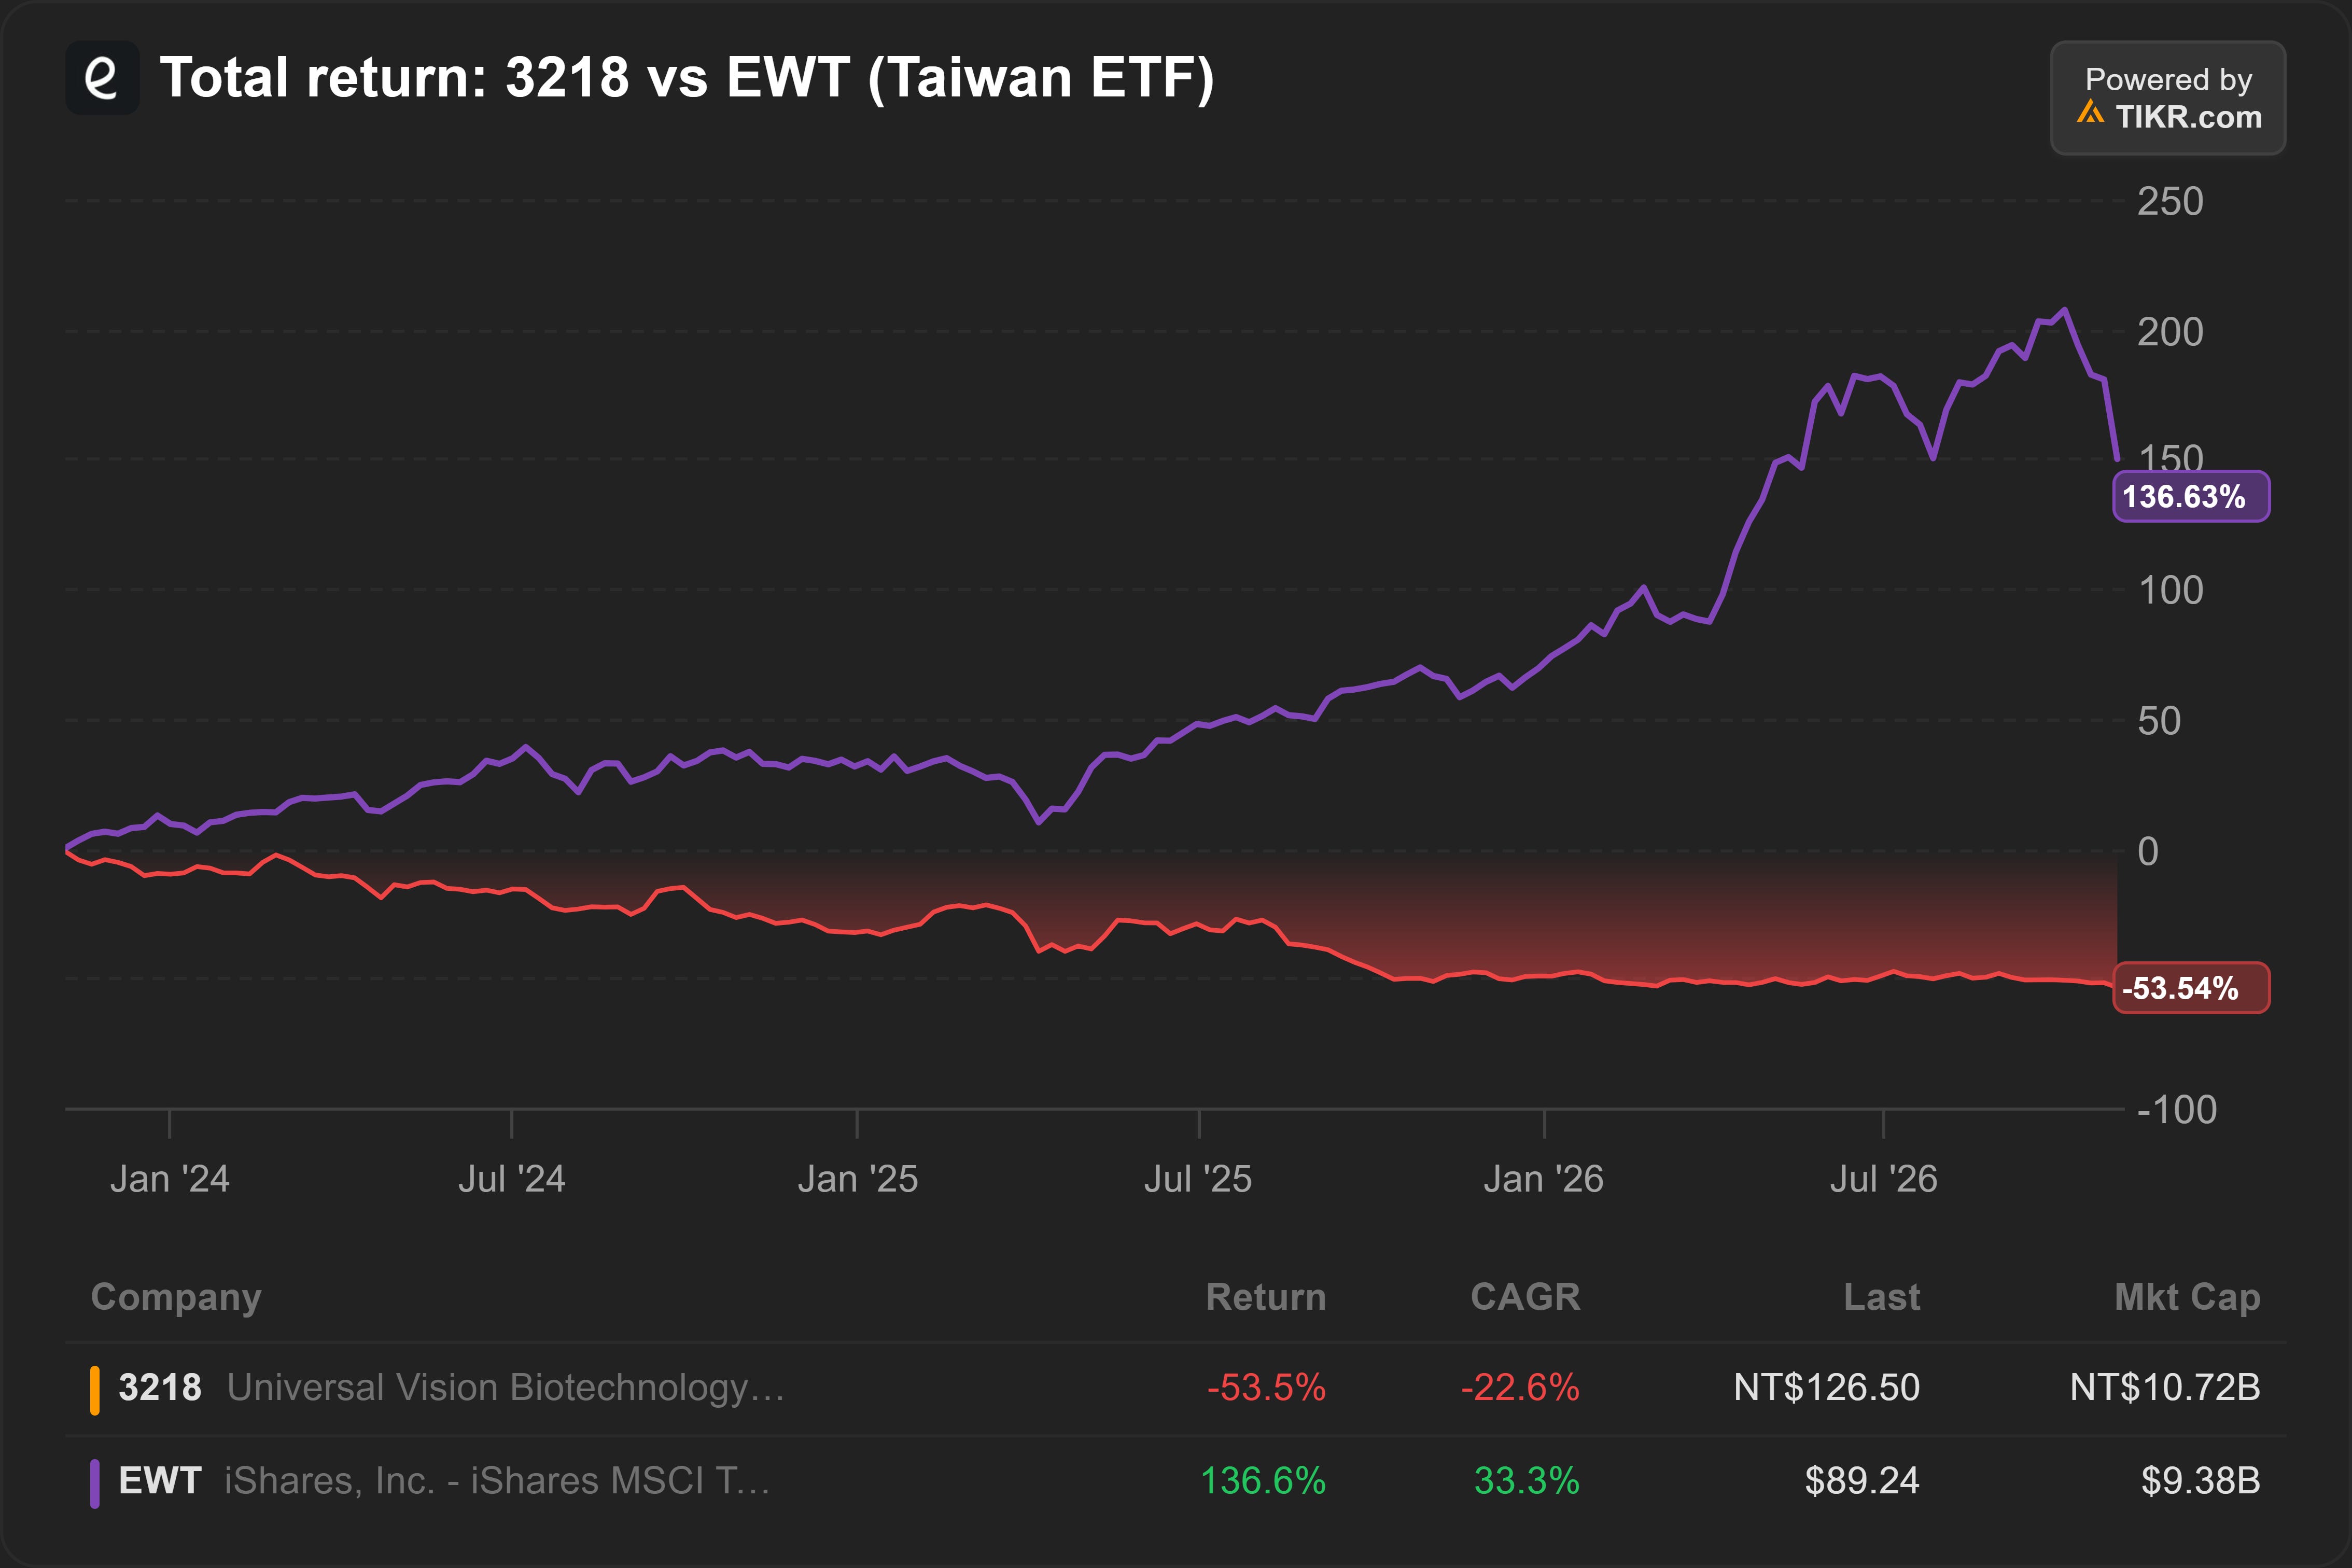
Revenue growth decelerated after COVID-19. Taiwan’s semiconductor boom also drew capital away from other sectors like healthcare.
At today’s valuation, the market seems to be pricing UVB like a low-growth business. There seems to be only 1 sell-side analyst covering this business. That analyst is forecasting +1% revenue growth in 2026, and +4% in 2027.
UVB estimates its overall market will grow between 6% and 7% through 2029.
Taiwan’s aging population will drive higher demand for cataract surgery.
Myopia is becoming more prevalent in Taiwan and China.1 Technological advancements such as SMILE Pro 3.0 Max and EVO ICL for high myopia lead to increasing public acceptance of minimally invasive procedures.2
Indeed, higher frequency data and working capital trends show revenue growth is re-accelerating.
Monthly revenue grew +11% YoY during September 2026. Between January and September 2026, revenue grew +7% YoY.3
Advance payments from customers increased +80% YoY in Jun 2026.
Factors to focus on
Growth potential and ability to capture more market share?
Any regulatory threats?