

Every week, I share my first take on 2 to 3 attractive ideas.
As usual, if you want me to dig deeper into an idea, vote for it. Use the poll at the end of this email.
Quick note: Asian Century Stocks (ACS) featured my analysis on Li Ning (2331 HK)1. ACS is the top Substack for Asian value stocks. I appreciate the shout-out. Look mum, I’m famous!
#1: Jet2 plc (JET2 LN)
JET2 is the UK’s top budget airline and tour operator.
The shares have sold off over fears of weaker travel demand.
At today’s valuation, the market seems to be pricing it like a low-growth business (~16% FCFF yield, 10% premium over UK 10y gilt).
However, there are 3 factors suggesting under-recognised growth:
Apollo, a PE firm, is acquiring JET2’s peer at 23x NTM P/E. JET2 is trading at 11x
JET2 is under-penetrated in South UK, and is working to increase penetration there
Advance payments from customers continued to grow
After many years of hoarding cash, management started buying back shares.
PE firms are interested in this sector. Apollo just acquired EZJ, JET2’s peer.
About (13 Nov 2026)
Share price: GBP 15.10
Market capitalisation: GBP 2,789 mn (USD 3,686 mn)
Enterprise value (EV): GBP 1,638 mn (USD 2,167 mn)
Average daily volume (ADV): GBP 8 mn (USD 11 mn)
NTM P/E: 11x
JET2 is a British low-cost airline. It also operates as the country’s largest tour operator.
In FY2026 (year ending 31 March 2026), it earned ~ GBP 7,482 mn revenue (+4% YoY):
80% Package holidays (+3% YoY)
11% Flight-only tickets (+8% YoY)
9% Others (+9% YoY)
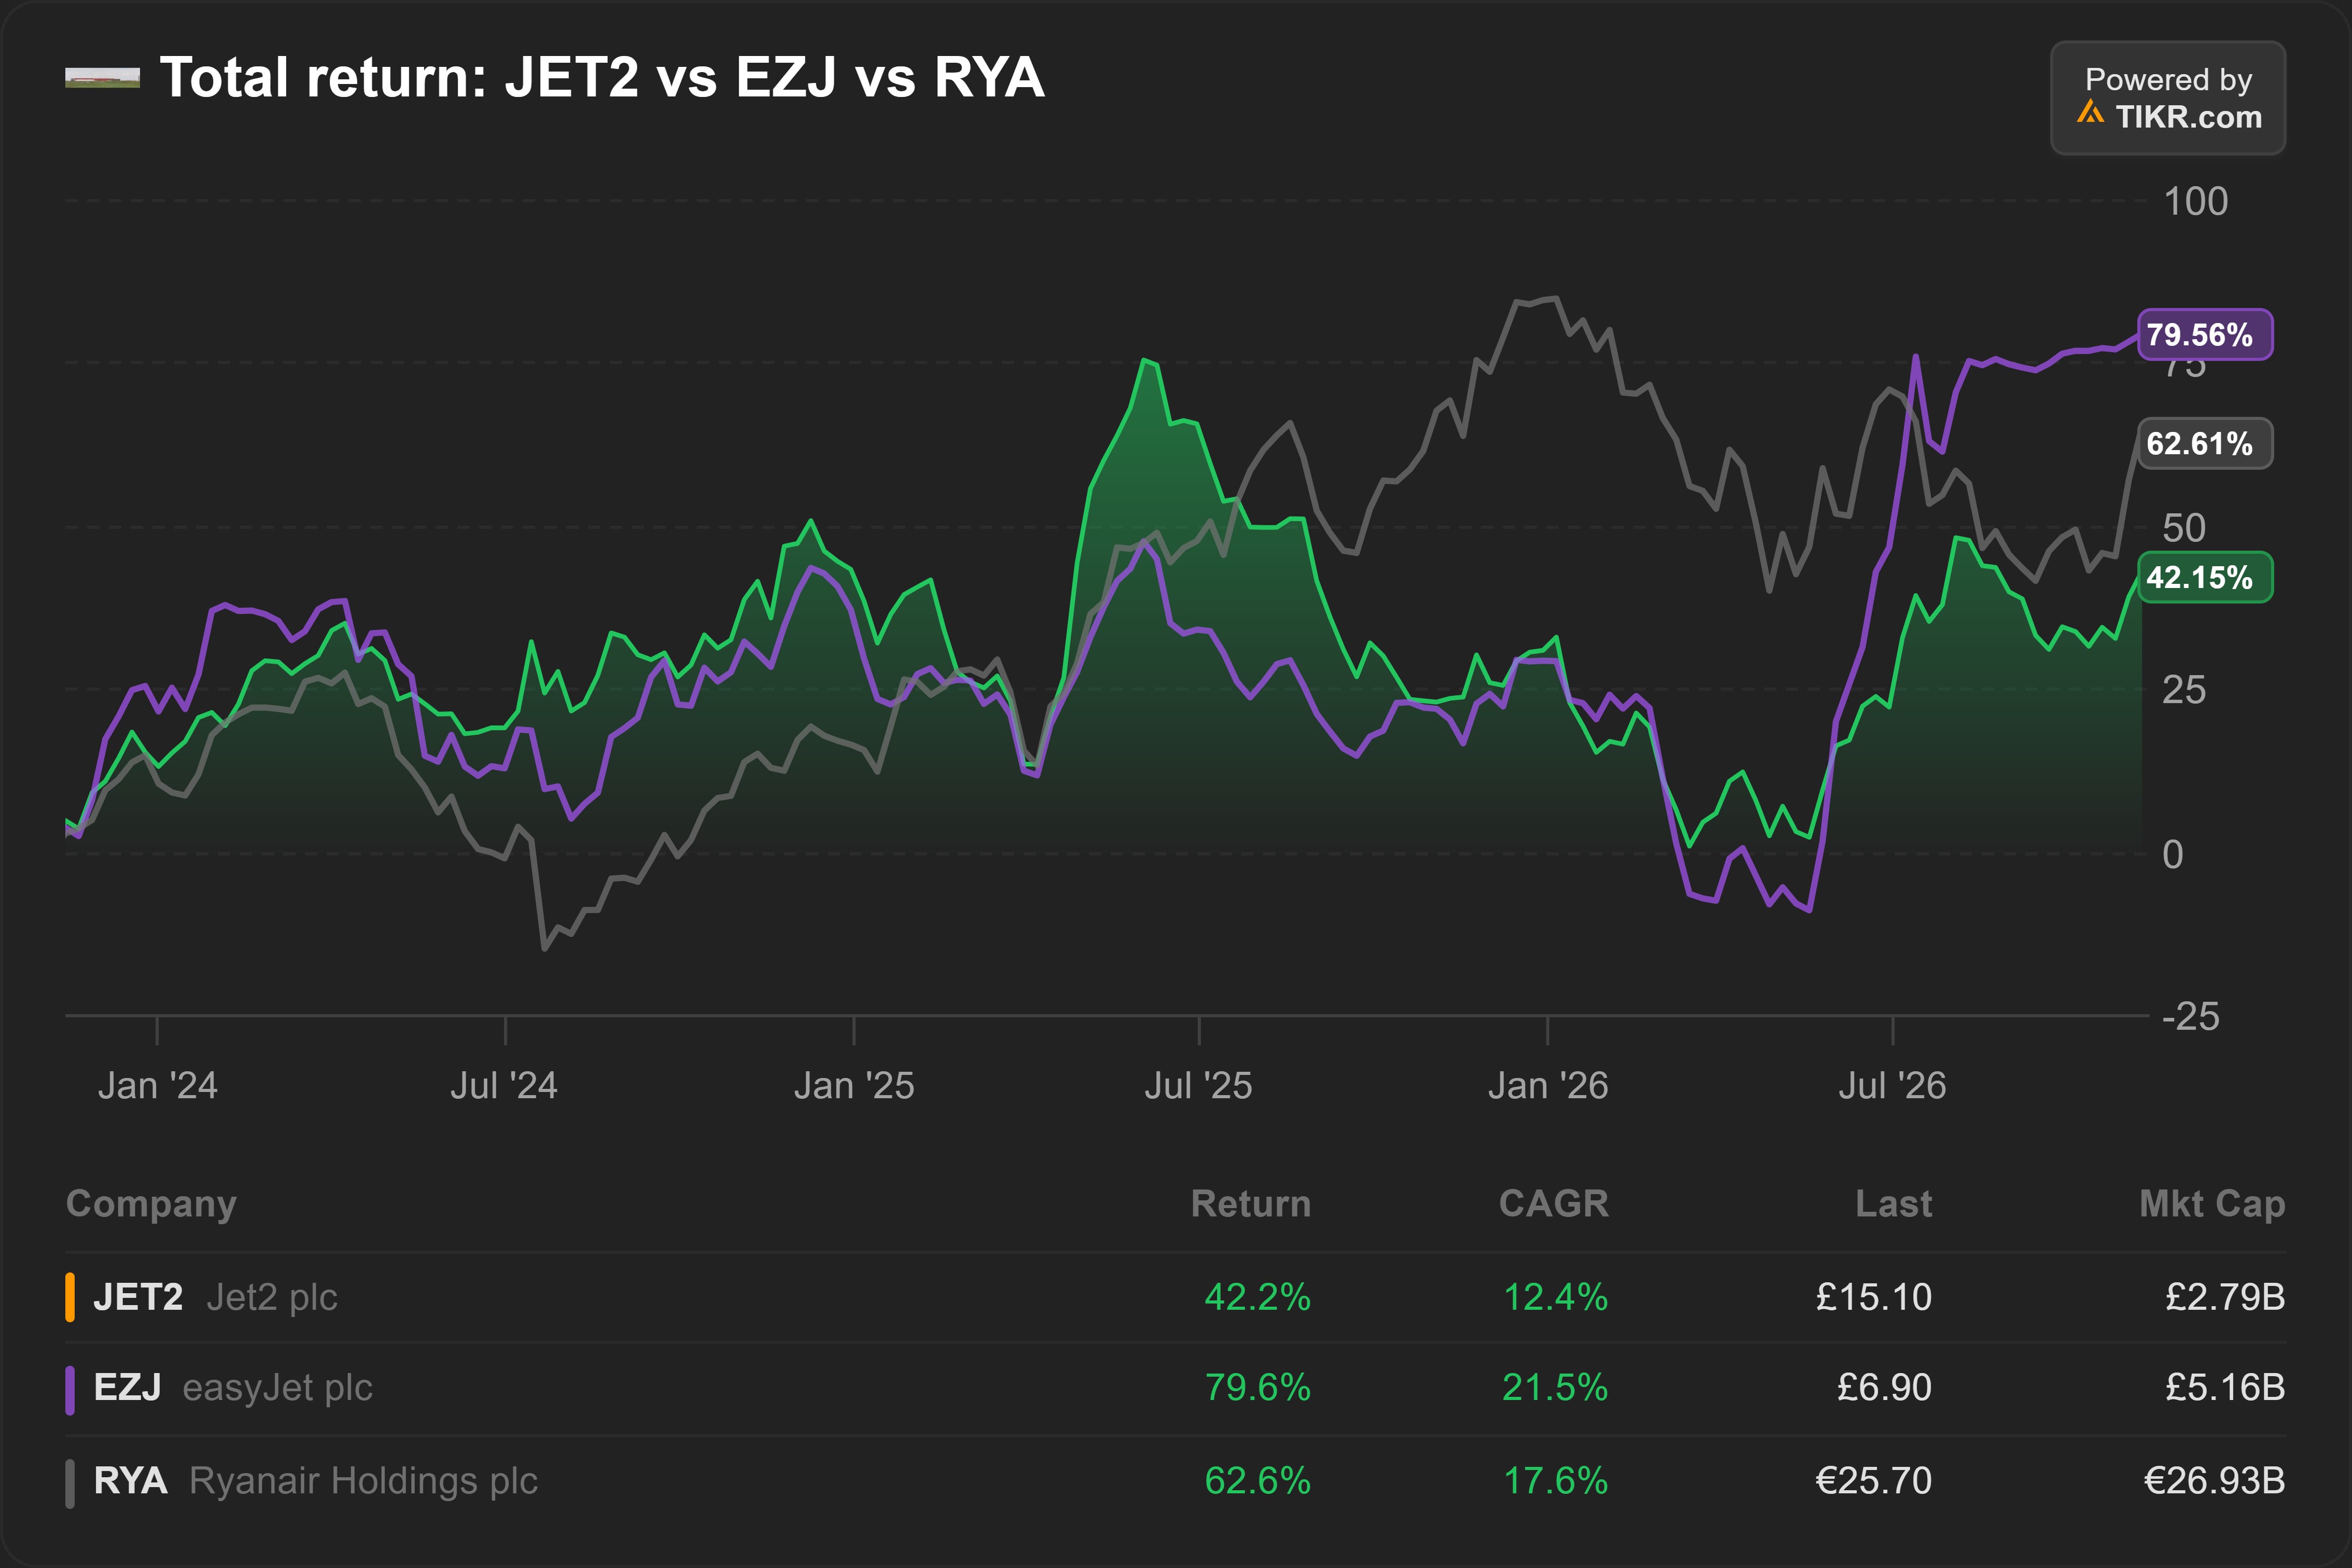
In July 2025, JET2 shares sold off after it warned of weaker demand and higher regulator costs. Shares in UK peer, easyJet plc (EZJ LN) followed the same trend. Ryanair Holdings plc (RYA ID) has less exposure to UK, and so was less impacted.
JET2 shares started recovering around July 2026 after it reported better-than-expected bookings.
Under-recognised growth?
My initial estimate suggests ~ 16% long-term free cash flow yield on enterprise value (FCFF yield), ~ 10% premium over UK 10-year gilt.
Such a large premium usually suggests declining future free cash flow.
However, there are 3 factors that suggest growth":
(1) Private buyers. In August 2026, Apollo, a private equity (PE) firm, offered to buy EZJ at 23x NTM P/E. This is more than twice JET2’s 11x NTM P/E.
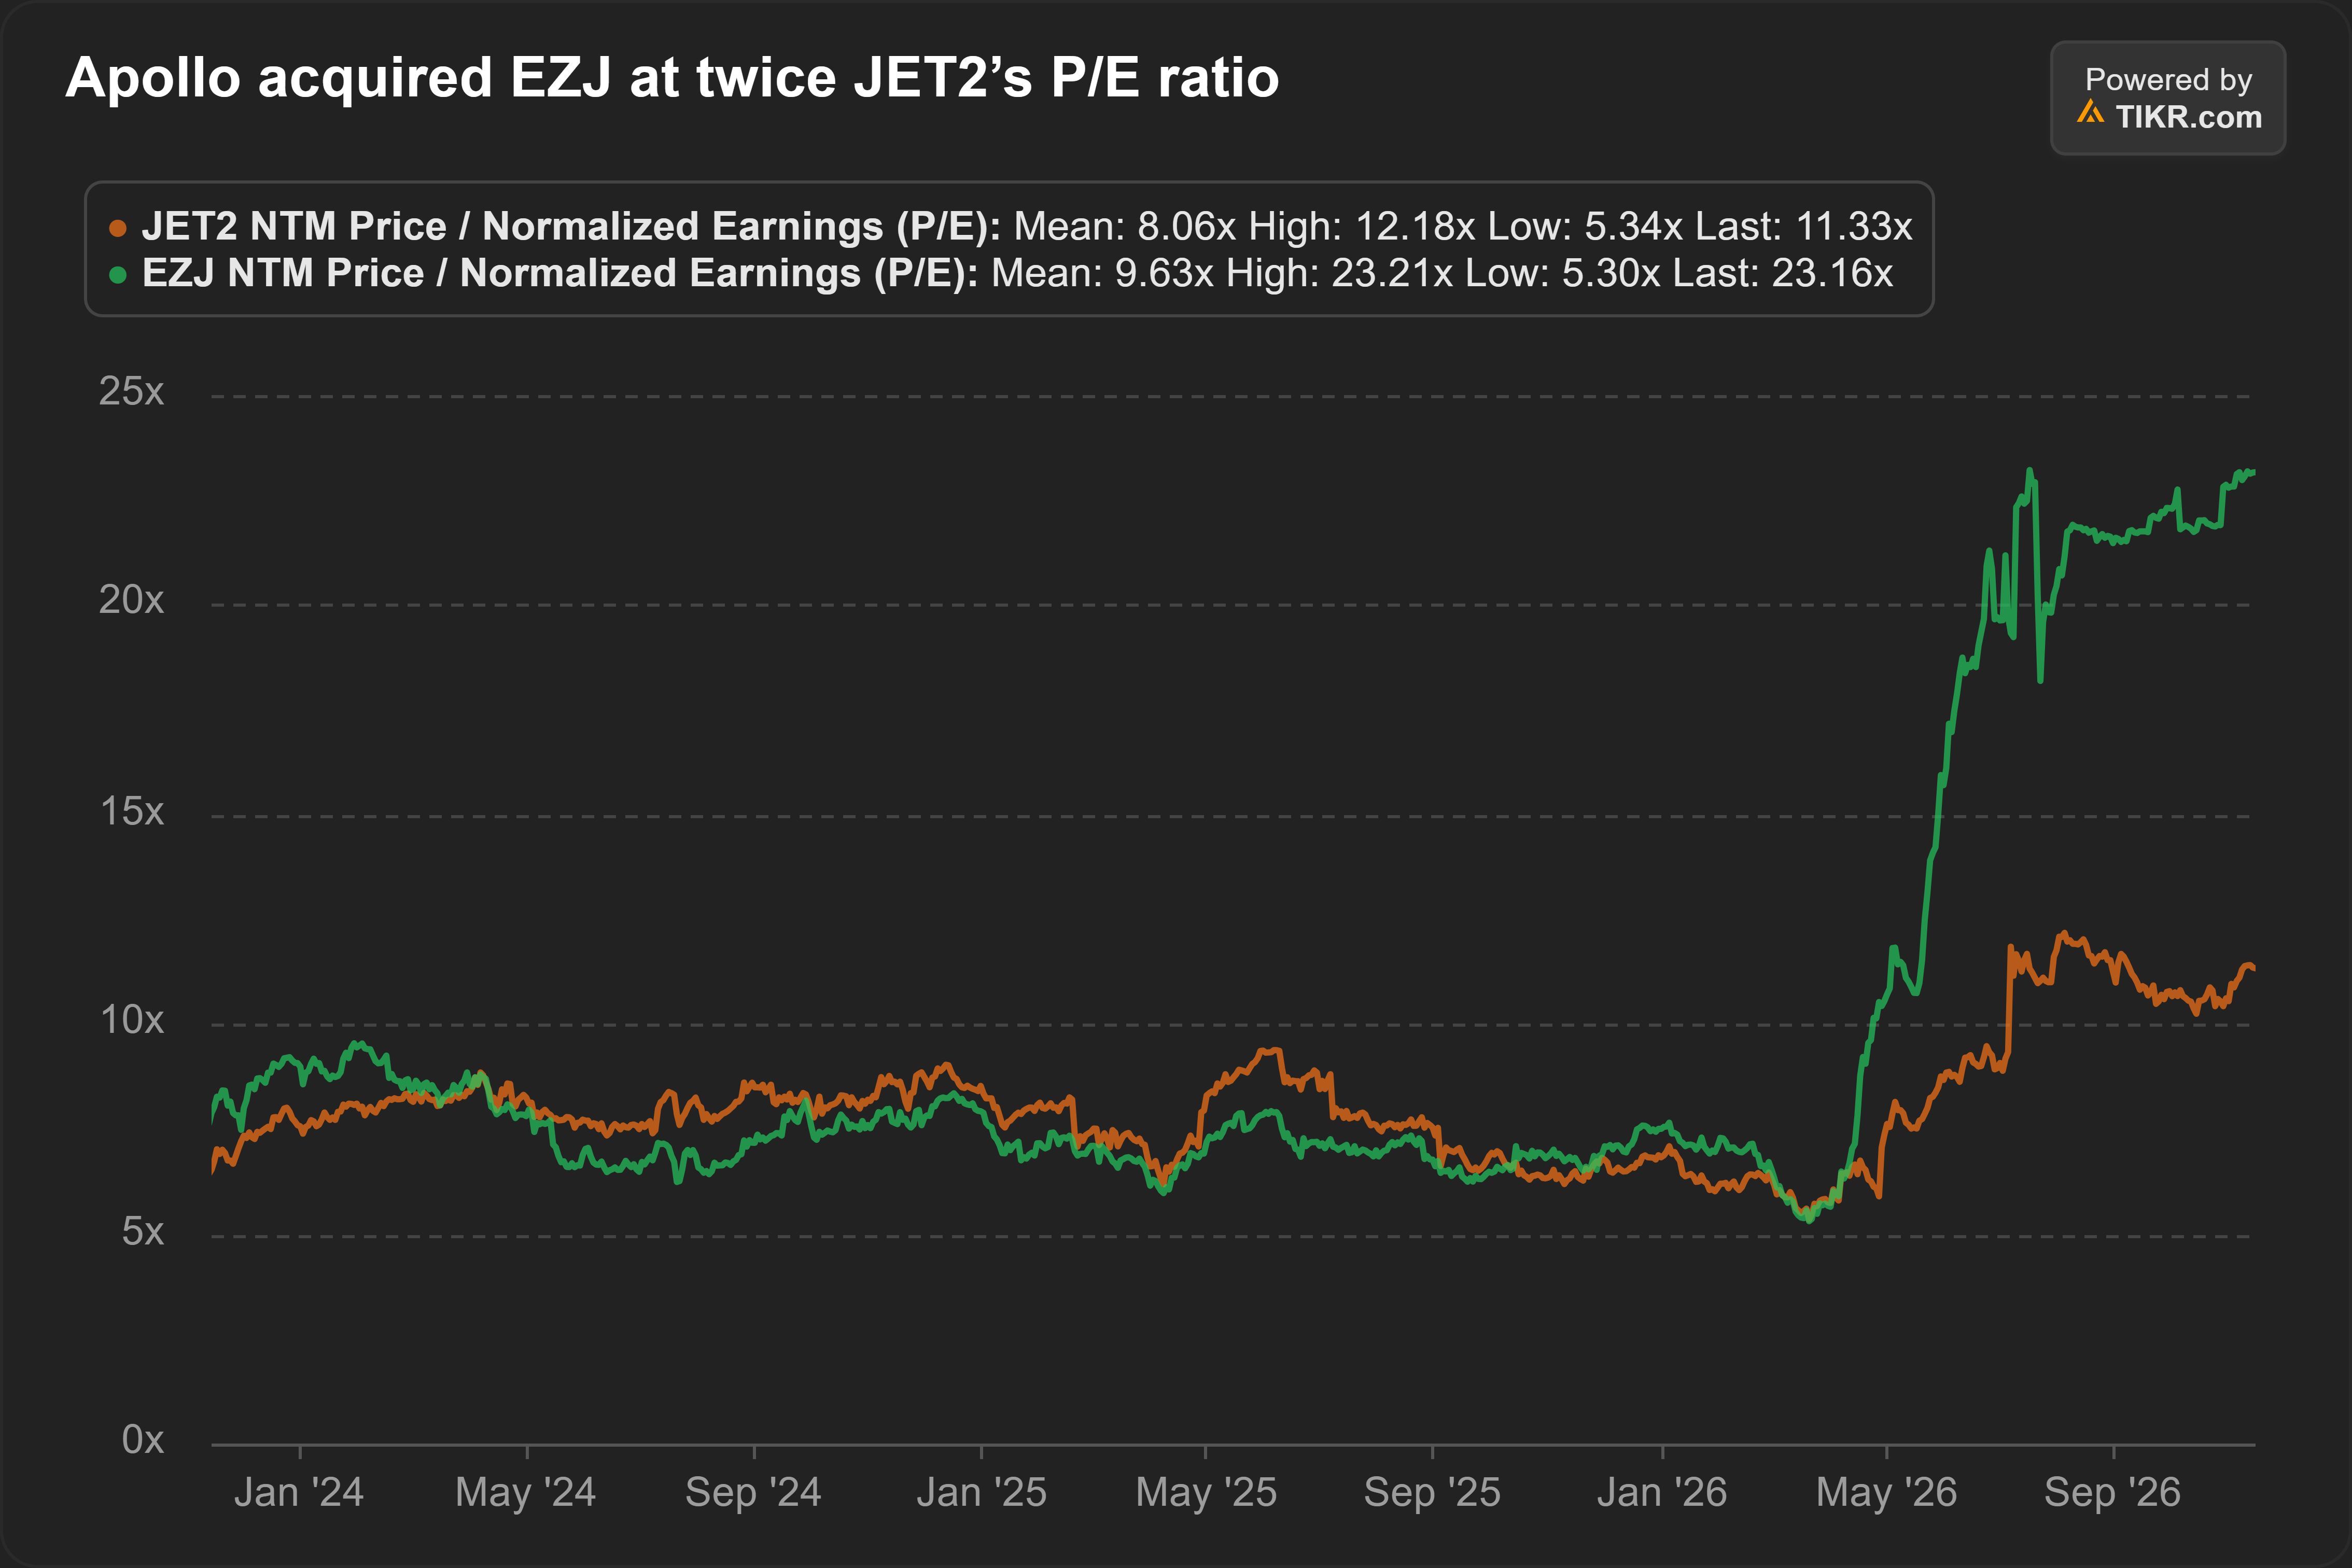
The PE firms have likely seen some growth drivers that the public investors overlooked. What are they?
(2) Increasing penetration. While dominant in North England, JET2 is under-penetrated in London and the South.
Its March 2026 launch at London Gatwick Airport aims to increase its penetration in the South. Management expects this to turn profitable by FY2029.
Meanwhile, competitors are retreating from JET2's core regional bases (e.g., easyJet exiting Leeds Bradford in January 2027).
(3) Favourable working capital trends. Advance payments from customers continued to grow in FY2026 (+2% YoY), albeit slower than the 10% YoY growth in FY2025.
Capital return?
JET2 is returning excess cash to shareholders.
In April 2025, it launched a GBP 250 mn share buyback program (~9% of market capitalisation) and extended by another GBP 100 mn in November 2025.
In July 2026, JET2 launched another GBP 250 mn share buyback program. This is ongoing.
By working backwards from its cash target, I estimate JET2 has the liquidity to launch another GBP 350 mn buyback (~ 13% of today’s market capitalisation).
Potential takeover?
In August 2026, EZJ agreed to a takeover by Apollo, after a bidding war against another PE firm, Castlelake.2
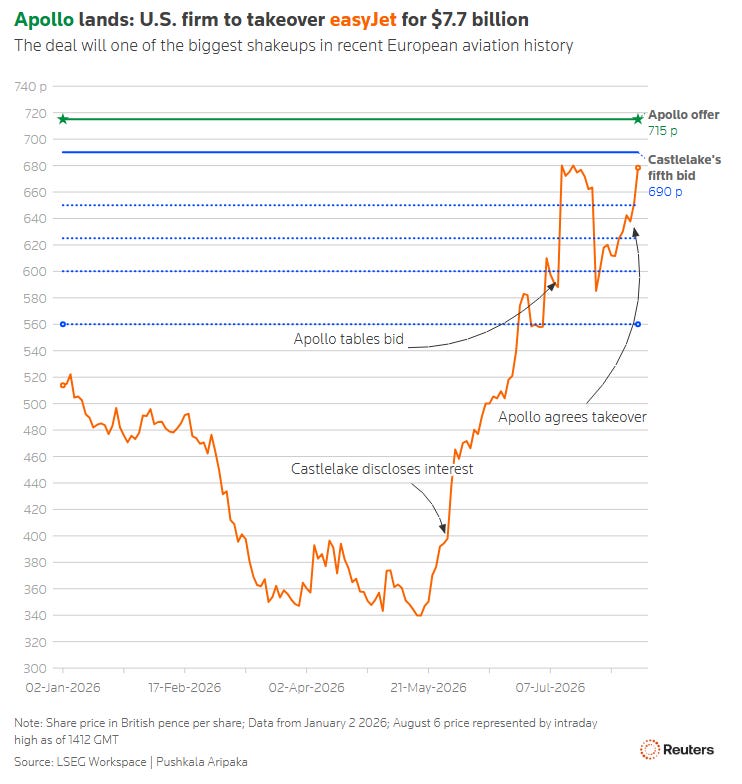
Source: Reuters (2026)
With JET2 trading at almost half the valuation of Castlelake’s bid for EZJ, could Castlelake look at JET2 next?
Factors to focus on
Where are we in the UK airline cycle? Look at the trends in demand vs supply
Risks from rising jet fuel costs?
JET2 systematically hedges its jet fuel requirements. It has hedged ~ 90% of its jet fuel costs for the rest of FY2027.
However, if jet fuel prices remain high for a long time, the higher costs will eventually reach JET2.
As we have seen in Asia, budget airlines are more vulnerable to high fuel prices.3 Lower margins mean less room to absorb higher costs while price-sensitive customers limit how much costs can be passed through.
Thought of the day
Some “growth” investors don’t really understand growth.
Let’s say I earn $50 million annual profits.
If investors give me $1 billion, I can easily show them 100% growth.
I’ll just park it in 5% Treasury bond!