

Every Monday, I share my first take on 2 to 3 attractive ideas. (Sorry for the delay this week)
As usual, if you want me to dig deeper into an idea, vote for it. Use the poll at the end of this email.
MEITEC Group Holdings Inc. (9744 JP)
At ~ 8% long-term free cash flow yield, the market is pricing Meitec like a cyclical business, just like any other HR firm in the world.
However, the labour market in Japan is different. A shrinking population means the labour shortage is persistent. This trend is unlikely to change.
Operating profit growth at Meitec will likely continue at low to mid single digit. Yet, investors are still pricing it like a cyclical business.
PE firms have taken over many of its peers. Meitec is one of the few remaining publicly listed company in the sector.
About (2 Nov 2026)
Share price: JPY 3,222
Market capitalisation: JPY 246,675 mn (USD 1,173 mn)
Enterprise value (EV): JPY 196,879 mn (USD 993 mn)
Average daily volume (ADV): JPY 1,482 mn (USD 10 mn)
NTM P/E: 18x (excludes non-recurring impairment)
Meitec hires engineers as full-time permanent employees. It then dispatches (‘rents’) them out to work directly inside the R&D labs of blue-chip corporations like Toyota, and Mitsubishi Heavy Industries.
Meitec charges clients a premium hourly rate (~ JPY 5,400 to JPY 5,800 per hour per engineer). After paying the engineer’s salary and corporate overhead, Meitec keeps roughly 27% gross margin and ~15% operating margin (OPM).
Under-recognised growth?
My initial estimate suggests ~ 8% long-term free cash flow yield on enterprise value (FCF yield), ~ 5% premium over Japan’s 10-year government bond. Looks attractive.
At this valuation, the market seems to be pricing Meitec like a cyclical business.
Indeed, the sector is cyclical. Volatility is a feature in the operating profits of global peers like Randstad NV (RAND NA) and Adecco Group AG (ADEN SW):
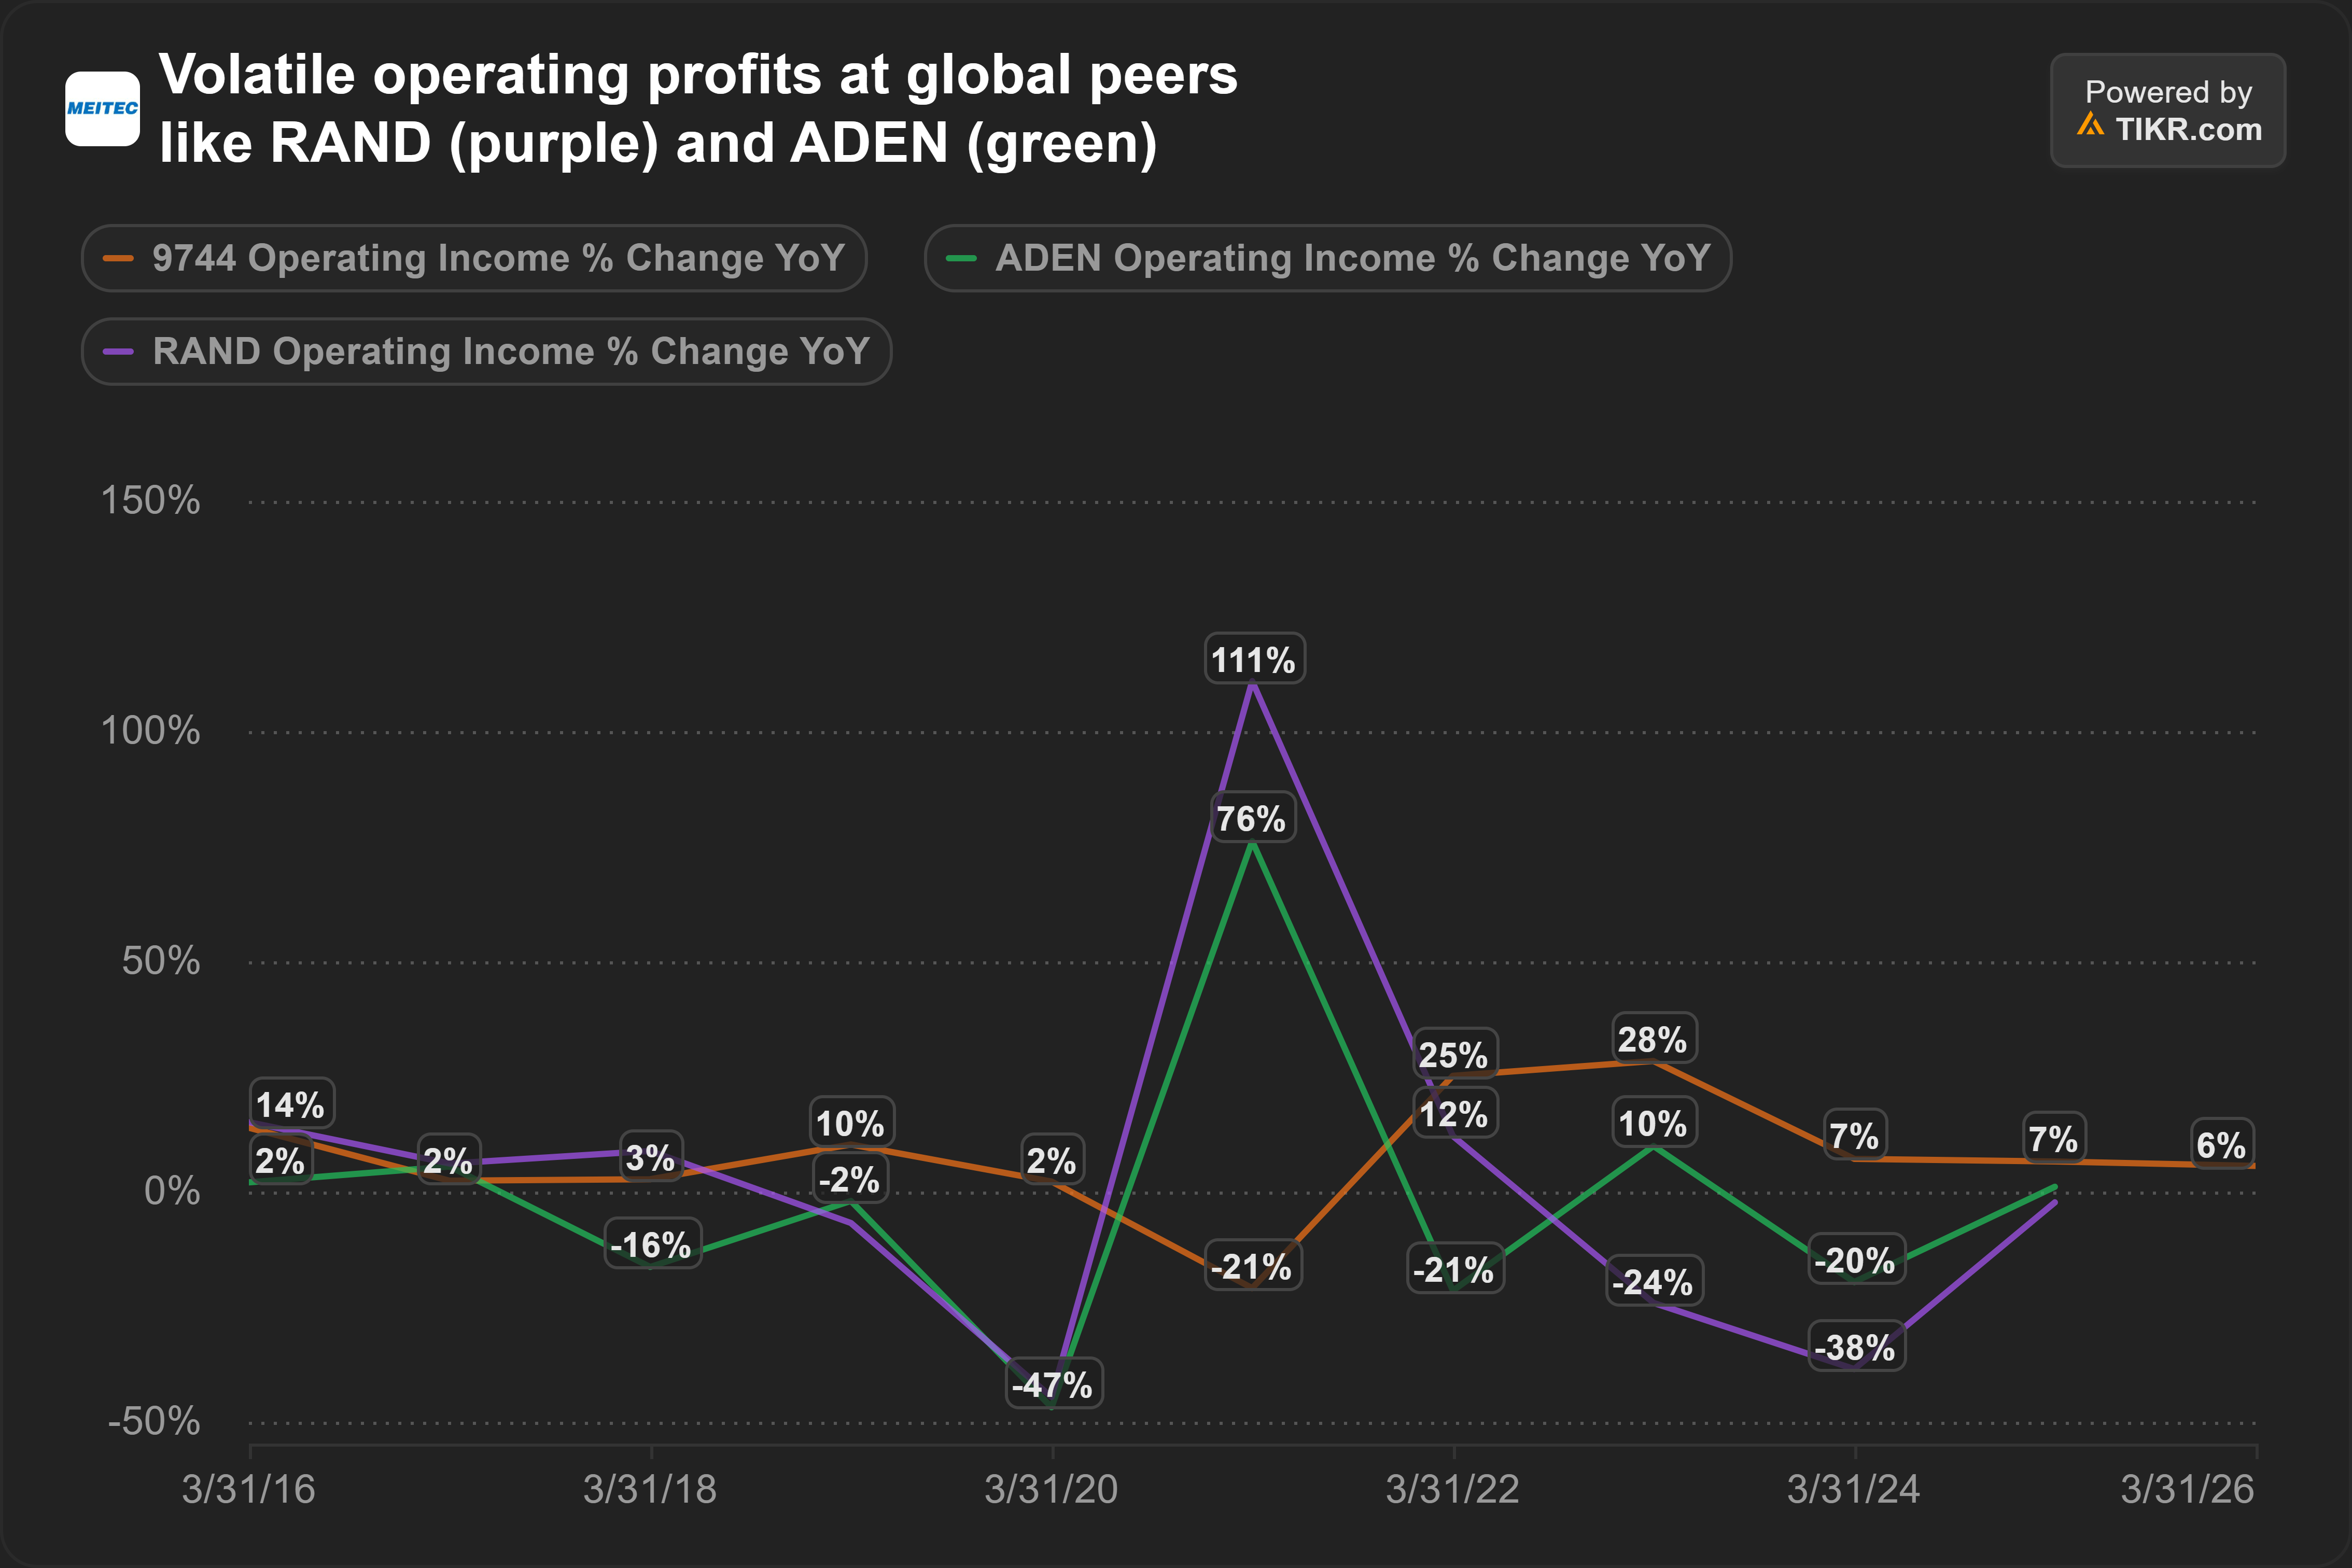
However, Meitec’s operating profits (orange) are much more stable.
Japan’s shrinking working-age population has created a long-term shortage of engineers, boosting the demand for Meitec’s dispatchable engineers.
This demographic change is a long-term trend. Implication?
Meitec becomes less cyclical and its operating profits will likely continue growing around mid-single digit.
If this is true, then 8% FCF yield looks attractive.
Potential takeover?
Private equity (PE) firms have taken over multiple direct peers.
In May 2026, KKR bought Forum Engineering Inc (7088 JP). Blackstone bought TechnoPro Holdings (6028 JP) in Dec 2025. Finally, Bain Capital acquired Outsourcing Inc. (2427 JP) in Jun 2024.
Meitec is one of the few remaining publicly listed companies in the sector.
I believe probability of a takeover is high. Valuation is undemanding. The business is capital-light and carries no debt.
Factors to focus on
Japan’s labour market. Specifically, how sustainable is the shortage of engineers?